3 Reasons to Sell RIG and 1 Stock to Buy Instead Kayode Omotosho Mon, October 12, 2026 at 2:55 PM EDT 3 min read RIG +1.36% ^GSPC -0.12% Trade RIG on Coinbase Trading disclosure Trading disclosure The above button links to Coinbase. Yahoo Finance is not a broker-dealer or investment adviser and does not offer securities or cryptocurrencies for sale or facilitate trading. Coinbase pays us for certain activity generated through this link. Prices displayed are informational.
Over the past six months, Transocean's stock price fell to $5.53. Shareholders have lost 16.8% of their capital, which is disappointing considering the S&P 500 has climbed by 12.8%. This might have investors contemplating their next move.
Even with the cheaper entry price, we don't have much confidence in Transocean. Here are three reasons why RIG doesn't excite us, plus one stock we'd rather own.
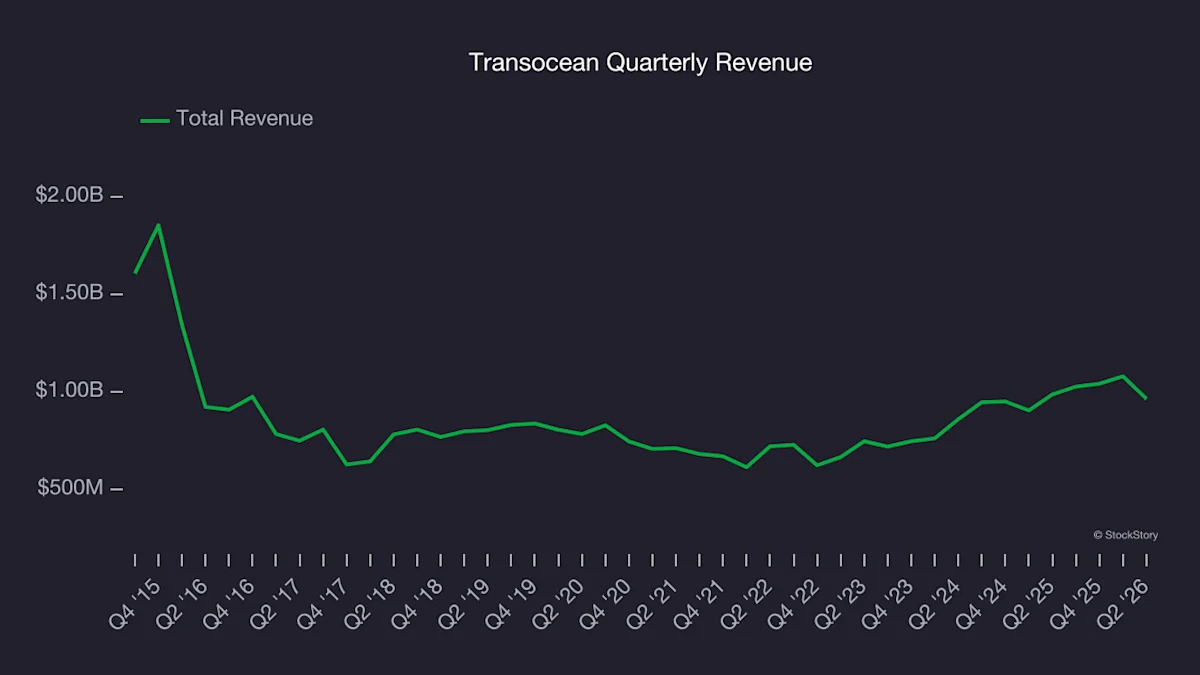
Cyclical sectors like Energy often flatter weaker operators during favorable price environments, but a longer-term lens separates those from businesses that can consistently perform across market cycles. Over the last five years, Transocean grew its sales at a sluggish 6.5% compounded annual growth rate. This was below our standard for the energy upstream and integrated energy sector.
In any given year, energy gross margins are heavily influenced by prices, hedging, and cost inflation, but over a full cycle these gross margins reveal which producers are structurally advantaged through superior "rock" quality, infrastructure access, and cost position.
Transocean, which averaged 38.1% gross margin over the last five years, exhibits poor unit economics in the sector. It means the company will struggle more at lower commodity prices than peers with better gross margins.
If you've followed StockStory for a while, you know we emphasize free cash flow. Why, you ask? We believe that in the end, cash is king, and you can't use accounting profits to pay the bills.
Transocean has shown mediocre cash profitability relative to peers over the last five years, giving the company fewer opportunities to return capital to shareholders. Its free cash flow margin averaged 5.2%, below what we'd expect for an upstream and integrated energy business.
Transocean falls short of our quality standards. Following the recent decline, the stock trades at 29.6× forward P/E (or $5.53 per share). This valuation tells us a lot of optimism is priced in - we think there are better opportunities elsewhere. Let us point you toward one of Charlie Munger's all-time favorite businesses.
ALSO WORTH WATCHING: Top 5 Momentum Stocks. The best time to own a great stock is when the market is finally noticing it. These aren't just high-quality businesses. Something is happening with them right now. Elite fundamentals meet near-term momentum — both boxes checked at the same time.
Find out which stocks our AI platform is flagging this week. See this week's Strong Momentum stocks — FREE. Get Our Strong Momentum Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-micro-cap company Tecnoglass (+1,552% between June 2020 and June 2025). Find your next big winner with StockStory today.