Harsh Chauhan, The Motley Fool Sat, November 14, 2026 at 9:29 AM EST 5 min read CRWV -8.57% NVDA -3.12% Explore stocks on Coinbase Trading disclosure Trading disclosure The above button links to Coinbase. Yahoo Finance is not a broker-dealer or investment adviser and does not offer securities or cryptocurrencies for sale or facilitate trading. Coinbase pays us for certain activity generated through this link. Prices displayed are informational.
CoreWeave (NASDAQ:CRWV) investors have had a forgettable year so far, as shares of the neocloud provider have dipped substantially in recent months following a bright start to 2026.
However, the company's latest results have brought much-needed relief for investors. CoreWeave stock surged almost 25% after releasing its third-quarter results on Nov. 10. Let's see why that was the case, and check if it is worth buying this artificial intelligence (AI) infrastructure company in anticipation of more upside.
Missed AI's "Act 1"? Act 2 Could Be 16x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our analysts, we're only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »
CoreWeave's Q3 revenue shot up by an impressive 168% year over year to $3.66 billion, landing higher than the $3.55 billion consensus estimate. Even better, the company posted a net loss of $0.95 per share, significantly lower than the Street expectation of $1.16.
CoreWeave's guidance played a central role in the stock's post-earnings surge. The company is now expecting adjusted operating income of $1.32 billion in 2026, higher than the consensus estimate of $1.07 billion. It was earlier expecting operating income to land between $960 million and $1.15 billion this year. What's more, CoreWeave has increased its full-year revenue guidance to a range of $13-$13.3 billion, up from the earlier range of $12.4-$13.2 billion.
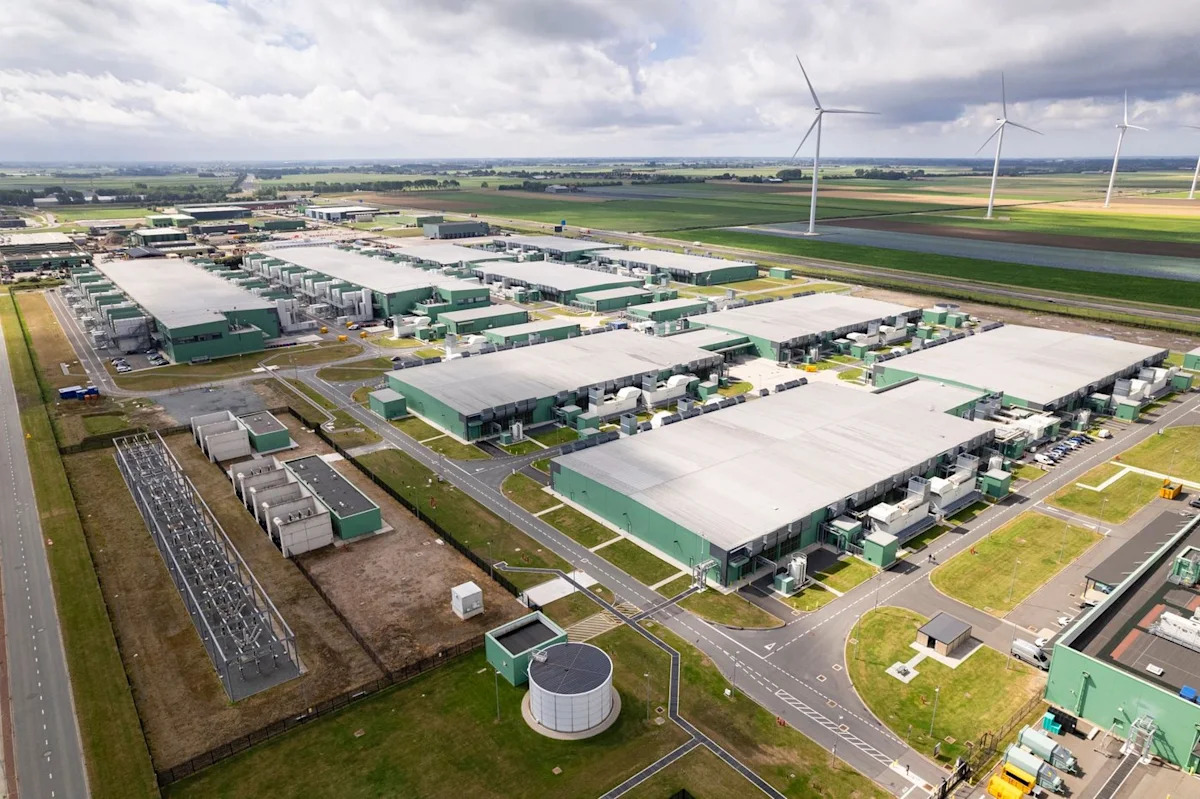
CoreWeave's focus on aggressively adding more data center capacity fueled its terrific results last quarter. The company now has active data center capacity of more than 1.7 gigawatts (MW). It was operating 850 megawatts (MW) at the end of 2025. More importantly, CoreWeave is taking steps to reduce strain on its balance sheet by taking prepayments from customers to fund the build-out of AI data centers.
It expects to collect $9 billion in customer prepayments over the next three months. It is worth noting that CoreWeave has "collected prepayments on 70% of our deals with customers funding up to 100% of the contract value upfront." Management added on the earnings call that these prepayments, along with its ability to internally fund data center development, will help it "fund the significant majority of our capital needs through 2027."
As a result, CoreWeave expects new debt financing to remain below $5 billion through the end of next year, as reported by CNBC. Moreover, CoreWeave is charging customers a significant premium for its data center capacity.
The company is charging $40 million annually per MW of data center capacity under short-term contracts. Long-term contracts with four- to five-year durations are priced in the $20 million to $25 million per MW per year range. Given that an AI-optimized data center reportedly costs $20 million to build, according to energy and AI infrastructure provider Giga Energy, the rent that CoreWeave is charging should help it move toward profitability over the long run.
What's more, CoreWeave ended Q3 with an incredible backlog of $132.5 billion, up 138% from the year-ago period. This strong backlog, the construction of new data centers, and smart financing models should allow CoreWeave to sustain solid growth in 2027 and beyond.
CoreWeave's median 12-month price target of $115 suggests that the stock could soar 89% from current levels. Also, 70% of the 47 analysts covering CoreWeave rate it as a buy. It is easy to see why that's the case, and I won't be surprised to see this AI stock reaching Wall Street's price target.
CoreWeave's robust growth and the decline in its stock price this year have made the stock extremely cheap. It has a price-to-sales ratio of just 3.3. That's a discount to the Nasdaq Composite index's sales multiple of 5. Buying CoreWeave at this valuation is a no-brainer given that its revenue is expected to more than double next year.
CRWV Revenue Estimates for Current Fiscal Year data by YCharts
Assuming CoreWeave's revenue reaches $27 billion next year, and it trades in line with the Nasdaq Composite's sales multiple, its market cap could surge to $135 billion. That's more than 4x its current market cap, suggesting it could deliver greater gains than Wall Street anticipates. So, it isn't too late for investors to buy CoreWeave stock, and doing so could be a smart move given its terrific upside potential in 2027.
The Motley Fool Stock Advisor analyst team just identified what they believe are the 10 best stocks for investors to buy now… and CoreWeave wasn't one of them. The 10 stocks that made the cut could produce monster returns in the coming years.
Consider when Netflix made this list on December 17, 2004... if you invested $1,000 at the time of our recommendation, you'd have $335,171!* Or when Nvidia made this list on April 15, 2005... if you invested $1,000 at the time of our recommendation, you'd have $1,000,640!*
Now, it's worth noting Stock Advisor's total average return is 823% — a market-crushing outperformance compared to 208% for the S&P 500. Don't miss the latest top 10 list, available with Stock Advisor, and join an investing community built by individual investors for individual investors.
*Stock Advisor returns as of November 14, 2026.
Harsh Chauhan has no position in any of the stocks mentioned. The Motley Fool has no position in any of the stocks mentioned. The Motley Fool has a disclosure policy.
Prediction: This Will Be CoreWeave's Stock Price After 1 Year Following Its Stunning Results (Hint: It Implies a Big Move) was originally published by The Motley Fool