AMD Stock Looks Poised to Revisit Its All-Time Highs TipRanks Fri, November 13, 2026 at 4:16 PM EST 6 min read AMD -10.03% ANT META +2.47% MSFT -0.24% MSF Explore stocks on Coinbase Trading disclosure Trading disclosure The above button links to Coinbase. Yahoo Finance is not a broker-dealer or investment adviser and does not offer securities or cryptocurrencies for sale or facilitate trading. Coinbase pays us for certain activity generated through this link. Prices displayed are informational.
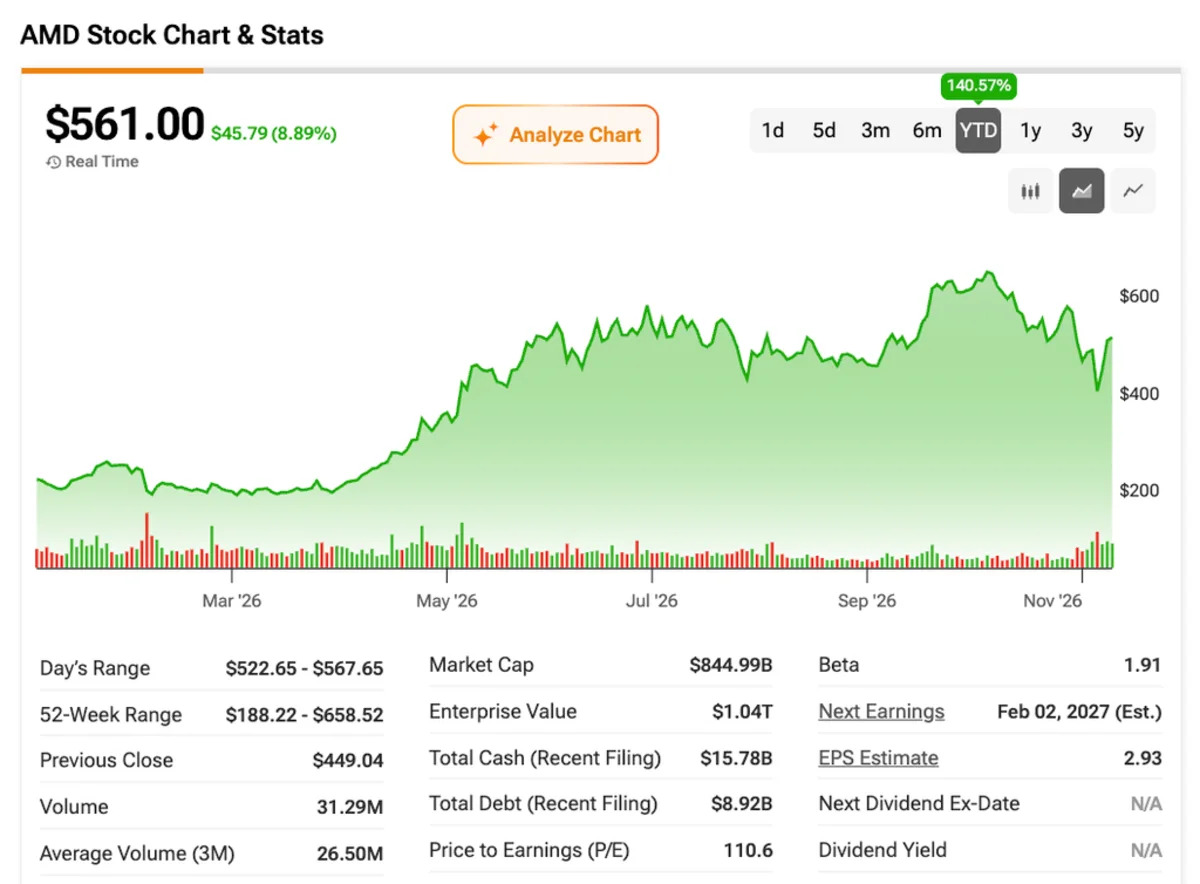
Advanced Micro Devices' (AMD) stock looks poised to revisit its all-time highs. The market has already bought into its growth story. Now, the next opportunity may lie in how much of that growth turns into profits. After a triple-digit gain in 2026, the stock has pulled back from its October record highs, but the fundamentals help explain much of that rally.
In its third-quarter earnings report, released on November 3, the Santa Clara, California-based chipmaker reported that its Data Center revenue nearly doubled, along with a great improvement in margins.
The most interesting part may still be ahead. With much greater visibility into 2027, I believe the market still underestimates the company's earnings growth potential. That's why I remain bullish, even with an already demanding valuation.
Get 75% Off TipRanks Premium and unlock powerful investing tools to make smarter, more confident investment decisions
First, I think it's important to put AMD's remarkable triple-digit rally this year into context. I see two key metrics that have marked a turning point in the company's investment thesis: Data Center revenue growth and forward revenue growth.
Let's start by breaking down the first metric. Basically, the market has gone from viewing AMD as a central processing unit (CPU) manufacturer trying to gain ground in artificial intelligence (AI) graphics processing units (GPUs) to treating it as a potential second major AI infrastructure platform, behind Nvidia (NVDA).
The acceleration driven by AI demand really began to show up in AMD's results in 2026, something that wasn't nearly as pronounced in 2025. To be more specific, in the third quarter of 2025, AMD generated $4.34 billion in Data Center revenue, up 22% year-over-year. A year later, that revenue reached $8.55 billion, a 97% jump, driven by both EPYC processors, benefiting particularly from the growth of AI agents, and Instinct MI450 GPUs. As a result, Data Center now accounts for 64% of the company's total revenue, compared to less than 50% in the same period last year.
As if that weren't enough, this growth came with a considerable improvement in the segment's profitability. Data Center's operating margin rose from 25% to 34%. So, we're talking about a company whose core business has nearly doubled in size while its margins have expanded by an impressive 9 percentage points.
The second key metric, forward revenue growth, is arguably the most important in explaining the enthusiasm surrounding AMD stock. Especially because it reflects a major shift in visibility for 2027.
Rewinding a bit, in November 2025, AMD gave investors a compound annual revenue growth target of over 35% for the next three to five years. This guidance gave many analysts a basis to adjust their forecasts accordingly. However, during the November 3 earnings call, CEO Lisa Su stated that, based on current visibility, AMD expects revenue to grow by more than 80% in 2027.
These are undoubtedly different forecast periods, so they don't represent a directly comparable revision. Still, the difference in the expected pace of growth is enormous.
Management also indicated that, in 2027, revenue from Data Center AI GPUs is expected to more than double, with the Data Center segment accounting for more than 80% of consolidated revenue. Revenue from server CPUs is also expected to roughly double.
One might ask why this visibility, which has driven such a dramatic re-rating of AMD's market value, didn't exist a year ago. In a way, part of it already did. Yet three important things have changed since then.
A year ago, AMD announced a 6 GW deal with OpenAI, marking the first sign of what was to come in Data Center. The first major change was that demand became less dependent on just a few large customers. Meta (META), Microsoft (MSFT), Oracle (ORCL), and Anthropic (ANT) are already using the first Helios systems. These are essentially AI supercomputers housed within data center racks, and AMD's biggest bet to compete with Nvidia in AI infrastructure.
The second shift was that what had been a promise started turning into revenue. A year ago, the MI450 architecture still needed to prove it could be produced and adopted at scale. Now, AMD has already begun ramping up production. The company expects revenue from Data Center AI GPUs to surpass that of server CPUs for the first time in Q4 2026.
Finally, management is now projecting much stronger growth based on customers' deployment plans. AMD expects approximately $17 billion in Q4 revenue, up 66% year-over-year, ahead of further acceleration projected for 2027.
So where might the next opportunity lie, one that the market hasn't yet fully priced in?
In my view, it's not necessarily in further revenue growth, but in the operating leverage this expansion could bring. After all, if AMD can grow sales without increasing operating expenses at the same pace, its earnings could grow considerably faster than revenue.
The valuation helps put this into perspective. At around $585.30 per share, AMD trades at approximately 31.25x its expected adjusted earnings per share (EPS) of $17.69 for 2027. Yet looking ahead to 2028, when consensus estimates already point to EPS near $26, that multiple drops to just 22.5x. Applying a 25x multiple to those projected 2028 earnings, I arrive at a price target of $650, implying approximately 11% upside.
I don't consider AMD a bargain, though. The biggest risk, in my view, is that the market is already pricing in nearly flawless execution in 2027. That leaves the stock particularly vulnerable if the expected surge in revenue doesn't translate into equally strong earnings growth.
Wall Street's AMD forecast remains very bullish, with a Strong Buy consensus rating. Of the 32 analyst ratings issued over the past three months, 29 are Buy and only three are Hold. The average AMD price target stands at $652.18, implying 11.43% upside from current levels.
In my view, AMD's impressive rally in 2026 is backed by solid fundamentals. The acceleration in Data Center revenue and much greater visibility into 2027 explain much of this re-rating.
I also believe the full potential for earnings growth has yet to be reflected in the current share price, especially considering the operating leverage that AI expansion could bring.
That said, the bull case doesn't need to be stretched far to see AMD reach $650 per share. So, I remain bullish on AMD, although further upside will depend much more on execution than on rising expectations.