Microsoft vs. Salesforce: One Software Stock Remains a Top Pick, the Other Has Something to Prove, Says RBC TipRanks Fri, November 13, 2026 at 3:39 PM EST 5 min read MSFT -0.23% CRM -0.04% MSF 4338 Explore stocks on Coinbase Trading disclosure Trading disclosure The above button links to Coinbase. Yahoo Finance is not a broker-dealer or investment adviser and does not offer securities or cryptocurrencies for sale or facilitate trading. Coinbase pays us for certain activity generated through this link. Prices displayed are informational.
Microsoft (NASDAQ:MSFT) and Salesforce (NYSE:CRM) sell to many of the same corporate customers, and both are betting that AI agents, software that can carry out tasks on its own, will become a major source of revenue.
Today, Microsoft got an uncomfortable reminder of how much those customers rely on it. A global outage that started Thursday afternoon knocked Outlook and parts of Teams, Copilot and other Microsoft 365 services offline for millions of users, and it dragged into Friday after the first fixes didn't hold. Microsoft says it has found no sign of malicious activity.
Microsoft shares are down around 1.5% in premarket trading on Friday. Salesforce has had a tough year of its own, with the stock down about 18% year to date.
Get 75% Off TipRanks Premium and unlock powerful investing tools to make smarter, more confident investment decisions
RBC analyst Rishi Jaluria covers both tech giants and published notes on each this week, ahead of Microsoft's Ignite conference (November 17-20) and Salesforce's fiscal third-quarter report on December 2.
Starting with Microsoft, the analyst expects Ignite to show how far the company has pushed AI into every layer of its business, from data centers and in-house chips to apps and security. However, he doesn't see the event moving the stock much in the short term.
The backdrop is strong. Azure grew 48% in constant currency last quarter, up from 43% the quarter before, and management has guided for 49% to 50% this quarter. Jaluria believes demand still outruns the capacity Microsoft can bring online, which makes that guidance look cautious, though the year-ago comparison is a tough one. He wants updates on capacity and on Maia 300, the custom chip unveiled in October, which Microsoft is designing to be 40% more efficient than leading GPU setups and expects to roll out at multi-gigawatt scale in 2027.
Then there's Copilot. Daily users jumped about 50% from the prior quarter and more than fivefold year over year, while customers with over 50,000 Microsoft 365 seats grew more than 8x. Jaluria thinks investors are overlooking Microsoft's shift toward usage-based pricing, which Cowork and GitHub Copilot already use. Charging for consumption rather than per user could lift the ceiling on what Microsoft earns as agents take on more work, and he expects Ignite to add new agent-building and management tools.
"Stepping back," Jaluria summed up, "MSFT continues to be our top pick, and we believe they are a differentiated AI beneficiary across the full stack. We see Ignite as an opportunity for management to further demonstrate the depth and breadth of AI monetization across the stack."
To this end, Jaluria rates MSFT as Outperform (i.e., Buy) with a $640 price target, a figure pointing to 12-month returns of 22%. (To watch Jaluria's track record, click here)
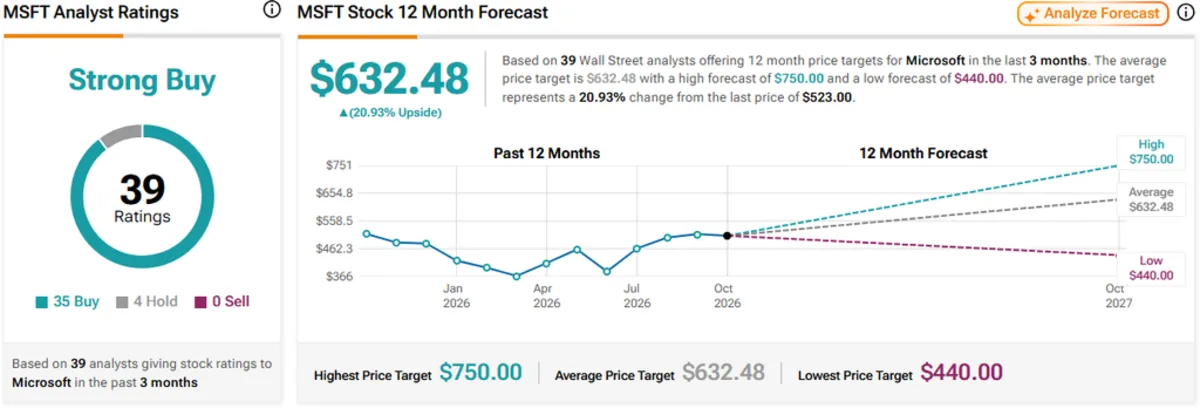
Microsoft gets a Strong Buy consensus rating on the Street, based on 35 Buys and 4 Holds. At $632.48, the average price target implies shares will gain 21% over the coming months. (See MSFT stock forecast)
Salesforce gets a cooler reception. Jaluria thinks software sentiment has yet to recover, and he lists Salesforce among the application companies without clear sight of a near-term growth pickup. That's not because the numbers are weak. Fiscal second-quarter (July quarter) revenue rose 11% YoY, cRPO grew 14% in constant currency, and net new annual order value (AOV) posted its best growth in four years. Agentforce ARR climbed to $1.5 billion, up more than 240%.
What he can't yet see is whether that momentum turns into lasting organic acceleration. Dreamforce left him slightly more upbeat. Its centerpiece, AI Force, opens Salesforce data, workflows and governance to outside AI tools through MCPs, APIs and plugins, on the argument that Salesforce's real value lies in the business context underneath, not the screens people click on. Jaluria isn't sure that holds up if AI model providers move into that territory, and easier outside access could eventually make Salesforce's own apps less essential. Partner checks also suggest pricing is still being worked out.
M&A is the other sticking point. Braze (about $5.66 billion), Cresta, Listen Labs and Rune Technologies push Salesforce's M&A spending over the past 12 months to roughly $27 billion by RBC's estimate. Each deal makes strategic sense, Jaluria says, but together they pile on integration risk just as investors want homegrown growth. He has worried about a return to "empire-building" since the Informatica deal.
The stock trades at about 12x RBC's calendar 2027 free cash flow estimate. "Valuation remains undemanding," says Jaluria, "but the sustained M&A cadence, early-stage AI monetization, and the need to cleanly integrate multiple concurrent acquisitions make it difficult to underwrite material upside in the near-term. In our view, Salesforce needs to demonstrate that this acquisition wave translates into durable organic reacceleration before the stock can re-rate."
To this end, he rates Salesforce as Sector Perform (i.e., Neutral) with a $250 price target. Still, should the figure be met, investors will be pocketing returns of 15% a year from now.
Eight other analysts join Jaluria on the sidelines, but with an additional 30 Buys, the stock claims a Strong Buy consensus view. Over the next year, shares are expected to appreciate by 29%, given the average price target stands at $280.41. (See CRM stock forecast)
Disclaimer: The opinions expressed in this article are solely those of the featured analyst. The content is intended to be used for informational purposes only. It is very important to do your own analysis before making any investment.