‘Everybody needs to prepare’: Market expert warns of December shock that puts Americans at high risk. Act by Dec. 8 Jing Pan Fri, November 13, 2026 at 7:15 AM EST 10 min read ^GSPC -0.35% GC=F +0.23% Moneywise and Yahoo Finance LLC may earn commission or revenue through links in the content below.
The Dow was up about 800 points. The S&P 500 was up 1.8%. On Fox Business, host Stuart Varney told viewers to take a look at their screens. "It's Monday morning. You like this stuff," he said (1).
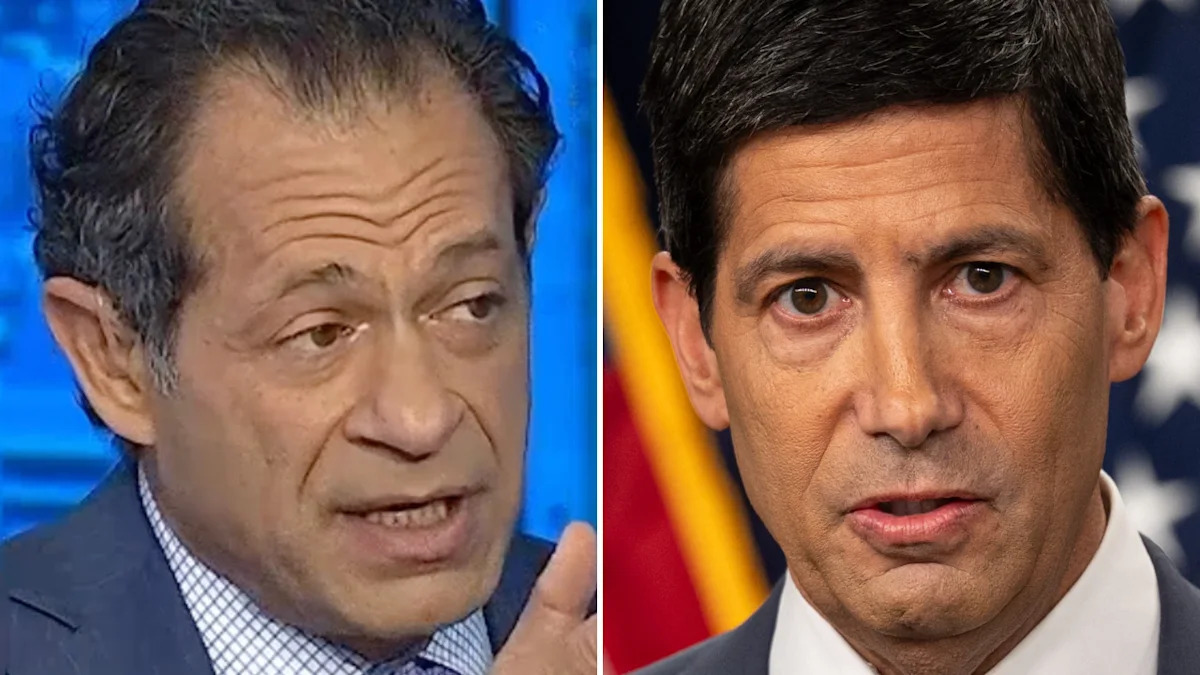
But his guest, market expert Jeff Sica, was looking past the morning's rally. He had his eye on a decision that was still weeks away.
Jeff Bezos backs a platform that lets anyone invest in rental homes for as little as $100 — 5 ways to build wealth like a landlord without actually being one
A single line on your car insurance policy could be inflating your premium by up to 30% — here's what to change
Gold has overtaken U.S. Treasuries as central banks' top reserve asset. Get Goldco's 2026 Precious Metals IRA Playbook for free
Varney brought up the inflation report due the next morning and suggested it might tempt the Fed to raise interest rates. Sica, CEO of Circle Squared Alternative Investments, cut straight to it.
"Stuart, not only are they tempted; they will raise interest rates," Sica said. "They're going to raise interest rates in December."
Sica pointed to Federal Reserve Chair Kevin Warsh's comments at Jackson Hole that Fed policy was not overly restrictive. Referring to the Fed's inflation target, Sica said, "He wants that 2%. We are not there yet. He is not going to back down. He is going to raise interest rates."
The Fed held its benchmark rate at 3.75% to 4% in October.
Its next meeting begins Dec. 8, with a decision due Dec. 9. And the inflation report (2) that landed after the interview gave officials more to think about. Consumer prices rose 0.4% in October from the previous month, while core inflation, which excludes food and energy, rose 0.3% for a third straight month.
Hours before the numbers came out, Fed Governor Christopher Waller said (3) he was leaning toward a 25-basis-point increase in December.
He also said a 50-basis-point hike should be considered if monthly core inflation came in at 0.3% or higher. It came in right at that threshold. The committee still has to vote, but one member has already put a bigger move on the table.
While Sica expects the Fed to raise rates, he doubts a hike will do much about the prices that prompted it in the first place.
"I think it's going to be completely ineffective. I think it's going to hurt the economy," Sica said. "I think it's especially going to hurt all this debt and this wall of refinances."
He called the approach "an ill-conceived agenda considering where I think inflation is coming from."
For everyday Americans, that could mean getting squeezed on two fronts.
Higher rates could make it more expensive to carry a credit card balance or refinance a mortgage. At the same time, stubborn inflation could keep pushing up everyday costs, from groceries and gas to rent and utilities. And if you're retired and living off your savings, covering those same expenses could mean taking more out of your nest egg.
"But it's going to happen," Sica warned. "So everybody needs to prepare themselves."
If you share those concerns, here are a few steps to help protect yourself from the double whammy.
When it comes to preserving wealth and fighting inflation, few assets have stood the test of time like gold.
Its appeal is simple: Unlike fiat currencies, the yellow metal can't be printed at will by central banks. This inherently limited supply can help it store value.
Gold is also considered the ultimate safe haven. It's not tied to any one country, currency or economy and in times of economic turmoil or geopolitical uncertainty, investors often flock to it — driving prices higher.
Ray Dalio, founder of the world's largest hedge fund, Bridgewater Associates, has repeatedly highlighted gold's role in a resilient portfolio.
"People don't have, typically, an adequate amount of gold in their portfolio," Dalio told CNBC last year. "When bad times come, gold is a very effective diversifier."
Over the past five years, as inflation continued to chip away at the purchasing power of the dollar, gold has climbed about 115%.
Other prominent voices see further potential. JPMorgan CEO Jamie Dimon has said that in this environment, gold can "easily" rise to $10,000 an ounce.
One way to invest in gold that also provides significant tax advantages is to open a gold IRA with the help of American Hartford Gold.
Gold IRAs allow investors to hold physical gold or gold-related assets within a retirement account — combining the tax advantages of an IRA with the protective benefits of investing in gold, making it an option for those looking to potentially hedge their retirement funds against economic uncertainties.
Even better, you can often roll over existing 401(k) or IRA accounts into a gold IRA without tax-related penalties. American Hartford Gold also helps keep startup costs down with free account setup, free insured shipping and up to five years of free storage. To learn more, get your free information guide on investing in precious metals.
If you change your mind, you can cancel within seven days for a full refund on eligible assets. With their price protection guarantee, if prices drop within seven days of your purchase, your order is repriced to reflect the lower price.
Qualifying purchases can also receive up to $25,000 in free silver. Just remember — gold is often best used as one part of an otherwise well-diversified portfolio.
Subscribe to Moneywise: Get Warren Buffett's best investing lessons in 1 free guide
Sica warned that a December rate hike could make things especially tough for borrowers facing what he called a "wall of refinances."
He has a point. America has approximately 3.1 million active adjustable-rate mortgages, according to Intercontinental Exchange (4). These loans can change rates after an initial fixed period, potentially leaving homeowners with larger payments. Not all face an immediate adjustment, but knowing your reset date matters.
If you have an adjustable-rate mortgage (ARM), start with the date your current rate stops being fixed. Check when your rate next adjusts and when the first payment at the new rate would be due. Ask your mortgage servicer for two estimates: your expected new payment and the highest payment permitted at that adjustment.
An ARM's rate generally follows a benchmark index plus a lender-set margin, subject to caps on how much it can change. Your loan's terms determine when — and how sharply — your payment can move.
Put the estimates into your household budget. If the numbers don't work, exploring refinancing early gives you time to compare alternatives. Weigh the new rate, closing costs and repayment term; a lower monthly payment isn't always a cheaper loan overall.
Whether you're considering refinancing or need a mortgage for a purchase, you don't have to accept the first offer.
Freddie Mac recommends shopping around and obtaining quotes from three to five lenders to secure the best possible mortgage rate. Even a small rate reduction can translate into significant savings over the life of a loan.
To make this process easier, places like the Mortgage Research Center (MRC) can help you quickly compare rates and estimated monthly payments from multiple vetted lenders. By entering basic details — such as your zip code, property type, price range and annual income — you can view mortgage offers tailored to your needs and shop with confidence.
And if replacing your mortgage doesn't make financial sense, there's another housing expense you can shop around for: homeowners insurance.
By using a comparison platform like Insurify, you can instantly view quotes from top-rated providers to ensure you aren't paying a hidden "loyalty tax" to your current insurer.
Just answer a few basic questions and Insurify will show you the most affordable deals in as little as three minutes.
Not only is the process 100% free, but you could also save up to 15% by bundling your car and home insurance.
Homeowners aren't the only ones facing a potential squeeze. A December rate hike could show up on your credit card bill, too. If your card has a variable rate (most credit cards in America do), it can climb when its benchmark rises, making any balance you carry more expensive.
Americans held a record $1.29 trillion in credit card balances in the third quarter, according to the New York Fed (5). For those carrying balances month to month, another rate increase could make an already expensive problem harder to escape.
Start by reviewing your latest credit card statement. Check your interest rate, outstanding balance and the repayment estimate showing how long it would take to pay off your debt if you make only the minimum payments.
To get rid of your debt faster, one option is consolidating all your debts into a personal loan through Credible. Instead of juggling multiple monthly payments, you'll have one predictable payment to manage each month.
Through Credible's online marketplace, finding the right loan becomes much simpler. Credible lets you comparison-shop for the lowest interest rates with just a few clicks.
In less than three minutes, you'll see all the lenders willing to help pay off your credit cards or other debts with a single personal loan.
If you owe a substantial amount, you may also want to see if you qualify for a debt relief program to help clear a significant portion of your debt.
With Freedom Debt Relief, you can speak with a certified debt relief consultant for free, who can show you how much you can save by partnering with them.
If you're eligible, they can negotiate settlements with your creditors until all of your enrolled debt is resolved.
Higher rates can squeeze borrowers, but they can also give savers an opportunity to earn more on their cash.
The catch? Your bank may be quick to charge more on your debt without being equally quick to reward your savings.
Check the annual percentage yield on your emergency fund and other cash reserves. If your money is earning next to nothing, shopping around could help you put the higher-rate environment to work in your favor.
For instance, a high-yield account like a Wealthfront Cash Account can be a great place to grow your uninvested cash, offering both competitive interest rates and easy access to your money when you need it.
A Wealthfront Cash Account currently offers a base rate APY of 3.55% through program banks. With a new client boost and direct deposit incentive, referred clients can earn up to a 4.55% APY.
That's 9 times the national deposit savings rate, according to the FDIC's October report (6).
With no minimum balances or account fees, as well as 24/7 withdrawals and free domestic wire transfers, your funds remain accessible at all times. Plus, you get access to up to $8 million FDIC insurance through program banks.
The tax breaks in Trump's 'big beautiful bill' expire after 2028. Here are 4 moves to make before the window closes
Vanguard reveals what's coming for U.S. stocks — and it could be bad news for this group of investors
Robert Kiyosaki issued grim warning for baby boomers. Many could be 'wiped out' and homeless 'all over' the country. How to protect yourself now
Dave Ramsey says this 1 indulgent purchase stops Americans from becoming wealthy. Here's what he recommends instead
We rely only on vetted sources and credible third-party reporting. For details, see our ethics and guidelines.
YouTube (1); Bureau of Labor Statistics (2); U.S. Federal Reserve (3); CNBC (4), (5); Federal Deposit Insurance Corporation (6)
This article provides information only and should not be construed as advice. It is provided without warranty of any kind.