Is Nvidia a buy after its CEO-resignation pullback? TheStreet Staff, CutterStudios.AI, Jeremy Salvucci Thu, November 12, 2026 at 8:02 PM EST 11 min read NVDA -3.22% Trade NVIDIA on Coinbase Trading disclosure Trading disclosure The above button links to Coinbase. Yahoo Finance is not a broker-dealer or investment adviser and does not offer securities or cryptocurrencies for sale or facilitate trading. Coinbase pays us for certain activity generated through this link. Prices displayed are informational.
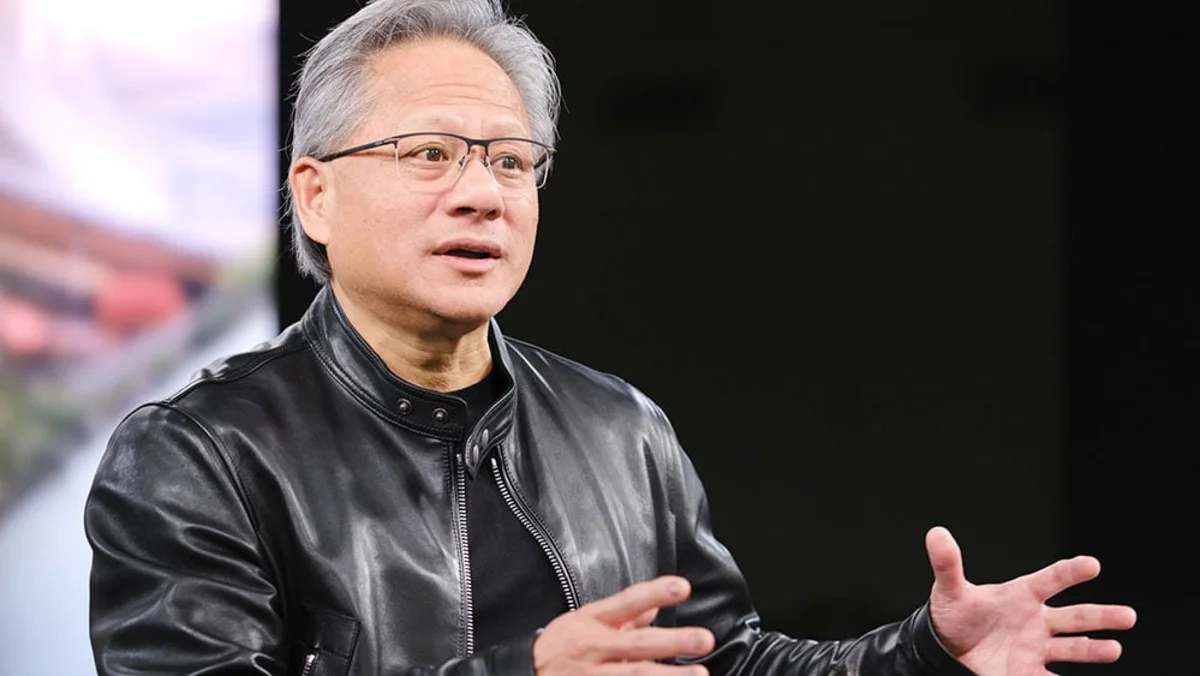
Nvidia stock fell over 4% on November 12 after co-founder and former CEO Jensen Huang, who has long been the face of the company, stepped down after news broke of his affair with an alleged Chinese spy.
A sharp stock decline can make an investment look cheaper without making it better. Robert Shine, chief investment officer of Blanke Schein Wealth Management, argues that investors should assess the business behind a pullback before they buy it, using four checks: the earnings trend, management's forward guidance, the company's place in its sector and the economic cycle, and price behavior on a chart.
That framework is especially relevant when high-profile stocks are moving quickly. Shine still sees Nvidia as an important AI build-out story despite its leadership upheaval, but his broader message is more useful than any single stock call: Keep a shopping list before a sell-off arrives, then use evidence to decide whether a lower price represents a chance to add or a reason to stay away.
Shine spoke with TheStreet's Caroline Woods to explain how he applies that discipline, from examining a company's outlook to maintaining sufficient cash and bonds to navigate a volatile market.
Note: The market musings expressed herein are those of the interviewed guest and should not be treated as professional investment advice. Readers should consult a certified financial planner (CFP) for individualized advice based on their available capital, goals, risk tolerance, and time horizon.
The first question in a pullback is whether the company's investment case has changed. A stock can fall because the market is worried about a temporary event, but it can also fall because expected sales, profits, competition, regulation, or demand have deteriorated. Treating both situations as identical is how investors turn a shopping list into a list of problems they have chosen to own.
Nvidia illustrates the distinction in Shine's view. He described the company's leadership news as a market-clearing event, meaning a sell-off that resets investor expectations and removes some speculative enthusiasm. He still sees demand for AI infrastructure as central to the longer-term case, while also acknowledging that earnings and management's outlook would supply information investors did not yet have.
If you're interested in a roller coaster ride, you buy it here, right? Because traditionally and historically on Wall Street, when you have that negative headline as you're seeing today, moving forward, again the market-clearing event as I referred to, moving forward that has been the time to buy.
Shine's comment is deliberately conditional. A negative headline can produce opportunity, but it does not eliminate uncertainty. For an investor considering Nvidia, the relevant evidence includes the company's leadership succession planning, the outlook for chip demand, and whether an investigation or a national-security issue reveals risks more serious than the initial headlines suggested.
That is a useful distinction for any stock. A falling share price is an observation. A sound purchase decision requires a view on the business, the price paid for the business, and the risks that could change the original thesis.
Shine's first two checks are the trend in earnings and forward guidance. Earnings show what a business has already delivered. Guidance shows whether company executives expect the drivers of those results, such as demand, costs, product launches, or margins, to improve or weaken.
Neither measure offers certainty. Management can revise an outlook, and a single strong quarter does not set a stock's future in stone. Still, a pullback in a company that continues to grow earnings and maintains a constructive outlook offers a different setup from a pullback accompanied by lowered expectations.
Shine used Microsoft and Amazon as examples of companies whose AI he believes is showing tangible business results. His Microsoft case rests on the company's ability, in his view, to remain profitable while investing in AI. His Amazon case centers on AWS, Amazon Web Services, which he described as evidence that cloud computing can provide operating leverage. Operating leverage means that revenue can rise faster than certain operating costs, allowing profitability to expand as a business grows.
The practical lesson is to ask a plain question before buying a dip in an AI-related company: Is spending producing a clearer path to revenue, profit, or free cash flow? Investors do not need to predict every new technology to look for proof that investment is becoming a productive business.
Shine's third check concerns the sector and the business cycle. A cyclical business is one whose sales and profits tend to rise and fall with economic conditions. A consumer discretionary company, for example, sells goods or services that households can often postpone when budgets tighten. That makes its outlook more sensitive to inflation, employment, borrowing costs, and consumer confidence than the outlook for a company selling necessities.
This is why a sector-level screen matters. A company can execute well while its industry faces difficult demand, or an average company can receive a lift from a recovering sector. Shine pointed to consumer discretionary stocks that had been beaten down and were rebounding, but he also described the category as crowded. The same broad sector can contain both a turnaround candidate and a business losing ground to competitors.
His consumer examples underline the need to separate a recognizable brand from an attractive investment. Shine called Estée Lauder a turnaround story based on international growth and brand traction in China. He remained cautious on Lululemon because he sees intense competition in athletic apparel. He considered Nike potentially attractive at depressed levels if its operational story improves, while saying he saw more compelling near-term opportunities elsewhere.
A reader can apply the same filter without relying on personal shopping habits. Look at whether a company's latest results support its strategy, whether a competitor is taking share, and whether the industry is growing or contracting. Anecdotes can prompt a question. Financial results and management commentary should carry more weight in the answer.
The fourth element is technical analysis, or the study of a stock's price and trading pattern. Shine said he also watches whether a stock is technically turning around from a chart perspective. In his process, price behavior is an additional test after examining earnings, guidance, and the sector backdrop.
That ordering matters. A stock bouncing after a steep decline may show that selling pressure has eased, but a chart cannot by itself establish that a company's fundamentals have improved. Conversely, good fundamentals do not prevent a stock from falling further when investors are reducing risk across the market.
For a long-term, buy-and-hold investor, technical analysis can be a way to avoid deploying all available cash in one purchase during a rapid sell-off. It can also help identify whether a stock's decline is stabilizing. It should not replace a review of valuation, business quality, and the reason the stock sold off.
Investors with shorter time horizons face a different task. They may use price behavior to manage an entry and an exit more closely, but they should define the maximum loss they are prepared to accept before exiting the position. That trading decision is separate from Shine's longer-term stock-selection process.
Shine's advice to maintain a shopping list is an antidote to making decisions in the middle of a stressful market day. The list can include companies an investor understands, the reasons they are attractive, a valuation range the investor considers reasonable, and the specific developments that would invalidate the case.
A written list also forces a useful comparison. If two companies have fallen by similar amounts, the better choice may be the one with a sturdier balance sheet, more reliable cash generation, or clearer management outlook. The largest percentage decline is not necessarily the best opportunity.
Shine's preference for Broadcom over AMD in the immediate aftermath of NVIDIA's disruption follows that logic. He described Broadcom as holding the stronger current position because, in his view, it offers more certainty while allowing investors to avoid Nvidia-specific headlines. That is a preference tied to a particular moment, not a claim that one company will always outperform the other.
The approach also helps investors avoid forcing themselves to buy every apparent bargain. Shine said he would wait for a better entry point in Eli Lilly despite his favorable long-term view of the GLP-1 market. An attractive business can still have a price that calls for patience.
A shopping list is only useful when an investor has money available to act. Shine said Blanke Schein Wealth Management had been rebalancing client portfolios by selling into strength in some stocks and sectors, then reallocating a portion of assets to fixed income. Fixed income refers to bonds and similar investments that generally pay scheduled interest.
When we got up to over 5% on the 10 year, or even the 530 as I mentioned earlier, treasuries are sexy again, right? Bonds are sexy again. We haven't been able to say that for a good long time.
Shine's point is that bond yields can change the role bonds play in a portfolio. When yields are higher, investors may receive more income while holding an asset that can reduce the portfolio's dependence on stock prices.
For illustration, Shine said his firm typically holds 5% to 10% in cash equivalents, about 25% in fixed income, and the remainder in equities for the client portfolios he described. Cash equivalents are highly liquid, lower-risk holdings, such as money-market investments, that can generally be converted to cash quickly. He said allocations vary with a client's risk tolerance and age, so the figures are his firm's approach rather than a universal prescription.
He also said the firm favored the middle of the yield curve, including bonds with maturities in the seven- to 10-year range. The yield curve compares interest rates across bonds with different maturities. Duration measures how sensitive a bond's price may be to changes in interest rates; a longer-duration bond generally has greater sensitivity.
Shine's framework does not promise a perfect entry point, and it does not remove the possibility that a stock continues to fall after purchase. It gives long-term, buy-and-hold investors a sequence for making a more informed decision: Identify why the stock declined, review earnings and management's outlook, examine the sector and economic backdrop, use price behavior as a secondary confirmation, and decide how much cash to commit.
The decision should change when the evidence changes. A temporary setback paired with intact earnings power may justify incremental buying for an investor who can tolerate volatility. Weakening guidance, worsening competition, or a newly disclosed risk may justify waiting, reducing exposure, or avoiding the stock entirely.
For investors who already own stocks, portfolio construction remains part of the answer. Cash equivalents and fixed income can provide the flexibility to act during a drawdown without selling long-term holdings at an unfavorable moment. The appropriate mix depends on the investor's time horizon, income needs, risk tolerance, and existing holdings.
Shine's stock preferences, including Nvidia, Broadcom, Microsoft, Amazon, Visa, Estée Lauder, and Eli Lilly, reflect his firm's views at the time of the segment. Investors should assess whether any individual stock fits their own objectives and diversification needs rather than treating a televised stock call as personalized investment advice.
This article is based on TheStreet's interview with Robert Shine on TheStreet. Watch the full interview here.
Shine's pullback checklist includes earnings trends, management forward guidance, sector cyclicality, the business cycle, and chart-based technical analysis. (7:30–8:13)
Shine describes NVIDIA's sell-off as a market-clearing event and says a negative headline has historically been a time to buy, while characterizing the position as volatile. (2:56–3:04)
Shine says Microsoft can preserve cash flow while investing in AI and cites AWS growth as part of Amazon's case. (8:56–10:00)
Shine says Blanke Schein Wealth Management typically holds 5% to 10% in cash equivalents, about 25% in fixed income, and the balance in equities for the client portfolios he describes. (22:43–23:25)
Shine says a 50-basis-point Federal Reserve increase could delay his S&P 500 target and pause a Santa Claus rally without ending the bull market. (18:55–20:15)
This story was originally published by TheStreet on Nov 12, 2026, where it first appeared in the Investing section. Add TheStreet as a Preferred Source by clicking here.
Some or all of this content may have been generated by AI. While we strive for accuracy, AI can occasionally produce incorrect information. If you buy something via one of our links, we may earn a commission.