Nvidia (NVDA) Stock Gets Fair Value Trim As Analyst Views Turn More Divided Sasha Jovanovic Thu, November 12, 2026 at 7:17 PM EST 5 min read NVDA -3.67% GS -1.29% Explore stocks on Coinbase Trading disclosure Trading disclosure The above button links to Coinbase. Yahoo Finance is not a broker-dealer or investment adviser and does not offer securities or cryptocurrencies for sale or facilitate trading. Coinbase pays us for certain activity generated through this link. Prices displayed are informational.
Nvidia's fair value estimate has been trimmed from $328.72 to $319.99, reflecting a slightly more cautious stance on the stock. Recent analyst commentary has become more divided, with bulls pointing to AI demand and ecosystem breadth, while bears highlight governance questions, financing exposure and long term visibility, which helps explain why price targets are being adjusted rather than reset. As you read on, you will see how these shifting views shape the evolving Nvidia story and what it means for tracking the stock from here.
Analyst Price Targets don't always capture the full story. Head over to our Company Report to find new ways to value NVIDIA.
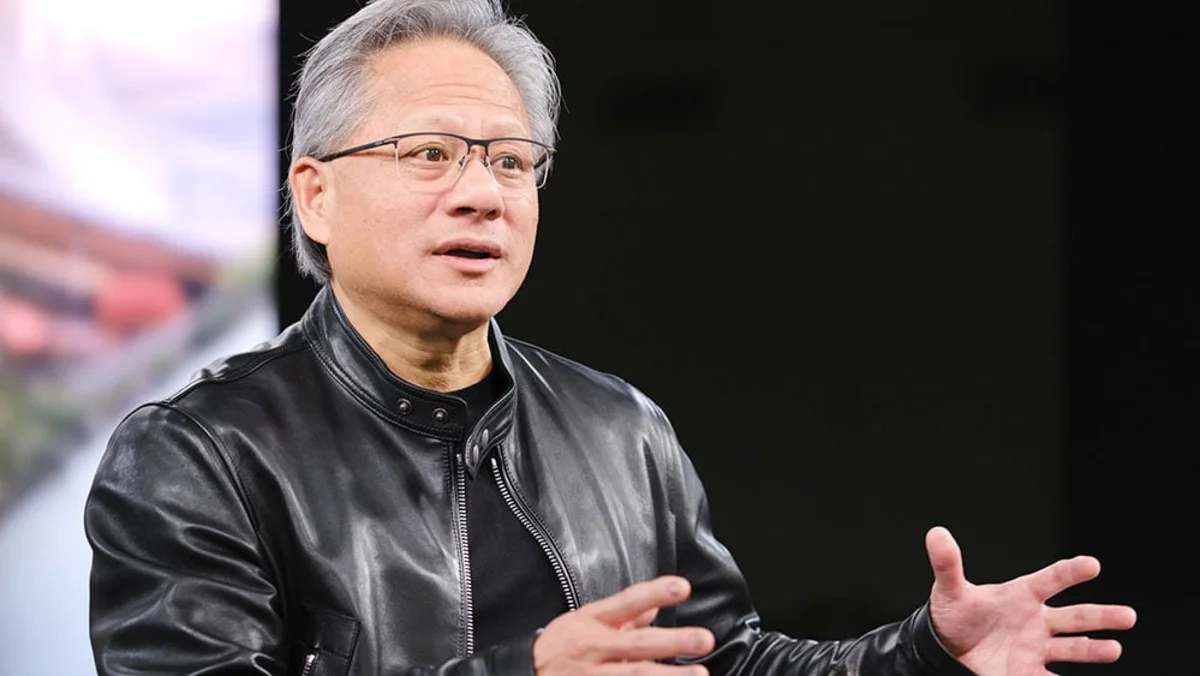
Recent research on Nvidia has turned sharply more cautious after the departure of CEO Jensen Huang, yet many firms still see meaningful strengths in the business. For you as an investor, the key point is that Wall Street is now separating Nvidia's core AI position from questions about leadership, governance and financing exposure.
Several firms, including Goldman Sachs, Citi, BofA, BMO Capital and JPMorgan, continue to rate Nvidia positively even after cutting price targets. They point to established AI product roadmaps and long-dated backlogs that underpin their valuation work.
Yorkville Ives and BMO Capital both trimmed targets, to US$225 and US$240 respectively. They still argue that Nvidia's AI chip position and what they view as attractive valuation support constructive long term growth prospects.
Stifel and BofA lowered targets to US$205 and US$280. They emphasize that current concerns are more about the multiple and governance risk than near term fundamentals, which they still frame as supported by demand and capacity plans.
Multiple firms have shifted to more neutral stances, including Bernstein, Evercore ISI, Baird, StoneX, William Blair, Oppenheimer, Truist and Craig Hallum. They often cite key person risk after Huang, succession uncertainty and governance questions.
Evercore ISI cut its target to US$186 from US$465 and Citi reduced an earlier target to US$285 before the resignation headlines. Both flag increased regulatory scrutiny and export control risk, particularly around sales into China and broader APAC.
Truist and Aletheia highlight concerns about culture, legal and policy exposure, and Nvidia's growing financing commitments to neocloud partners. They see this as adding execution risk and providing less visibility on longer term growth.
Do your thoughts align with the Bull or Bear Analysts? Perhaps you think there's more to the story. Head to the Simply Wall St Community to discover more perspectives!
We've flagged 2 risks for NVIDIA. See which could impact your investment.
Nvidia is in focus after a Democratic midterm sweep in the US, with AI chip regulation and potential limits on new AI data center builds raising questions about operating costs and environmental compliance.
CEO Jensen Huang is under internal board investigation and facing class action litigation and political scrutiny following an admitted affair with a woman US intelligence agencies believe is a Chinese spy, with governance and succession planning under review.
US regulators and Congress are examining Nvidia's China exposure, including alleged AI chip smuggling via intermediaries, tighter proposed export controls and new tracking measures across Southeast Asia and data center clients.
The US Department of Justice is reviewing Nvidia's planned US$12.9b acquisition of Hugging Face and earlier Groq-related deals, which adds scrutiny to the company's broader AI M&A and investment activity.
Fair value trimmed from US$328.72 to US$319.99, based on modestly softer assumptions for Nvidia.
Revenue growth assumption eased from 48.69% to 48.27% for Nvidia's long term revenue base.
Net profit margin expectation edged higher from 54.28% to 54.74% on Nvidia's income.
Future P/E multiple reduced from 19.69x to 19.20x on Nvidia's expected earnings.
Discount rate increased from 11.25% to 11.32%, implying a marginally higher required return on Nvidia's future cash flows.
Narratives link Nvidia's business story to a financial forecast and fair value that update as new information comes through. They help you see how changing news, forecasts and risks connect into one clear thesis.
Head over to the Simply Wall St Community and follow the Narrative on NVIDIA to stay up to date on:
How Nvidia's shift to full stack AI factory platforms and rising revenue per gigawatt shapes its data center opportunity.
The role of broader ACIE demand, sovereign AI projects and physical AI workloads such as autonomous systems in supporting Nvidia's revenue mix.
Key risks around US China export controls, customer in house accelerator programs, and margin pressure from higher component costs.
This article is general in nature and was produced with the assistance of AI automation, based on data and analysis from Simply Wall St. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Companies discussed in this article include NVDA.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com