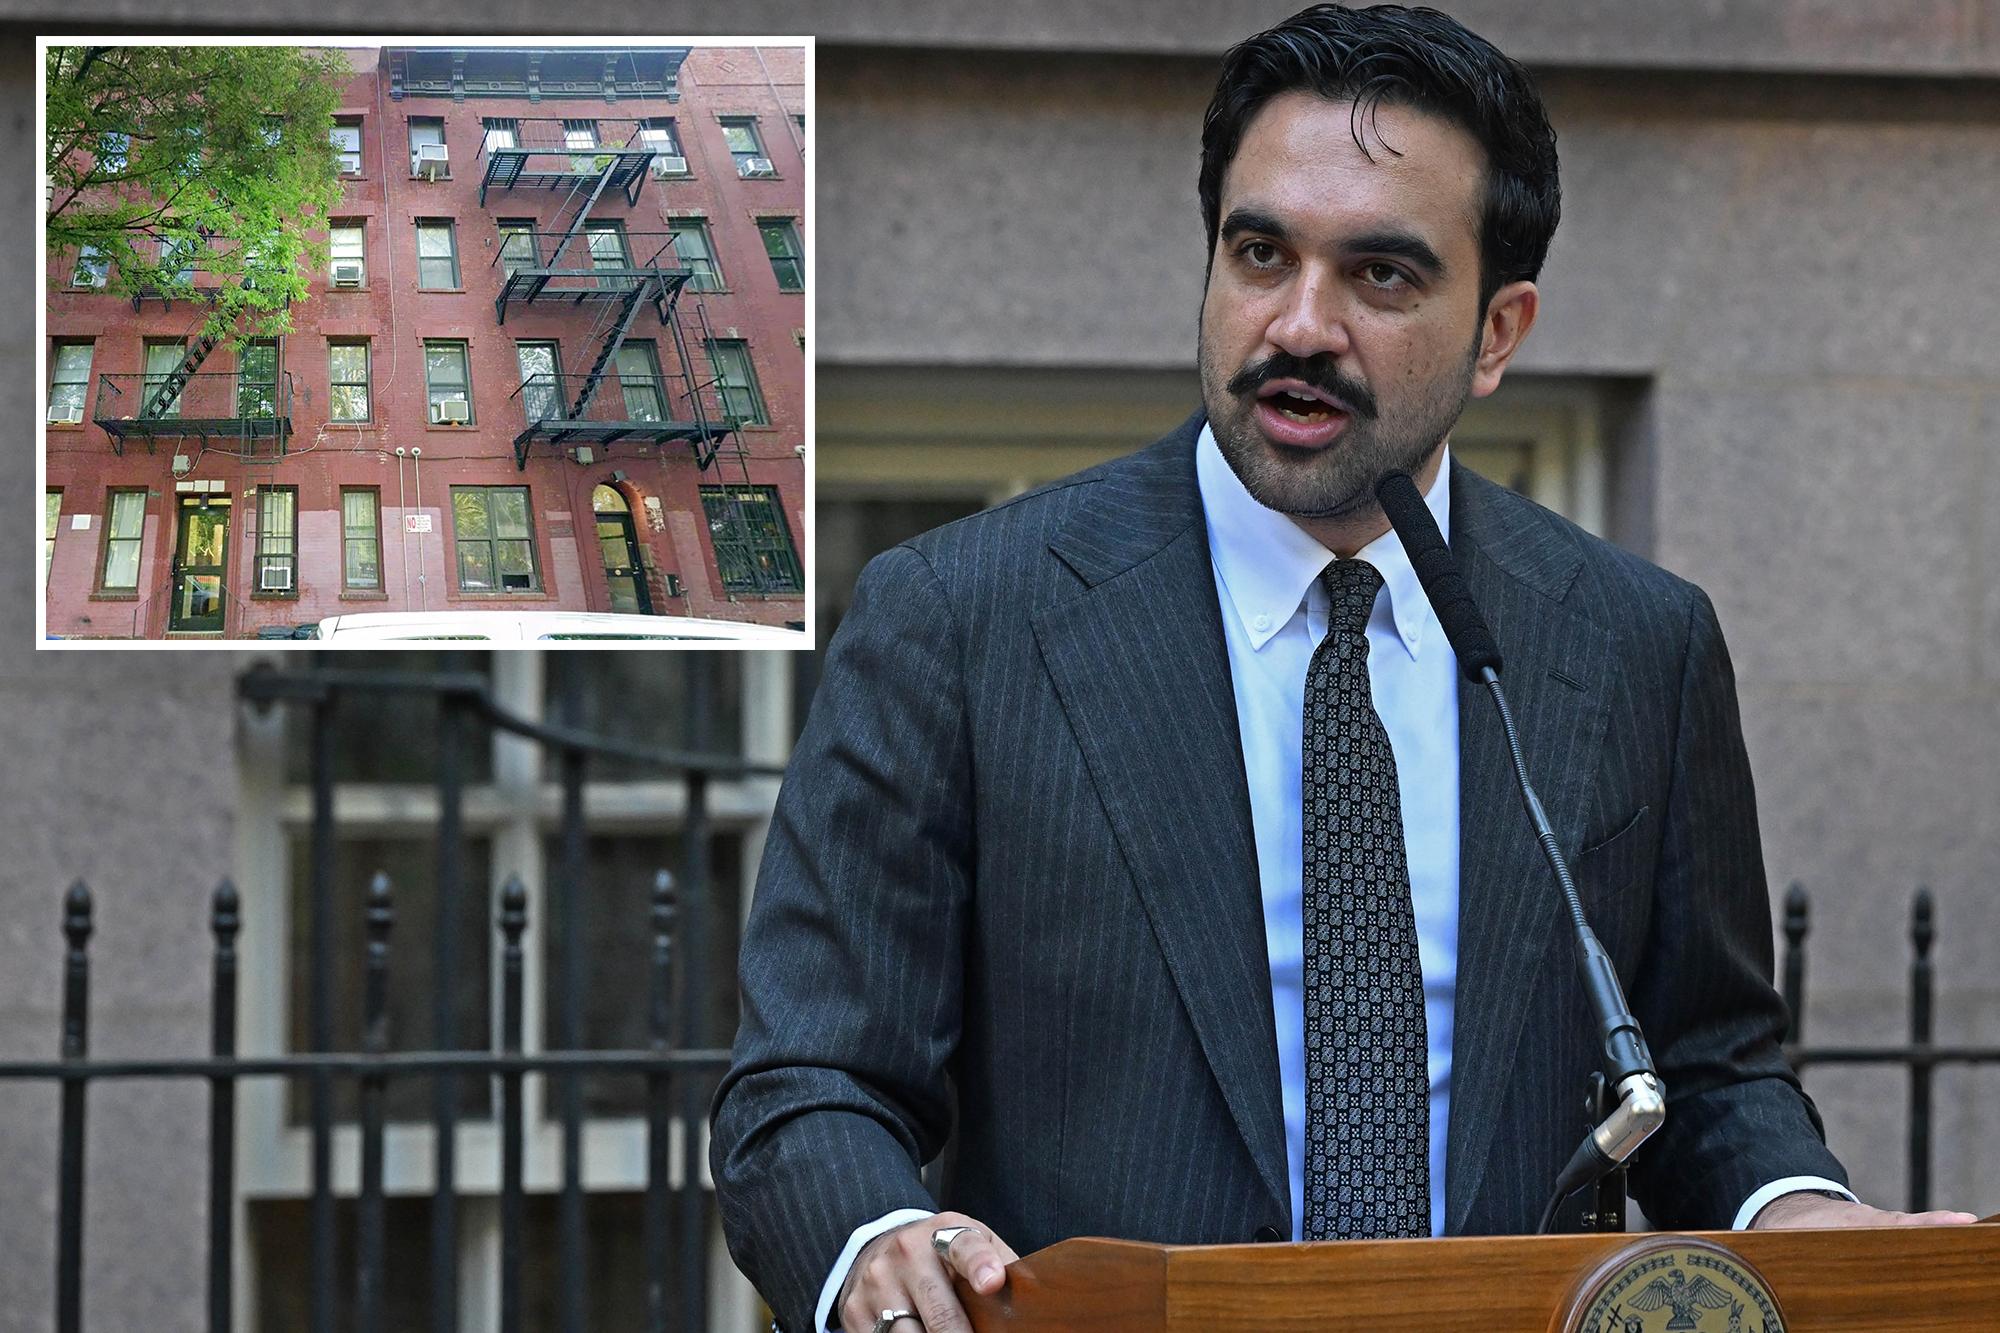
Make New York Post a Preferred Source Mayor Zohran Mamdani’s effort to steer hundreds of deteriorating Manhattan apartments into nonprofit ownership has hit a wall — after creditors rejected a $110 million offer from a city-backed developer and pushed the buildings into foreclosure auctions.
And despite City Hall insisting the fight isn’t over, the administration has yet to publicly explain how it plans to salvage the deal.
At Tuesday’s auction, 14 of 15 East Harlem apartment buildings failed to attract outside buyers, with most reverting to plaintiff US Bank National Association for nominal bids of $500 apiece. One went for $1,000.
The only building to draw an outside bidder, at 417 E. 114th St., sold for $826,000 — just $1,000 above the minimum bid and far below its original $1.9 million loan.
The properties are part of a troubled 38-building portfolio containing roughly 850 apartments, most of them rent-stabilized, that was previously owned by Emerald Equity Group.
The buildings had accumulated more than 2,300 housing code violations when the city became involved earlier this year, raising concerns about deteriorating living conditions and the future of desperately needed affordable housing.
Mamdani’s administration had backed affordable housing developer Spatial Equity in its attempt to purchase the portfolio, with tenant advocates hoping the properties would eventually be transferred to the nonprofit East Harlem El Barrio Community Land Trust.
The Post previously reported that Spatial Equity was seeking to evict eight tenants from a separate Brooklyn housing complex, even as the administration backed its bid for the East Harlem properties.
The developer initially offered $68 million before raising its bid to $110 million last month. Creditors rejected both offers, and the properties proceeded to foreclosure.
The setback came on the very day Mamdani signed the Community Opportunity to Purchase Act, or COPA, a law intended to give qualifying nonprofit housing organizations a better shot at buying certain troubled apartment buildings before private investors.
But the new law won’t take effect until November 2027 — and even then, it won’t apply to judicially supervised foreclosure auctions like those involving the Emerald properties.
That leaves the administration’s immediate path forward unclear.
Deputy Mayor Leila Bozorg said Tuesday that the city was not giving up on the portfolio, but officials have not publicly detailed whether they intend to pursue a revised offer, seek another buyer or explore a different approach.
The Post reached out to City Hall seeking clarification on whether the administration is still actively pursuing the properties and how it plans to overcome creditors’ rejection of the $110 million bid, but had not received a response as of Thursday afternoon.
The setback follows Mamdani’s failed attempt to influence the bankruptcy sale of roughly 5,200 Pinnacle Group apartments earlier this year.
Emerald CEO Isaac Kassirer bought the original 47-building portfolio for more than $350 million in 2016, betting on renovations and higher rents. He had removed roughly 20% of the units from rent stabilization before a 2019 law largely eliminated that strategy.
Mack Real Estate Group took control in 2023 but subsequently defaulted.
Between 2020 and 2024, operating expenses for rent-stabilized apartments climbed 27%, while rents rose just 11%, according to nonprofit lender Community Preservation Corp.
Some NYC landlords have been forced to sell buildings at discounts of up to 90% amid mounting financial pressures.
Kenny Burgos, CEO of the New York Apartment Association, criticized Mamdani’s COPA signing in a statement Tuesday as the foreclosure auctions unfolded.
“The problem isn’t who can buy these buildings,” Burgos said, citing rising expenses, the rent freeze and vacant rent-stabilized apartments.
Another 13 properties are scheduled for auction Nov. 17, with dates for the remaining buildings yet to be set.