Daniel Miller, The Motley Fool Thu, November 12, 2026 at 12:05 PM EST 4 min read RIVN -3.99% NVDA -5.61% Explore stocks on Coinbase Trading disclosure Trading disclosure The above button links to Coinbase. Yahoo Finance is not a broker-dealer or investment adviser and does not offer securities or cryptocurrencies for sale or facilitate trading. Coinbase pays us for certain activity generated through this link. Prices displayed are informational.
Rivian Automotive (NASDAQ:RIVN) shareholders probably wouldn't mind a little encouragement from Wall Street. But a buy rating alone doesn't pay the bills, fix a production bottleneck, or convince somebody to buy an electric vehicle (EV).
What makes this upgrade interesting is the reasoning behind it. UBS sees a disconnect between Rivian's beaten-down stock and the opportunity taking shape around its highly anticipated R2. For investors, the question is whether that disconnect represents an opportunity – or whether the market has good reasons to remain skeptical.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
On Nov. 2, UBS analyst Joseph Spak upgraded Rivian from neutral to buy while keeping his $17 price target unchanged. Analysts at UBS viewed the stock's roughly 19% decline over the preceding month as a buying opportunity ahead of an expected improvement in R2 production and automotive gross margins.
It's fair to say that Rivian has worked through two quarters of upfront launch costs, which have weighed on margins, and the EV maker added a second shift near the end of the third quarter while targeting a third production shift sometime next year.
Rewinding a moment, UBS' unchanged target is worth thinking about. UBS didn't need a bigger estimate of Rivian's value to become more enthusiastic. Essentially, a lower share price made the existing opportunity more appealing, suggesting Rivian is undervalued in the analysts' view.
Or to use a corny auto analogy: Think of a vehicle you've been eyeing finally getting a price cut. The discount matters – but you still need to look under the hood before celebrating a bargain.
Rivian delivered 19,248 vehicles in the third quarter, up 46% year over year. R2 became its best-selling vehicle by volume, outselling both R1 and its electric delivery van. Those are actual customer deliveries, giving investors something firmer than launch excitement to consider.
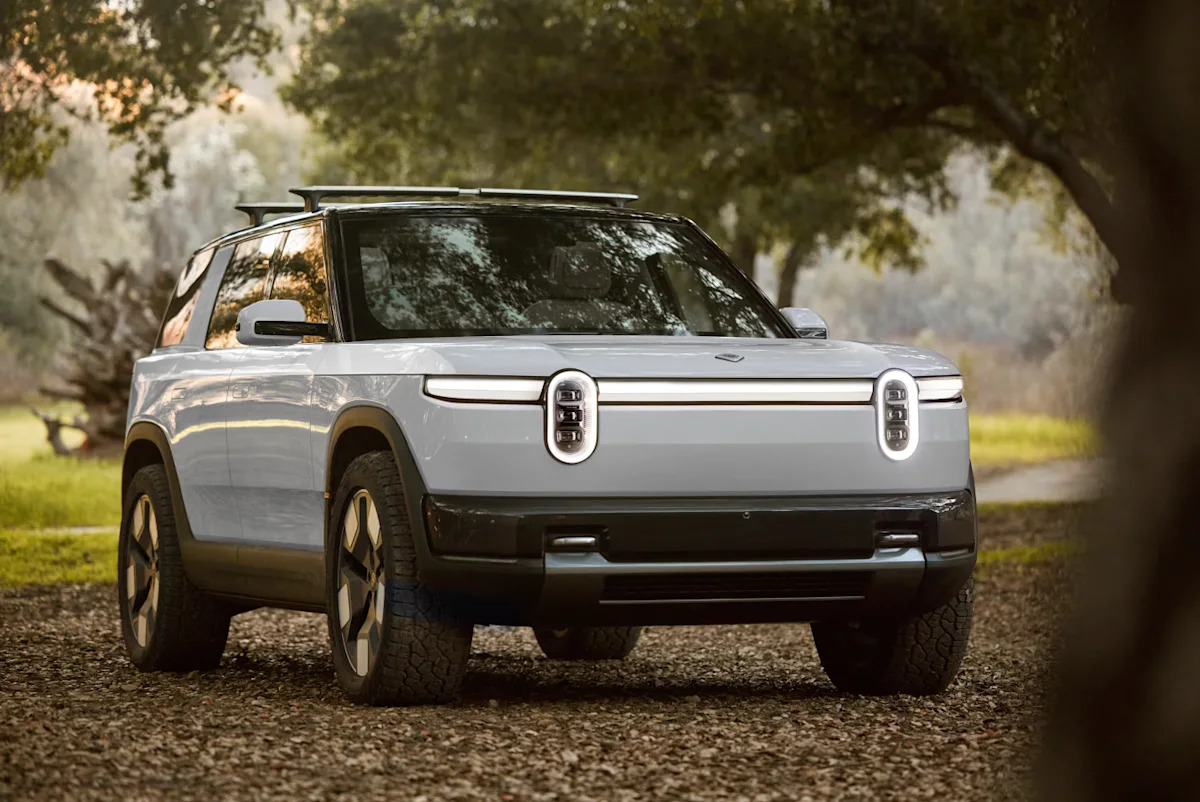
Rivian's highly anticipated R2 SUV. Image source: Rivian Automotive.
UBS also described initial R2 demand as solid, suggesting an encouraging foundation as more trim levels become available, as well as lower pricing. That's the analysts' assessment, rather than proof that every future version will find eager buyers. The investment opportunity rests on what comes next: whether Rivian can sustain that demand while turning a growing vehicle business into a more profitable one.
Rivian's automotive business posted an $80 million gross loss in the third quarter. Companywide gross profit was positive, but its software and services business provided the strength needed to offset that automotive loss.
That leaves two straightforward things to watch: whether R2 keeps attracting buyers as the launch progresses, sending deliveries to new heights, and whether automotive gross margins improve as production settles into a rhythm and efficiencies begin to add up. A falling share price doesn't automatically make a stock cheap, but it can create an interesting opportunity for investors willing to accept risk in such a young company.
That's the useful takeaway from this upgrade. Investors don't need to agree with a $17 target to understand the argument. Rivian's R2 is gaining traction, but now Rivian needs to show that its next chapter includes improving automotive segment profits alongside more vehicles.
Most investors think they missed the AI boat because they didn't buy Nvidia in 2005.
But according to our analysts, we're only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout, a massive technology build-out that Google's CEO says could be more profound than fire or electricity.
While everyone watches the chip designers, one "backbone" company provides the critical technology that Nvidia and AMD literally cannot function without. We've detailed this under-the-radar player in our new AI Playbook.
Daniel Miller has no position in any of the stocks mentioned. The Motley Fool has no position in any of the stocks mentioned. The Motley Fool has a disclosure policy.
Rivian Just Earned a Buy Rating. Is Wall Street Seeing a Turning Point? was originally published by The Motley Fool