3 British Lithium Stocks With Revenue Growth Up To 64% Bailey Pemberton Thu, November 12, 2026 at 11:12 AM EST 4 min read KOD.L -3.57% GC=F -3.11% RIO -1.36% GMTL -2.02% Trade RIO on Coinbase Trading disclosure Trading disclosure The above button links to Coinbase. Yahoo Finance is not a broker-dealer or investment adviser and does not offer securities or cryptocurrencies for sale or facilitate trading. Coinbase pays us for certain activity generated through this link. Prices displayed are informational.
Global power grid expansion just surged, with new transmission projects climbing 50% as governments race to secure electricity supplies and support electrification. That kind of build out tends to pull battery materials into the spotlight, which keeps interest in global lithium miners and processors alive for UK based investors watching long term trends. This article highlights three stocks from this lithium focused group that merit a closer look.
The three lithium ideas in this article are only a first pass, and the full screen surfaced 4 more miners and processors with equally compelling narratives that are not covered below. To see the complete lithium mining set, head straight to the Lithium Mining screener to identify, filter and analyze the highest conviction plays.
Kodal Minerals is a London based explorer focused on the Bougouni hard rock lithium project in southern Mali, backed up by other lithium and gold licences across West Africa. The group currently carries a market value of about £57 million.
The Bougouni project gives Kodal Minerals direct exposure to global lithium mining. Recent profitability, a low P/E near 11.9x and an earnings swing to £3.5 million in H1 2026 keep attention on how one unresolved funding and cash flow pressure shapes future returns from this asset.
That funding question is exactly what makes the DCF valuation analysis for Kodal Minerals so useful for weighing how Bougouni's cash flows might stack up against today's share price.
Rio Tinto Group gives lithium focused investors exposure to a large scale miner, where battery materials are growing inside a much bigger iron ore, aluminium and copper portfolio. The analyst consensus Narrative on Simply Wall St sets out how that lithium push fits into the wider growth story.
"Diversification into battery materials is moving forward as Rio Tinto Group brings the Fénix 1B expansion and Sal de Vida lithium projects in Argentina into operation ahead of schedule. This adds 25,000 tonnes per year of lithium carbonate equivalent capacity toward a 200,000 tonne goal by 2028, which directly increases potential revenue from lithium and exposure to electrification driven demand."
What really matters now is how one less visible constraint shapes the profitability investors eventually see from that growing lithium footprint.
That hinges on what is accelerating in the background, which the full narrative for Rio Tinto Group unpacks in detail so you can see what the headline lithium story might be masking.
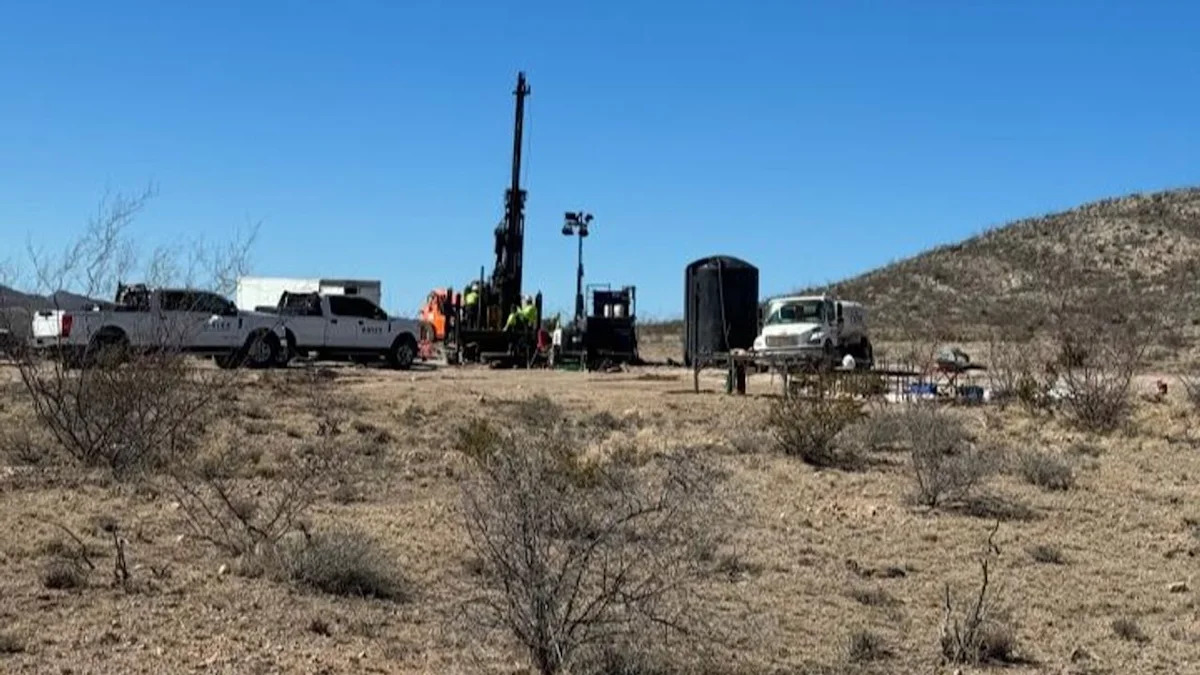
Guardian Metal Resources is a London based explorer focused on the Pilot Mountain project in Nevada, where lithium sits alongside tungsten, gold, copper and other metals. The group is still pre revenue and carries a market value of about £137.1 million.
Pilot Mountain gives Guardian Metal Resources direct exposure to the lithium mining theme through exploration drilling in Nevada, even though tungsten currently dominates project newsflow. Investors are effectively backing lithium discovery potential in a higher risk explorer that depends on fresh funding, as well as the outcome when one capital hungry work program meets a short cash runway.
That funding knife edge is exactly why the 2 key rewards and 5 important warning signs (4 are major!) could be worth a look, as it shows how Guardian Metal Resources' drilling upside balances that pressure.
Fresh opportunities can move from quiet to flying once momentum builds and early buyers get caught in the breakout. Scan these curated ideas while it matters and act now.
Target resilient payers throwing off income while others chase hype, then sift through the 4 dividend fortresses to spot yield opportunities before prices start dropping.
Hunt for mispriced quality that the market has not fully clocked yet by combing through the 17 high quality undervalued stocks while they are still under the radar for now.
Focus on real earnings momentum instead of stories by reviewing cash generative AI players inside the 42 profitable AI stocks that aren't just burning cash before they attract broader attention.
This article is general in nature and was produced with the assistance of AI automation, based on data and analysis from Simply Wall St. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com