AMD Has Opportunity As NVDA Faces Scrutiny And Potential Leadership Vacuum, William Blair Says — Sees Runway For Shares Harshita Tyagi Thu, November 12, 2026 at 7:24 AM EST 4 min read AMD +1.88% NVDA -7.91% Explore stocks on Coinbase Trading disclosure Trading disclosure The above button links to Coinbase. Yahoo Finance is not a broker-dealer or investment adviser and does not offer securities or cryptocurrencies for sale or facilitate trading. Coinbase pays us for certain activity generated through this link. Prices displayed are informational.
William Blair upgraded AMD to 'Outperform' without a price target, saying the risk/reward has shifted in the chipmaker's favor.
The firm expects AMD's data-center AI revenue to surpass its server CPU business in Q4.
BofA raised its AMD price target to $700 from $650, reiterating the chipmaker as its top CPU pick.
Advanced Micro Devices (AMD) was upgraded by William Blair on Thursday, with the brokerage citing an improving risk/reward outlook as its biggest AI chip rival, Nvidia (NVDA), faces leadership uncertainty.
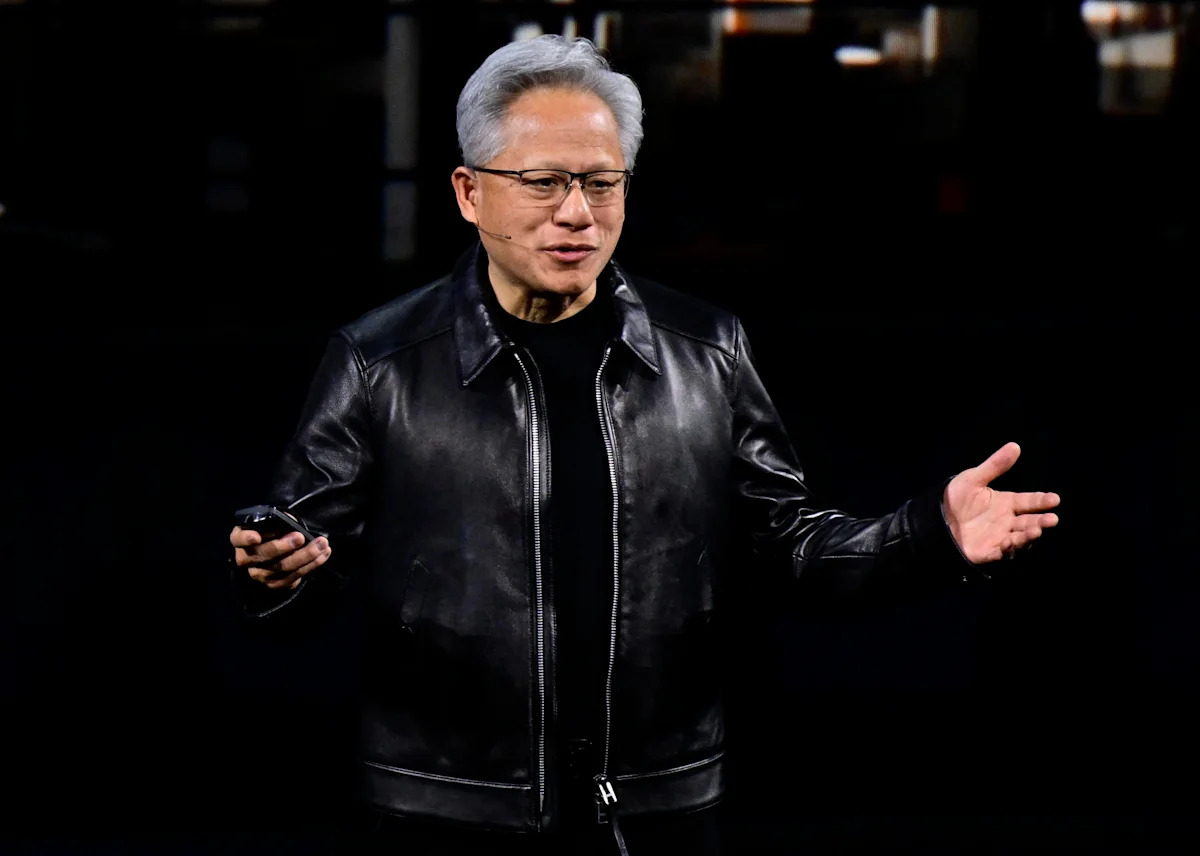
The upgrade comes amid growing uncertainty at Nvidia following reports of CEO Jensen Huang's alleged extramarital relationships, including one involving a woman suspected of having links to Chinese intelligence. Nvidia's board is meeting to discuss Huang's possible removal, raising questions about the chipmaker's leadership succession.
See what 10M+ investors are talking about. Get the Stocktwits Daily Rip for what retail is watching right now, free to your inbox
According to a note cited by TheFly, William Blair upgraded AMD to 'Outperform' from 'Market Perform,' saying the stock has room to rise as Nvidia faces scrutiny and a leadership vacuum, while AMD's competitive position improves and its valuation looks attractive.
At the time of writing in premarket trading, AMD stock was up 3% while NVDA stock was down nearly 7%.
William Blair said all four factors behind its previous rating have shifted in AMD's favor since it initiated coverage in July.
Intel's (INTC) Xeon server processor roadmap continues to face delays and supply shortages, while the transition toward Arm-based host processors has proved less disruptive than previously anticipated, Investing.com reported, citing the note.
The firm also noted that AMD's valuation multiple has declined significantly even as earnings estimates have risen.
Analysts at William Blair expect AMD's data-center AI revenue to surpass its server central processing unit (CPU) business in the fourth quarter, supported by its Helios AI systems ramping through 2027. It sees the potential for more than 80% revenue growth next year, over twice its longer-term model.
AMD and Broadcom (AVGO) gained as investors considered whether Nvidia customers might diversify their chip suppliers. Floodlines Research founder Anna Wu told Bloomberg, "AMD as a direct competitor, and Alphabet and Broadcom in the TPU space, are natural beneficiaries in the short term."
Meanwhile, a Barron's report cited Pepperstone analyst Chris Weston, who said markets appeared to distinguish between Nvidia-specific risks and the broader AI trade, suggesting investors were not treating Huang's situation as a fundamental threat to AI demand.
BofA raised its AMD price target to $700 from $650, maintaining a 'Buy' rating, according to TheFly. The firm reiterated AMD as its top central processing unit (CPU) pick, citing its broad product portfolio, leadership across key segments, Zen 6 execution on 2-nanometer technology and improving supply visibility.
AMD's fiscal third-quarter revenue rose 45% year-over-year to $13.4 billion, while data-center revenue surged 97% to $8.5 billion, driven by strong sales of EPYC processors and Instinct graphics processing units (GPUs).
Management expects fourth-quarter revenue of around $17 billion, implying 66% year-over-year growth at the midpoint.
William Blair nevertheless flagged competition from custom application-specific integrated circuits (ASICs), particularly at Meta Platforms (META) and OpenAI, as a risk to AMD's Instinct business. However, the firm sees these custom chip programs creating additional opportunities for AMD's server CPUs, per the Investing.com report.
On Stocktwits, retail investors' sentiment around AMD stock remained in the 'extremely bullish' territory amid high user message volume.
So far this year, AMD's share price has more than doubled, surging by over 147%. In comparison, the Invesco NASDAQ 100 ETF (QQQM) and the State Street Technology Select Sector SPDR ETF (XLK), which hold the stock, have risen 12% and 21%, respectively, over the same period.
See Also: AI-Optimized Server Spending To Reach Nearly $957B In 2027, Says Gartner — Global AI Spending To Cross $4T
For updates and corrections, email newsroom[at]stocktwits[dot]com.
Harshita Tyagi has no position in any of the stocks mentioned in this article. StockTwits' news team content is for informational purposes only and is not intended as investment advice. For more, see our editorial policy. This article was originally published on StockTwits.
NVDA Stock On Track To Hit Lowest Level In Over A Year: Dan Ives Values Nvidia At $225 Without Jensen Huang
ESLT Stock In Focus After $260M NATO Deal – CEO Highlights Continued European And NATO Selection Of PULS Systems
AI-Optimized Server Spending To Reach Nearly $957B In 2027, Says Gartner — Global AI Spending To Cross $4T