MP Gains 2% After Q3 Earnings Beat: Reason Enough to Buy the Stock? Madhurima Das Thu, November 12, 2026 at 2:19 AM EST 6 min read ^GSPC +1.31% MP -1.17% AAPL +0.08% UUUU -1.32% LYSCF +3.50% Explore stocks on Coinbase Trading disclosure Trading disclosure The above button links to Coinbase. Yahoo Finance is not a broker-dealer or investment adviser and does not offer securities or cryptocurrencies for sale or facilitate trading. Coinbase pays us for certain activity generated through this link. Prices displayed are informational.
MP Materials MP delivered a stronger-than-expected third-quarter 2026 performance on Nov. 5, driven by robust growth in rare earth production, higher NdPr sales volumes and improved pricing. Revenues surged 176% year over year to $147.7 million while adjusted earnings swung to a profit of 4 cents per share from the loss of 10 cents in the year-ago quarter. The company also made progress in expanding its domestic magnet manufacturing operations, marking another step toward strengthening its position in the U.S. rare earth supply chain.
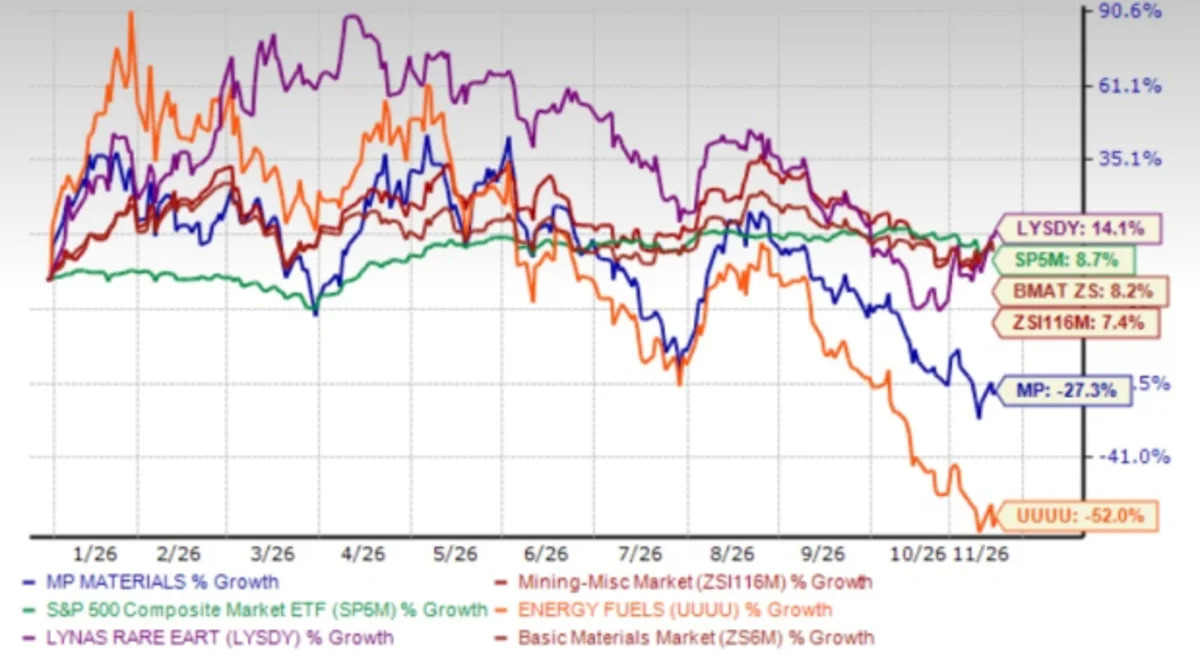
MP shares have gained 2% since the earnings release. However, the recovery has done little to offset the stock's broader weakness. MP stock has declined 27.3% year to date, trailing the Zacks Mining - Miscellaneous industry's growth of 7.4%, the Zacks Basic Materials sector's 8.2% gain and the S&P 500's rise of 8.7%. Peer Energy Fuels UUUU has declined 52% year to date while Lynas Rare Earths Limited LYSDY advanced 14.1%.
Before addressing the critical question of how investors should position themselves regarding the stock, let us first review the company's third-quarter results.
MP Materials produced 1,018 metric tons of neodymium-praseodymium (NdPr), up 41% year over year, reflecting stronger output from the company's separation and finishing operations at Mountain Pass. NdPr sales volumes surged 94% to 1,020 metric tons.
The Materials segment's revenues soared 322% year over year to $133.5 million. NdPr oxide and metal revenues surged 227% to $100.96 million, benefiting from higher sales volumes and stronger market pricing.
In September 2026, the company had entered into a one-time sale agreement with a U.S. aerospace and defense customer, under which it sold $31.6 million of a mixed heavy rare earth product containing samarium, europium, gadolinium and other heavy rare earths (SEG+) during the third quarter of 2026.
The Magnetics segment's revenues declined 15% year over year to $18.6 million, reflecting slightly lower magnetic precursor product sales as the company advanced the start-up of magnet production at its Independence Facility.MP's total revenues rose 176% year over year to $147.7 million. MP also recorded $8.11 million in income tied to a price protection agreement (PPA) with the Department of War (DoW).
MP achieved another important commercial milestone during the quarter by completing the magnet qualification process with General Motors Company (GM). Management expects saleable magnet deliveries and associated revenues to commence in the fourth quarter of 2026, supporting the company's transition toward higher-value downstream operations.
Despite the strong revenue growth, MP continues to face considerable cost pressures as it expands beyond rare earth concentrate production into separated products and magnets.
Cost of sales increased 76.6% year over year in the third quarter, reflecting higher sales volumes of NdPr oxide and metals. Selling, general and administrative expenses rose 33.8%, primarily due to higher personnel costs associated with downstream expansion. Start-up expenses also climbed significantly to $14.15 million from $1.41 million a year earlier as initial magnet manufacturing activities gathered pace.
Advanced projects and development expenses declined sharply to $1.90 million from $19.03 million, partly reflecting the absence of transaction-related expenses incurred in the prior-year period.
Despite the higher expenses, MP's consolidated adjusted EBITDA improved substantially to $41.14 million from a loss of $12.57 million in the year-ago quarter. The operating loss narrowed to $22.06 million from $67.02 million, reflecting higher revenues and PPA-related income, which partly offset increased operating expenses.
However, costs are likely to remain elevated in 2026 and 2027, as producing separated rare earth products and magnetic materials involves significantly higher costs than concentrate production. Costs associated with magnetic precursor products and start-up costs are also likely to increase further in the coming quarters.
The Zacks Consensus Estimate for MP Materials' 2026 revenues indicates a 99% increase year over year. The estimate for earnings is currently pegged at a loss of 3 cents per share, narrower than the loss of 24 cents reported in 2025.
For 2027, the consensus estimate points to revenue growth of 58.8%, with earnings expected to reach 66 cents per share.
MP's growth outlook remains strong, but the Zacks Consensus Estimate for earnings for both 2026 and 2027 has moved down over the past 60 days. It suggests that analysts are becoming more cautious about its near-term profitability.
MP stock is trading at a forward 12-month price/sales multiple of 9.33X, significantly higher than the industry's 1.46X. MP has a Value Score of F, reflecting this expensive valuation, with the forward sales multiple also standing above the broader Basic Materials sector's valuation and the company's five-year median.
Energy Fuels trades at an even steeper multiple of 12.86X, while Lynas Rare Earths appears comparatively cheaper at 7.76X.
Despite near-term profitability challenges, MP continues to make progress on several strategic initiatives that could strengthen its competitive position in the rare earth and magnet markets.
During the third quarter, the company advanced the refining of its SEG+ production stream and expects to begin producing separated terbium and dysprosium by the end of 2026. Under its partnership with the U.S. Department of War, MP has also committed to expanding its heavy rare earth refining capabilities to include samarium oxide separation and recommissioning the chlor-alkali facilities at Mountain Pass.
Its agreement with Apple Inc. AAPL represents another important growth opportunity. Under the partnership, MP plans to develop and install scaled magnet recycling capabilities at Mountain Pass, with dedicated capacity for both NdPr and heavy rare earth separation.
Meanwhile, construction of the 10X facility remains on track, with commissioning expected to begin in 2028. The facility is designed to produce approximately 7,000 metric tons of magnets annually. Combined with the 3,000-metric-ton annual capacity of the Independence facility, MP's total U.S. magnet production capacity is expected to reach 10,000 metric tons.
MP Materials' latest quarterly performance highlights meaningful progress in expanding production, increasing NdPr sales and developing its domestic magnet manufacturing business. Its strategic partnerships with the U.S. Department of War, Apple and General Motors further strengthen its long-term growth prospects.
However, the investment case is less compelling from a near-term valuation and earnings perspective. Operating losses persist, expansion-related costs remain elevated and downward earnings estimate revisions point to continued uncertainty around profitability. Moreover, MP trades at a substantial premium to the industry despite its significant year-to-date underperformance.
Given these concerns, investors may prefer to remain on the sidelines for now. MP Materials currently carries a Zacks Rank #4 (Sell).
You can see the complete list of today's Zacks #1 Rank (Strong Buy) stocks here.
Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
MP Materials Corp. (MP) : Free Stock Analysis Report
Energy Fuels Inc (UUUU) : Free Stock Analysis Report
Lynas Rare Earths Limited - Sponsored ADR (LYSDY) : Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).