Apple Shares (AAPL) Look Expensive Heading into 2027 TipRanks Wed, November 11, 2026 at 4:15 PM EST 5 min read AAPL +2.44% QQQ +1.79% MU +11.09% LLY +1.09% Explore stocks on Coinbase Trading disclosure Trading disclosure The above button links to Coinbase. Yahoo Finance is not a broker-dealer or investment adviser and does not offer securities or cryptocurrencies for sale or facilitate trading. Coinbase pays us for certain activity generated through this link. Prices displayed are informational.
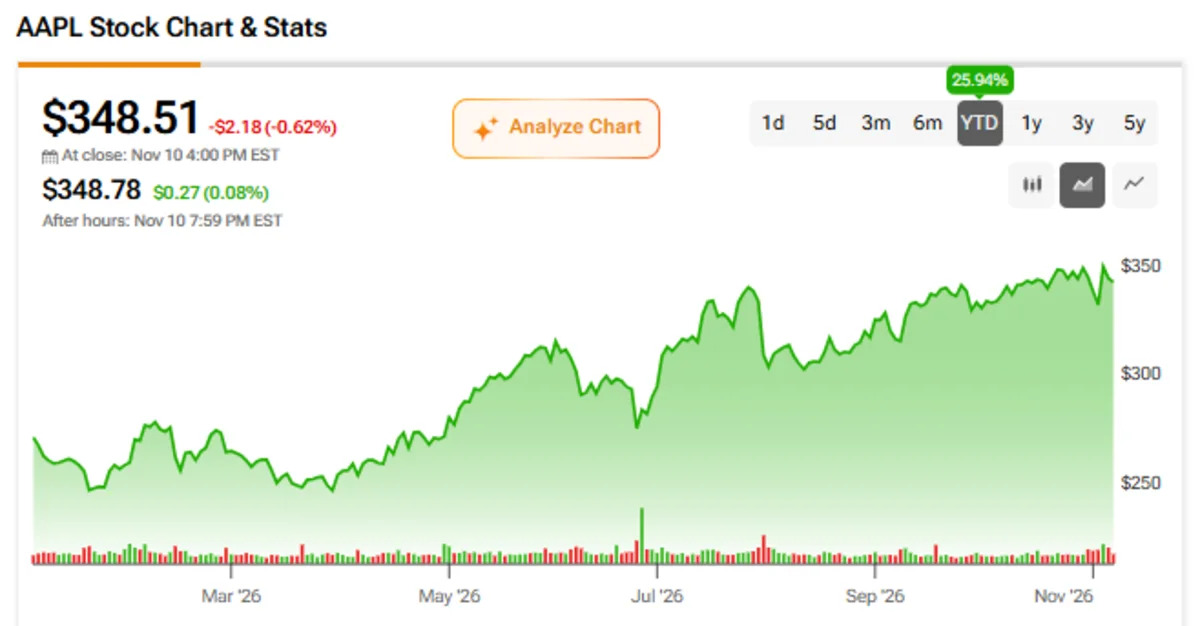
Apple (AAPL) shares look expensive heading into 2027, despite the company's strong growth prospects. Shares of the iPhone maker have soared in 2026, easily outperforming the Nasdaq-100 (NDX) as tracked by the Invesco QQQ Trust (QQQ). This comes as Apple has delivered higher sales and revenues this year, a trend analysts expect to continue into Fiscal 2027.
What is more, Apple may benefit from higher device sales should memory costs normalize, potentially making the shares interesting for investors looking to diversify their artificial intelligence (AI) exposure away from current high memory cost beneficiaries such as Micron (MU).
Despite these positives for the Apple investment case, my rating on the shares remains a Hold. I believe that with the stock trading at 37.08x analysts' consensus 2027 earnings per share (EPS) estimate of $9.40, the outlook for investor returns is quite modest even as the company is likely to continue its strong underlying performance.
Get 75% Off TipRanks Premium and unlock powerful investing tools to make smarter, more confident investment decisions
Apple delivered Q4 2026 EPS of $2.10, a 14% increase relative to the prior-year quarter and a Q4 record for the company from a historical perspective. While results were boosted by a $0.05 per share one-off tariff refund, underlying performance was nevertheless quite strong.
Case in point, Apple sales increased 12% year-over-year, driven by the low-margin products segment. Apple cited strong iPhone demand as a key revenue driver. Growth in the high-margin services business was somewhat weaker, at 10% year-over-year. A 32% year-over-year increase in research & development expenses was a relative disappointment, although this should help Apple's innovation over the medium term.
CEO John Ternus was quite optimistic for the company's prospects going into Q1 2027. He said, "We're closing the year with our most ambitious lineup yet. That includes the iPhone Duo, the most transformational iPhone since the original, alongside iPhone 18 Pro and iPhone 18 Pro Max, our most powerful iPhones yet. We also just introduced a whole new generation of hardware for the home and brought Touch to Mac for the first time. Together with the all-new Siri AI, it's an incredible lineup to carry us into the holiday season."
Despite the strong product pipeline, Apple's forecast for Q1 2027 shows that the company anticipates total revenue to increase by about 7%–10% year-over-year, with Services revenue growing by about 8%–9%. As such, we do see that the company expects a near-term slowdown relative to the growth rate achieved in Q4 2026.
To sum up, while the one-off tariff benefit and somewhat weaker growth in the Services business arguably support my Hold on Apple, I must admit that the underlying performance of the company remains quite reasonable. As I will discuss in the next section, however, the strong revenue and earnings momentum going into 2027 appears priced in.
Analysts expect Apple to generate EPS of about $9.40 in Fiscal 2027, implying roughly 4.8% growth relative to the $8.97 EPS achieved in 2026. The earnings increase is projected to be driven more by higher sales than by a meaningful pickup in margins, as revenues are expected to be about 10% higher at $527.53 billion.
Indeed, I expect the low-margin products revenue category to continue to be a key sales contributor to Apple's top line. This comes as the initial sales results of iPhone Duo will begin to be booked in Fiscal 2027.
Product margins are currently squeezed by high memory costs. The silver lining is that Apple's product margin may see a recovery in 2028–2029, when I expect the memory shortage to begin to normalize. As such, I do see Apple's earnings trajectory increasing over the medium term.
Unfortunately, this positive medium-term backdrop appears to be priced into Apple stock, as it already trades at 37.08x expected 2027 earnings. This high valuation is a key factor in my Hold rating, as Apple trades at a hefty premium to the S&P 500's (SPX) 19.8x forward P/E multiple. This kind of valuation premium is typically reserved for conservative health care companies such as Eli Lilly (LLY), rather than consumer electronics companies such as Apple, which can see a downturn in sales during recessions.
To conclude, while Apple may offer diversification benefits for technology investors thanks to a potential acceleration in device sales if memory costs decline, I believe this year's stellar returns have frontloaded gains. Indeed, Apple stock may fail to produce attractive returns over the medium term, even as the company's earnings and sales continue to grow.
On Wall Street, Apple has a Moderate Buy consensus rating, based on 15 Buy, eight Hold, and six Sell ratings over the past three months. The average Apple price target is currently $338.28, implying roughly 3% downside over the next 12 months.
Apple stock has soared in 2026, with investors rewarding the company for its double-digit revenue and earnings expansion. While a near-term slowdown in Q1 2027 cannot be ruled out based on company guidance, analysts expect full-year 2027 performance to reflect a moderation in growth rates relative to Fiscal 2026.
Looking further ahead, Apple's margins may recover in 2028–2029 should memory costs decline. This could make the shares interesting for investors looking to diversify their technology exposure with companies like Apple, which can deliver higher earnings even as AI capex spending slows.
Despite these positives, my rating on Apple is a Hold. Strong recent gains have pushed the company's valuation well above the S&P 500, potentially indicating that the shares may deliver lackluster returns even as earnings and revenues continue to grow.
This is also evident from Wall Street's 12-month consensus price target for Apple, which implies slight downside from current levels. As such, Apple appears to be a business that is doing quite well on an underlying basis, but nevertheless is likely to deliver modest gains for investors over the medium term.