Synopsys at $460: Appealing Ahead of Dec. 8 Earnings Alex Sirois Wed, November 11, 2026 at 12:45 PM EST 5 min read SNPS +1.38% ^GSPC +1.51% Trade SNPS on Coinbase Trading disclosure Trading disclosure The above button links to Coinbase. Yahoo Finance is not a broker-dealer or investment adviser and does not offer securities or cryptocurrencies for sale or facilitate trading. Coinbase pays us for certain activity generated through this link. Prices displayed are informational.
Synopsys (SNPS) trades at $460, down 2% this year while the S&P 500 gains 10%, despite four straight earnings beats and raised guidance.
Analysts see 28% upside to a $590 average target, with 23 of 25 rating the stock Buy or Strong Buy and none Sell.
Fiscal 2027 guidance will decide the debate, as investors seek double-digit EDA growth, sequential IP gains and progress on licensing-plus-royalty deals.
Building a portfolio and living off one are two completely different skills, and almost nobody teaches the second. This problem is what The Definitive Guide to Retirement Income helps, and it is free today. Read more here. (Sponsor)
Synopsys (NASDAQ:SNPS) trades at $459.95, a price below where the stock started the year even though earnings estimates keep rising ahead of its fiscal fourth-quarter report.
Synopsys leads the market for electronic design automation (EDA), the software chipmakers use to design and verify chips, and it also licenses silicon IP. Its ~$35B Ansys acquisition extended the company into simulation, covering everything from silicon to full systems. The shares have dropped 9.81% over the past month and remain well below the 52-week high of $539.48.
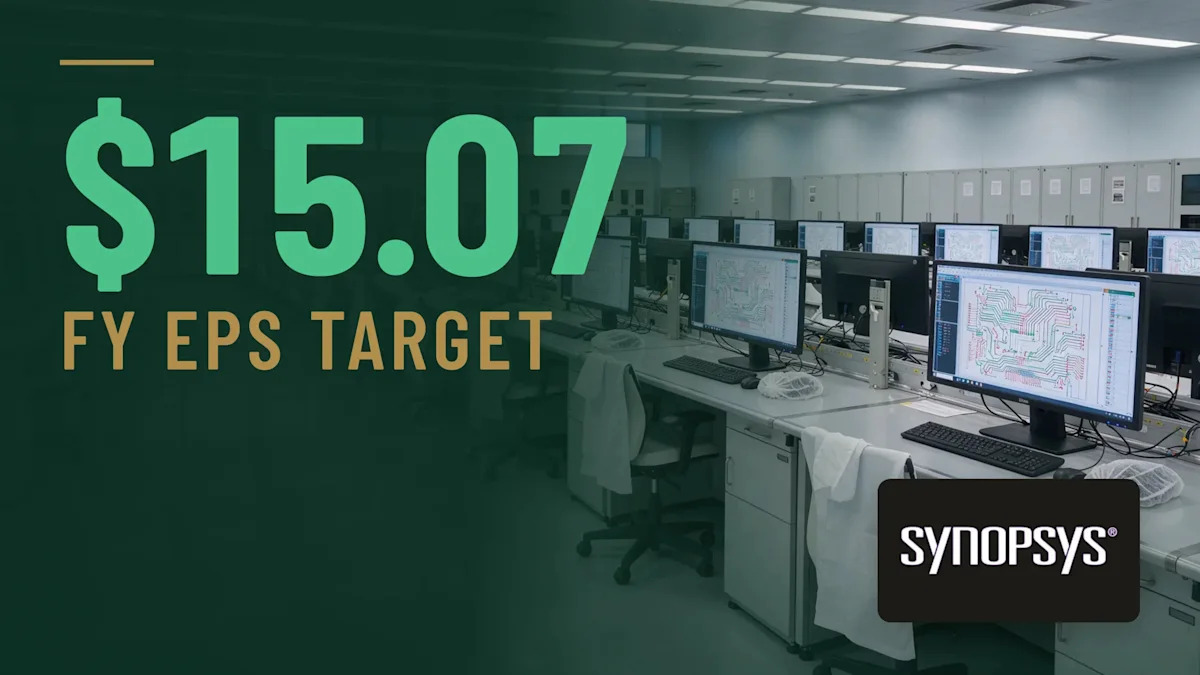
Third-quarter revenue reached $2.48B, up 42.4%. Non-GAAP EPS of $3.91 exceeded the $3.67 consensus, and that was the 4th straight beat. Management then raised full-year guidance to a $15.07 non-GAAP EPS target. The stock trades at a forward P/E of 25, compared with a trailing figure of 83.
Analysts have made 14 upward revisions to fiscal 2027 EPS in the past 30 days, bringing the average to $18.6455. Design IP grew roughly 11%, and management expects Multiphysics Fusion to add to EDA growth in 2027. CEO Sassine Ghazi said "EDA is accelerating. Design IP has returned to growth and Ansys is performing strongly."
Many successful investors eventually reach the same moment. The saving is done, the portfolio is built, and the question quietly changes from how much can I grow this to how much can I take out? Get that second question wrong and decades of good investing can come apart in a handful of years.
That is exactly what The Definitive Guide to Retirement Income helps answer. It covers what your retirement could actually cost, which income sources are worth using, and the withdrawal math that decides whether the money lasts. It is free today from Fisher Investments. Read More Here ›
Synopsys carries approximately $10 billion of debt. About $404M of intangible assets amortization each quarter weighs on GAAP results, and GAAP net income in the second quarter fell to just $17.1M. Company filings also flag shareholder lawsuits over Design IP disclosures, a Morgan Stanley downgrade warning of slowing growth, and export control risk tied to China.
Beating estimates has often failed to lift the shares. After the third-quarter beat, the stock rose 13.39% on the day and then gave back 10.45% over the following week. Backlog slid to $10.9 billion from the prior quarter.
Fourth-quarter non-GAAP EPS guidance from management came in at $4.10–$4.16, with consensus at $4.1332. The fiscal 2027 outlook matters more than the quarter itself. Investors will look for double-digit EDA growth, sequential IP gains and progress on licensing-plus-royalty deals before committing either way.
The average analyst target of $589.55 implies 28.2% upside from $459.95. Targets are estimates and carry no guarantee. Of the 25 analysts covering the stock:
So far this year, Synopsys is down 2.08% while the S&P 500 is up 9.99%. Over one year, Synopsys has gained 14.77%, ahead of the index at 10.06%.
At $459.95, several factors shape the outlook for Synopsys.
The stock trades at roughly 25 times fiscal 2027 consensus EPS, yet analysts keep raising that number. Management has beaten estimates for four quarters in a row, and the fourth-quarter consensus sits inside guidance. That leaves room for another beat.
The path higher depends on fiscal 2027 guidance that shows EDA acceleration and early revenue from Multiphysics Fusion and the more than 30 agentic AI projects now underway. Free cash flow of about $2.6B keeps paying down debt, which should ease the main bear concern over the next several quarters.
The investment thesis falls apart if fiscal 2027 guidance points to slowing EDA growth, or if Design IP slips again. Past post-earnings swings mean volatility is likely, and the stock has already fallen 9.81% over the past month. The shares currently reflect accelerating AI-driven earnings at a multiple that already prices in plenty of doubt.
(Sponsor) Most people spend their entire working lives focusing on one thing: growing a pile of money. Then they retire and discover the skill they actually need is close to the opposite. Turning that pile into steady income, year after year, through good markets and bad, without ever running out.
It may be the least discussed and most consequential transition in personal finance, and plenty of otherwise careful investors walk into it with no real plan. That is exactly what The Definitive Guide to Retirement Income helps answer. It is a free guide from Fisher Investments covering what your retirement will really cost, where the cash flow should come from, and how much you can safely withdraw each year. Learn more here. Learn More Here ›
Contact editorial@247wallst.com for any questions or corrections.