AMD Price Prediction: AI Boom and Record Revenue Set the Stage for Another Monster Rally Vandita Jadeja Wed, November 11, 2026 at 10:03 AM EST 6 min read AMD +5.16% NVDA +2.07% INTC +6.21% Explore stocks on Coinbase Trading disclosure Trading disclosure The above button links to Coinbase. Yahoo Finance is not a broker-dealer or investment adviser and does not offer securities or cryptocurrencies for sale or facilitate trading. Coinbase pays us for certain activity generated through this link. Prices displayed are informational.
AMD (AMD) posted record quarterly revenue up 45% and guided Q4 sales up 66%, yet trades 26% below its 52-week high.
NVIDIA (NVDA) trades at a trailing P/E of 40 versus AMD's 123, while Intel (INTC) still posts a negative P/E.
Lisa Su says "We now expect revenue to grow more than 80% in 2027," fueling a $682 bull case.
Building a portfolio and living off one are two completely different skills, and almost nobody teaches the second. This problem is what The Definitive Guide to Retirement Income helps, and it is free today. Read more here. (Sponsor)
The 24/7 Wall St. price target for Advanced Micro Devices (NASDAQ:AMD) is $514.18 over the next 12 months. That means 5.2% upside from the $488.78 close. The model gives AMD a buy rating with high confidence.
AMD just reported a record quarter, yet the stock trades 25.8% below its 52-week high while management guides for faster growth. The gap between how fast the business is growing and where the stock sits right now drives our positive view.
Shares fell 15.5% over the past week and 22.63% over the past month. Even so, AMD is still up 128.23% year to date and 159.7% above its 52-week low of $188.22.
Third quarter revenue reached $13.38B, up 44.7% YoY and ahead of the $13.08B consensus. Non-GAAP EPS of $2.09 beat the $1.94 estimate. Data Center sales climbed 97% to $8.55B, and segment operating margin widened to 34% from 25%. The stock rose after the report because fourth quarter guidance calls for roughly $17.0B in revenue, about 66% YoY growth at the midpoint.
Many successful investors eventually reach the same moment. The saving is done, the portfolio is built, and the question quietly changes from how much can I grow this to how much can I take out? Get that second question wrong and decades of good investing can come apart in a handful of years.
That is exactly what The Definitive Guide to Retirement Income helps answer. It covers what your retirement could actually cost, which income sources are worth using, and the withdrawal math that decides whether the money lasts. It is free today from Fisher Investments. Read More Here ›
The bull case reaches $682.33, about 39.6% above today's price. Anthropic, Meta, Microsoft, OpenAI and Oracle brought their first Helios racks online last quarter. Management expects Data Center revenue to grow about 50% sequentially in the fourth quarter.
CEO Lisa Su raised the bar further: "We now expect revenue to grow more than 80% in 2027." She also expects operating expenses to grow less than half as fast as revenue, which points to wider margins. On top of that, Meta's commitment for up to 6 GW of Instinct GPUs gives AMD visibility for years.
The consensus target is $649.38, with 5 Strong Buy, 39 Buy and 11 Hold ratings and no Sells.
The bear case comes to at $410.75, roughly 16% below the current price. Free cash flow fell 70.9% to $554M. Inventory rose 35% from the prior quarter to $11.46B. Its free cash flow multiple stands at 119.1. Gaming revenue dropped 40%, and export controls remain a risk after $440M in FY25 inventory charges linked to China restrictions on the MI308.
Management says the drop in free cash flow came from working capital and capex spent to secure capacity. The inventory build supports data center demand that exceeds supply. GAAP EPS of $1.46 included a $1,097M non-cash warrant charge that leaves non-GAAP results and free cash flow unchanged.
AMD's direct competition in AI accelerators is NVIDIA (NASDAQ:NVDA). The stock carries a trailing P/E of 40 and about 50 times free cash flow, and its latest quarterly revenue rose 105.85% to $96.22 billion. That makes NVIDIA cheaper on current earnings, which argues against setting an AMD target far above consensus.
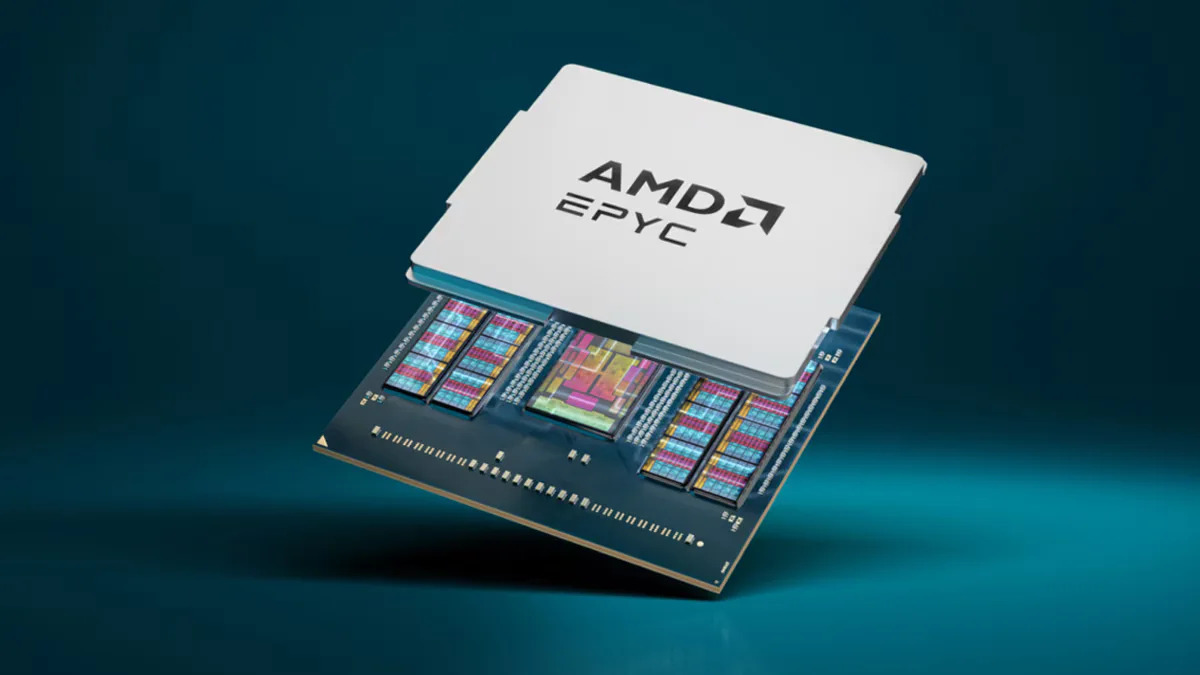
Intel (NASDAQ:INTC) competes with EPYC in server CPUs. Data Center and AI revenue grew 78% to $7.318 billion, but the company still posts a negative P/E and operating margin. Intel shows that AI demand only pays off with execution behind it, and AMD's track record of execution supports its premium.
AMD's forward P/E of 29 is far lower than its trailing multiple. Against this peer group, our target looks reasonable.
The 24/7 Wall St. price target of $514.18 carries a buy rating with 90% confidence. The fourth quarter guide supports that rating.
The outlook strengthens if Helios deployments increase as expected and free cash flow recovers as inventory turns into sales. The outlook weakens if supply limits or export rules delay the MI450 increase. As things stand, the growth path outweighs the valuation risk.
Our model projects where AMD could trade if current growth trends and market conditions hold.
These projections assume AMD keeps executing on its data center strategy. Results could come to well above or below them depending on how the MI500 generation is adopted and on export-control policy. The traits that showed up early in the last decade's biggest chip winner are the ones we cataloged in a free playbook on spotting the next one.
(Sponsor) Most people spend their entire working lives focusing on one thing: growing a pile of money. Then they retire and discover the skill they actually need is close to the opposite. Turning that pile into steady income, year after year, through good markets and bad, without ever running out.
It may be the least discussed and most consequential transition in personal finance, and plenty of otherwise careful investors walk into it with no real plan. That is exactly what The Definitive Guide to Retirement Income helps answer. It is a free guide from Fisher Investments covering what your retirement will really cost, where the cash flow should come from, and how much you can safely withdraw each year. Learn more here. Learn More Here ›
Contact editorial@247wallst.com for any questions or corrections.