002594.SZ -0.54% NVDA -4.29% Trade NVIDIA on Coinbase Trading disclosure Trading disclosure The above button links to Coinbase. Yahoo Finance is not a broker-dealer or investment adviser and does not offer securities or cryptocurrencies for sale or facilitate trading. Coinbase pays us for certain activity generated through this link. Prices displayed are informational.
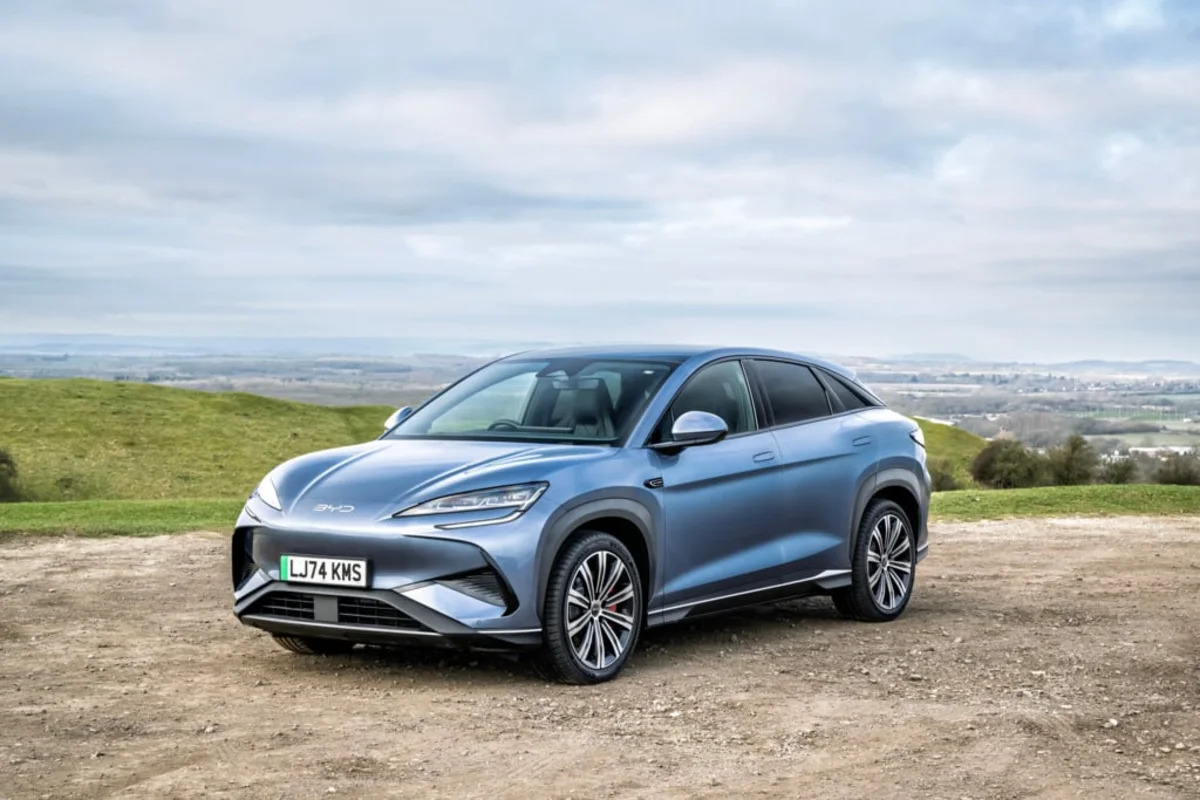
BYD Co. (OTC: BYDDF) investors finally have a revenue recovery to chew on. Third-quarter revenue increased 13.6% year over year to 221.5 billion yuan, ending four consecutive quarters of declines. Better yet, looking at the bottom line, net profit rose roughly 28% to 10 billion yuan. That sounds like a quarter worth celebrating. Unfortunately, Wall Street forgot to bring the confetti: Net profit fell short of the estimates from three brokerages compiled by Reuters.
A rebound can be real and still leave Wall Street wanting more. For BYD investors, two questions could help determine whether this recovery has legs.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
BYD's global vehicle sales increased 18.8% in Q3, to more than 1.32 million. Overseas shipments more than doubled, helping offset weaker sales in China, according to Reuters.
That's been the strategy of BYD, and just about every other automaker competing in China, because China's domestic auto market sales hit a speed bump and remain in a brutal price war -- a nasty combination. An expanding international business gives BYD another place to find customers when its home market gets tougher, especially if overseas sales prove more profitable until China's market balances and the price war lightens. That said, investors would have a stronger BYD rebound on their hands if China stopped needing to be offset.
Competition remains fierce. Rival Geely's faster-charging technology is expanding its network, and competitively priced vehicles from Stellantis-backed Leapmotor are giving consumers more options. For all of Tesla's (NASDAQ: TSLA) woes, its product lineup remains surprisingly resilient considering the lack of major vehicle refreshes or launches. For investors, the next encouraging development would be a recovery in domestic sales alongside continued improvement in companywide profitability. That would give BYD's rebound a broader foundation and offer investors more reason to celebrate.
Export growth gives BYD an opportunity, but a passport isn't a guarantee of profits, because there are familiar faces joining the overseas auto battle. Competition from other Chinese automakers is also intensifying overseas. BYD's international expansion therefore shouldn't be treated as an escape hatch from competitive pressure.
In fact, BYD's Chinese rival Geely has the same playbook and offers a perfect example. Geely's Q3 net profit also increased roughly 28%, with overseas growth helping counter slowing demand in China. That's encouraging for the industry, but it also reminds investors that BYD's competitors have passports, too. On the other hand, what nobody wants is for Chinese automakers to export their domestic price war to the rest of the world.
Investors should watch whether growing overseas sales continue translating into stronger companywide earnings. It would also be useful to see more detail on regional profitability before assuming every vehicle sold abroad delivers superior returns. Investors will also want to watch which Chinese or other new foreign competitors can better avoid or offset some tariffs or set up local operations to gain a competitive edge.
There's an important distinction here: Expanding into more markets can make a business more diversified without automatically making each sale more profitable. BYD needs both the customers and the economics to make its expansion more valuable.
The quarter offers encouragement: Revenue returned to growth and profit increased. But the investment case needs more than a better-looking earnings headline. A healthier domestic business would give the recovery a second engine. Overseas expansion that supports lasting profit growth would make it more convincing still, especially if it can hold advantages overseas while avoiding a relocated Chinese price war.
On that note, investors don't need BYD to win every price war. They need evidence that the company can keep growing and leveraging its numerous competitive advantages into more durable profits.
The Motley Fool Stock Advisor analyst team just identified what they believe are the 10 best stocks for investors to buy now… and BYD wasn't one of them. The 10 stocks that made the cut could produce monster returns in the coming years.
Consider when Netflix made this list on December 17, 2004... if you invested $1,000 at the time of our recommendation, you'd have $344,878!* Or when Nvidia made this list on April 15, 2005... if you invested $1,000 at the time of our recommendation, you'd have $1,097,846!*
Now, it's worth noting Stock Advisor's total average return is 852% — a market-crushing outperformance compared to 208% for the S&P 500. Don't miss the latest top 10 list, available with Stock Advisor, and join an investing community built by individual investors for individual investors.
*Stock Advisor returns as of November 10, 2026.
Daniel Miller has no position in any of the stocks mentioned. The Motley Fool has positions in and recommends Tesla. The Motley Fool recommends BYD Company and Stellantis. The Motley Fool has a disclosure policy.
BYD's Profits Rebounded. These 2 Questions Will Decide What Comes Next. was originally published by The Motley Fool