Bank of America Is Doubling Down on Apple While Tech Sells Off. Here’s Its Price Target Vandita Jadeja Mon, November 9, 2026 at 9:03 AM EST 5 min read AAPL +2.19% BAC +1.95% MSFT +2.13% GOOG +3.03% Explore stocks on Coinbase Trading disclosure Trading disclosure The above button links to Coinbase. Yahoo Finance is not a broker-dealer or investment adviser and does not offer securities or cryptocurrencies for sale or facilitate trading. Coinbase pays us for certain activity generated through this link. Prices displayed are informational.
Apple (AAPL) posted its best fiscal year ever, and our model's $385 price target implies 11% upside despite memory-driven margin pressure.
Microsoft's $116 billion capex dwarfs Apple's $9 billion, which makes Apple's light spending a key reason the premium valuation looks reasonable.
Apple guided December gross margin down to 45%-46% from 48%, and the CEO called memory pricing "unprecedented."
Read More: Learn 7 ways to generate income with a $1,000,000+ portfolio (sponsor)
Bank of America (NYSE:BAC) analyst Wamsi Mohan is maintaining a buy rating on Apple (NASDAQ:AAPL) at a time when memory costs and a volatile tech market are testing investors' patience.
Our model is also bullish. Apple's 24/7 Wall St. price target is $384.73. That means 11.29% upside from where shares trade at $345.71.
A 70% confidence score means I have moderately high conviction. Apple just finished its best fiscal year ever, and management expects the December quarter to be the best quarter for revenue in the history of the company.
The main pressure on the target comes from memory-driven margin compression. My view is that Apple's cash generation and the size of its installed base outweigh that drag over the next 12 months.
Over the past week Apple fell 1.36%. It is up 3.16% over the past month and 26.95% year to date. Shares sit 2.48% below the 52-week high of $354.50 and 42.41% above the low of $242.76.
Fiscal Q4 revenue came in at $114.48 billion (+11.7% YoY), ahead of the $113.36 billion estimate. EPS of $2.10 beat expectations of $1.98, although that figure includes a $0.05 one-time benefit from tariff refunds. Even so, the stock sank as the global memory crisis hurt profits. It then surged alongside hyperscalers after election results removed uncertainty.
If you've saved over $1,000,000, this guide is for you. The last thing you want in retirement is to run out of money, you want your money to generate lasting income while you enjoy your life.
Now you can learn the strategies wealthy retirees use to fund their retirement with The Definitive Guide to Retirement Income from Fisher Investments. Download the guide today! (sponsor)
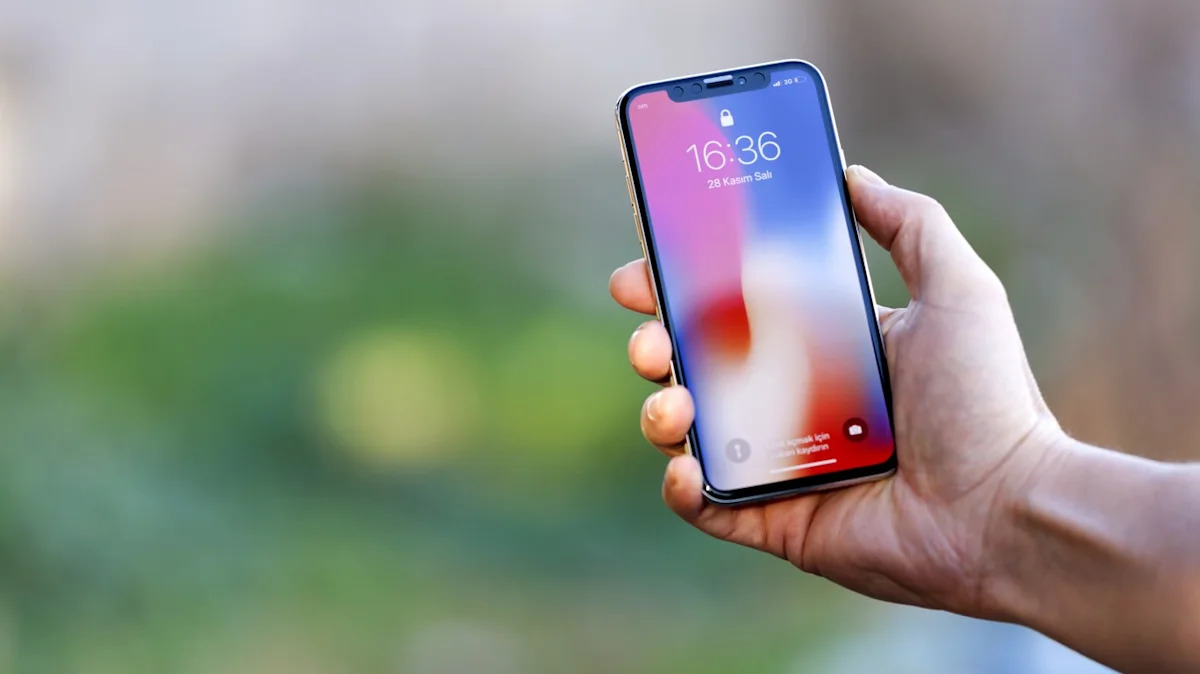
iPhone revenue reached $57.58 billion. The new iPhone Duo is supply constrained, and the chief executive calls it "the most transformational iPhone since the original." Services brought in $31.57 billion at a 76% gross margin.
Greater China grew 21%. Apple also bought back $24 billion of its own stock in the quarter. Management guided December-quarter revenue growth to between 7% and 10%. If Siri AI drives faster upgrade cycles, our bull case points to $402.21.
Gross margin was 47.9% in the September quarter, and Apple guided it down to between 45% and 46% for December. The chief executive described memory pricing as "unprecedented."
Operating expenses rose 21%, and inventories climbed to $14.54 billion from $5.72 billion. Building inventory protects supply during the holiday quarter, and the jump in R&D to $11.73 billion funds AI features that could drive future upgrades. Still, the consensus analyst target sits below where the stock trades. Our bear case is $328.28.
Microsoft (NASDAQ:MSFT) is the closest mega-cap comparison on quality. Its P/E is 30 and quarterly revenue grew 18.8%. However, Microsoft spent $115.9 billion on capex in fiscal 2026, while Apple spent $9.04 billion.
Alphabet (NASDAQ:GOOGL) competes with Apple on AI assistants and trades at a P/E of 13. Its free cash flow came in at -$9.065 billion last quarter because of heavy AI spending.
On earnings multiples alone, the peer group makes our target look aggressive. Apple's light capex needs and steady buybacks are the reasons I consider the target reasonable anyway.
The 24/7 Wall St. price target of $384.73 carries a buy rating with 70% confidence. What tips the balance for me is capital efficiency.
I'd stay positive if iPhone Duo supply catches up with demand and gross margin holds within guidance. I'd be more cautious if memory costs push margins below the guided range.
Apple would need to keep executing on its current strategy for these estimates to hold. Results could land well above or below them depending on how fast Siri AI is adopted and how long memory costs stay high.
If you've saved over $1,000,000, this guide is for you. The last thing you want in retirement is to run out of money, you want your money to generate lasting income while you enjoy your life.
Now you can learn the strategies wealthy retirees use to fund their retirement with The Definitive Guide to Retirement Income from Fisher Investments. Download the guide today! (sponsor)
Contact editorial@247wallst.com for any questions or corrections.