Pfizer (PFE) Stock Looks Attractive for Income Investors TipRanks Thu, November 5, 2026 at 4:32 PM EST 5 min read PFE -3.05% LLY -3.83% ^GSPC -4.36% IYH -2.83% JNJ -1.47% Explore stocks on Coinbase Trading disclosure Trading disclosure The above button links to Coinbase. Yahoo Finance is not a broker-dealer or investment adviser and does not offer securities or cryptocurrencies for sale or facilitate trading. Coinbase pays us for certain activity generated through this link. Prices displayed are informational.
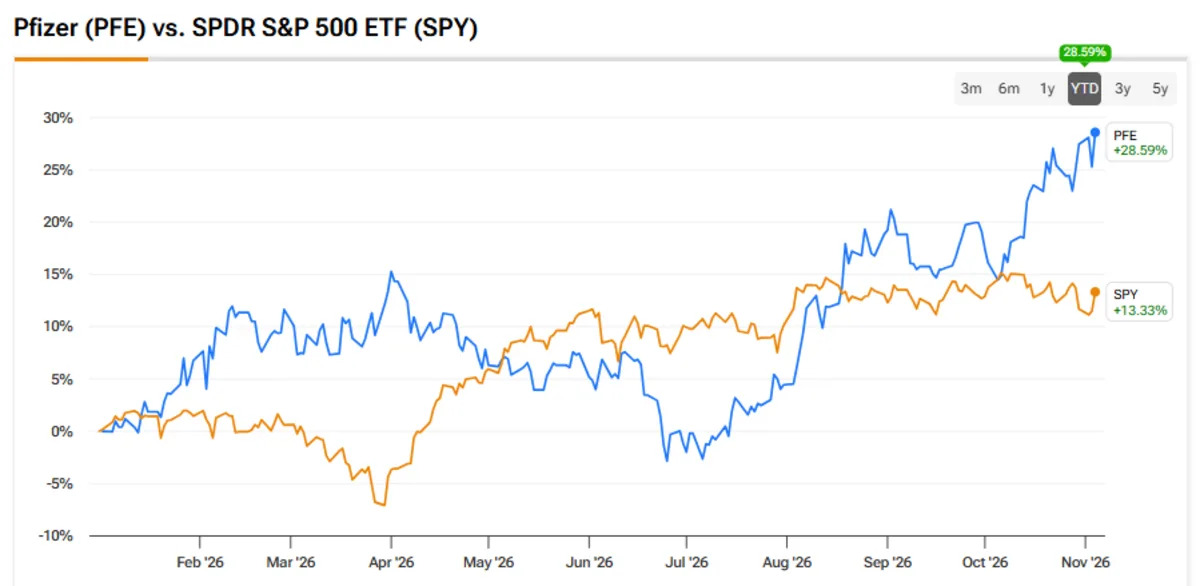
Pfizer (PFE) stock looks attractive for income investors because of its well-covered dividend and modest valuation. The drug maker's shares have outperformed the S&P 500 (SPX) in 2026, mirroring the strong performance of the healthcare sector as tracked by the iShares U.S. Healthcare ETF (IYH). While broader sector gains are largely driven by growth investors looking to diversify away from the artificial intelligence (AI) theme in stocks such as Eli Lilly (LLY), Pfizer's investment case is somewhat unique.
No doubt, Pfizer reported weaker revenues in Q3 2026, and its adjusted earnings per share (EPS) remain flat relative to the prior-year quarter. However, the shares offer a well-covered dividend of $1.72 per share per year. What is more, they trade at only 10.58x expected 2027 EPS of $2.91.
As such, my Buy rating on Pfizer is driven by a discounted income play in the short term, potentially transforming into a growth investment opportunity if the company's expectations for a turnaround in sales after 2028 prove correct.
Unlock powerful investing tools with TipRanks Premium to make smarter, more confident investment decisions
Pfizer reported a marginal 0.4% year-over-year revenue decline to $16.6 billion, impacted by weak demand for COVID-19 treatments and patent expirations. Against this weak top-line result, adjusted EPS of $0.87 was unchanged relative to the prior-year quarter. This was actually a beat as analysts were expecting a weaker earnings print.
Despite unfavorable year-over-year comparisons, results beat the company's expectations. This prompted Pfizer to raise its full-year revenue guidance to $62–$64 billion, from the previous guidance of $60.5–$62.5 billion. The revised guidance implies a modest 0.6% increase relative to 2025 revenues of $62.6 billion.
For earnings, Pfizer's 2026 forecast now reflects adjusted EPS of $2.95–$3.05. Using the midpoint, this is still about a 7% decline from the $3.22 EPS achieved in 2025. The silver lining is that weaker profitability reflects higher research and development spending, which should support Pfizer earnings over the medium to long term.
I believe the takeaway for investors is that Pfizer is still struggling to grow revenue and earnings, making the shares primarily appealing to income-focused investors in the short term. Case in point, Pfizer made no share repurchases in 2026, allowing the company to maintain a $0.43 per share quarterly dividend.
Relative to the adjusted EPS forecast for 2026, we see that Pfizer's annual dividend of $1.72 per share represents a payout of about 57%. I think this makes the dividend quite safe and reinforces my Buy rating on PFE.
Looking ahead to 2027, we see that analysts expect Pfizer to deliver revenues of about $60 billion, indicating that the top-line pressures observed in Q3 2026 will carry into next year. The same applies to earnings, with consensus EPS estimates standing at about $2.91, pointing to a single-digit decline next year.
Pfizer is keen to highlight that while patent expirations will weigh on near-term growth, the outlook after 2028 remains bright. Growth in Launched and Acquired Products, a category that includes recently launched and acquired products, including new indications, grew 32% year-over-year. As such, the company is able to successfully launch new medicines, supporting a Buy rating on the shares for investors with a medium-to-long-term outlook.
I believe that once the effects of patent expirations are in the rearview mirror, Pfizer's valuation should move closer to that of large-cap U.S. peers, as I will discuss in the next section.
Pfizer trades at 10.58x expected 2027 EPS of about $2.91, notably cheaper than peers such as Eli Lilly and Johnson & Johnson (JNJ). For example, Eli Lilly trades at a 28.27x multiple to its expected 2027 EPS of $50.15, while Johnson & Johnson trades at 23.78x its expected 2027 EPS of $11.62.
The key difference between Pfizer and these two peers is that Pfizer's earnings are still falling, while Eli Lilly is projected to grow earnings by about 42% next year, with a somewhat smaller increase of about 4% penciled in for Johnson & Johnson.
I believe that the key catalyst for Pfizer shares to re-rate higher will be a turnaround in the company's earnings momentum. While the timing of such a turnaround is hard to pinpoint in advance, I think it may come as early as 2029. My positive outlook is largely driven by the company's own expectations for a turnaround in sales, although I should caution that higher revenues may not automatically translate into higher earnings per share.
In a nutshell, my Buy rating on Pfizer is driven by a well-covered dividend in the short term and the prospect of higher earnings in the medium-to-long term. Indeed, with an increased focus on longevity and well-being, healthcare stocks will likely continue to do well, although I do admit that the sector is not as cheap following its strong performance in 2026.
On Wall Street, Pfizer has a Moderate Buy consensus rating, based on seven Buy, 14 Hold, and one Sell ratings over the past three months. The average Pfizer price target is currently $30.26, implying roughly 2% downside over the next 12 months.
Pfizer shares have done well in 2026 even as the company is struggling to achieve meaningful revenue and earnings growth. As such, I believe the broader healthcare sector's strong performance has boosted Pfizer stock.
In the near term, I see no quick turnaround for Pfizer's operating performance, as patent expirations continue to weigh on sales and earnings. Against this backdrop, Pfizer's well-covered dividend remains a key appeal for the investment case.
Over the medium to long term, I expect Pfizer to return to top-line growth. This in turn should support an acceleration in earnings, allowing Pfizer shares to re-rate closer to valuations of large peers such as Eli Lilly and Johnson & Johnson.
While the stock offers limited capital-gain potential, I think its income appeal remains quite strong, ultimately resulting in an acceptable total return in the near term until revenues return to growth after 2028.