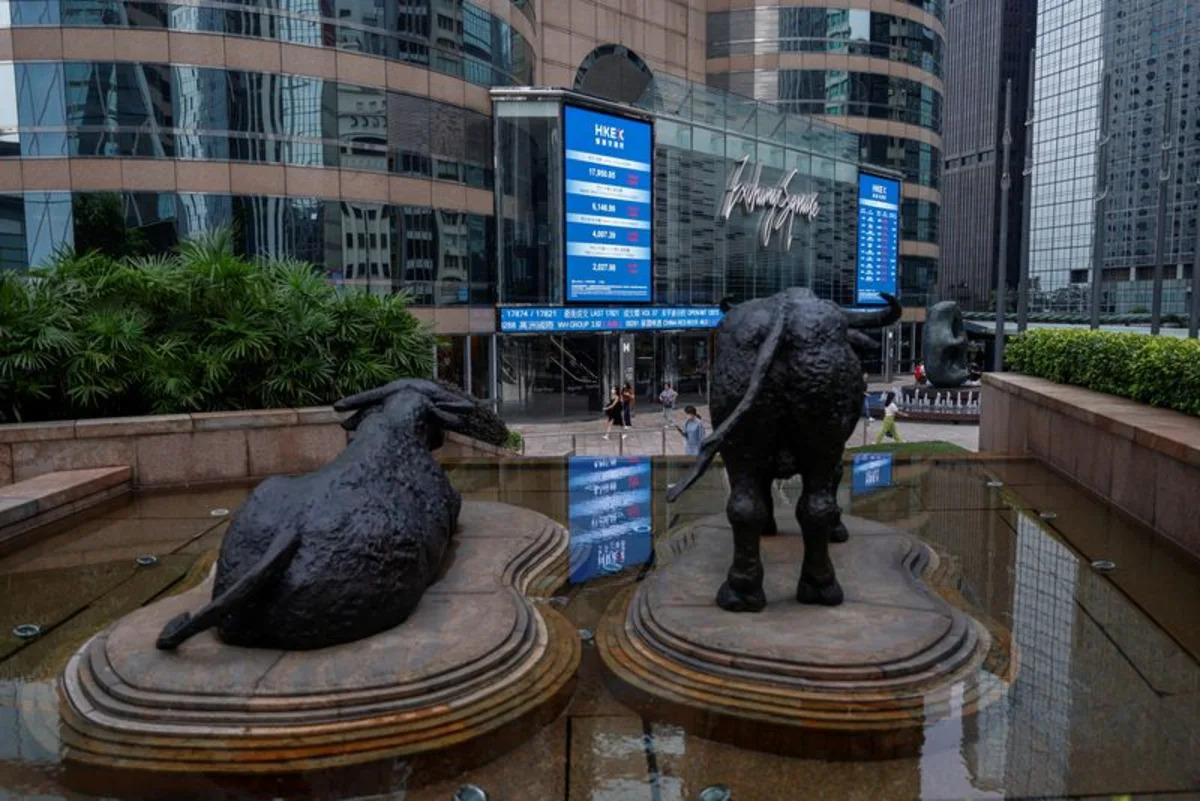
European stocks flat, oil drops as midterm caution prevails FILE PHOTO: Bull statues are placed in font of screens showing the Hang Seng stock index and stock prices outside Exchange Square, in Hong Kong, China, August 18, 2023. REUTERS/Tyrone Siu/File Photo · Reuters By Stefano Rebaudo and Wayne Cole Mon, November 2, 2026 at 4:14 AM EST 3 min read ^GSPC -1.82% ^IXIC -2.86% ^STOXX +0.16% AAPL -1.23% CL=F -4.34% Trade Apple on Coinbase Trading disclosure Trading disclosure The above button links to Coinbase. Yahoo Finance is not a broker-dealer or investment adviser and does not offer securities or cryptocurrencies for sale or facilitate trading. Coinbase pays us for certain activity generated through this link. Prices displayed are informational.
Nov 2 (Reuters) - European stocks struggled for direction on Monday after Friday's tech rout, with investors looking ahead to Apple's earnings and taking comfort from a sharp fall in oil prices amid hopes for a deal to end the Iran war.
Markets face a pivotal week, with investors still digesting the Federal Reserve's and the European Central Bank's latest policy decisions, earnings season in full swing and the US midterm elections on Tuesday.
Euro zone government bond yields were little changed after last week's rally, but investor sentiment remained fragile amid concerns over France's fiscal outlook and continuing street unrest.
MSCI's main world stocks index was roughly unchanged, while Europe's STOXX 600 .STOXX was up 0.05%, with tech stocks rising 0.40%.
Nasdaq futures climbed 0.76% and S&P 500 futures increased 0.34%. The S&P 500 index fell 1.82% on Friday, while the Nasdaq tumbled 2.86%.
Japan's Nikkei .N225 dropped 0.33%, while South Korea's added 2.24%, having shed 16% last month.
Investors remain cautious ahead of the US vote, with European stock markets facing a different set of challenges from their US counterparts.
"Further expected downside for the Euro area PMI is a drag on our Stoxx 600 forecast trajectory," wrote Sebastian Raedler, head of European equity strategy at BofA.
"However, the main reason for our caution on European equities is the risk of disappointment in the AI capex cycle as AI models commoditise and competitive moats prove limited."
Investors expect US equities to come under pressure in the event of a Democratic sweep, as markets price in the risk of higher corporate taxes and tighter AI regulation.
Opinion polls suggest Democrats are favoured to win the House, while the Senate remains too close to call, leaving the party well short of a veto-proof two-thirds majority.
Apple has been an oasis of relative calm given it does not spend billions on data centres, and its shares have climbed for four straight months, helping it overtake Nvidia as the world's most valuable listed company.
Goldman Sachs analysts expect capital spending by hyperscalers to nearly double to $800 billion this year and rise further to $1.2 trillion in 2027. At the same time, they see S&P 500 earnings per share growth slowing to 18% next year from nearly 30% in 2026.
"Earnings results have underscored the fundamental challenge facing equity investors," wrote Ben Snider, Goldman's chief US equity strategist, in a note.
In foreign exchange markets, major currencies were largely subdued. The euro rose 0.37% to $1.1199, while the dollar was barely changed at 157.72 yen.
Rising oil prices tend to hurt the euro and yen as they worsen the outlook for energy-importing economies.
Investors are also questioning the dollar's safe-haven status, concerned that a renewed tech-driven market selloff could weaken the US currency.
George Saravelos, global head of forex strategy at Deutsche Bank, said the US's reliance on foreign equity inflows was historically unprecedented and evidence showed that when the source of an equity shock is US-centric the dollar-equity correlation flips to positive.
Among central banks meeting this week, markets are pricing in rate increases from the Reserve Bank of Australia, Bank of England and Riksbank, while the Norges Bank is seen on hold.
Data due this week include the US ISM manufacturing survey for October later on Monday and the closely watched non-farm payrolls report on Friday.
(Reporting by Stefano Rebaudo and Wayne Cole. Editing by Muralikumar Anantharaman and Mark Potter)