Daniel Foelber, The Motley Fool Fri, October 16, 2026 at 9:50 AM EDT 6 min read ASML +1.28% NVDA -0.33% Explore stocks on Coinbase Trading disclosure Trading disclosure The above button links to Coinbase. Yahoo Finance is not a broker-dealer or investment adviser and does not offer securities or cryptocurrencies for sale or facilitate trading. Coinbase pays us for certain activity generated through this link. Prices displayed are informational.
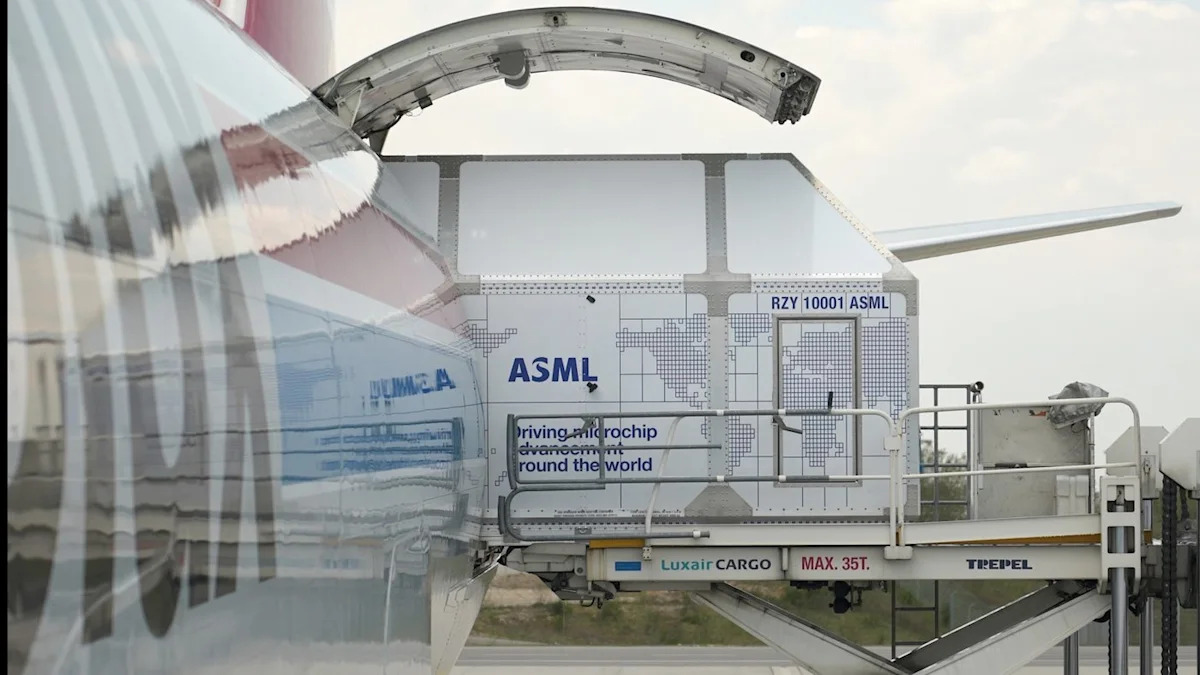
ASML (NASDAQ: ASML) reported excellent third-quarter 2026 results on Oct. 14. The semiconductor equipment maker raked in a record 11.7 billion euros in revenue, which was the high end of its guidance. ASML's gross margins came in at a whopping 57.5% -- above guidance.
Management stated that customers are already looking to place orders in 2029 and 2030 to fulfill their short- and medium-term equipment demand forecasts. Here's why that's great news for ASML, and why ASML is arguably the best artificial intelligence (AI) growth stock for long-term investors to buy now.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
There are three main parts of ASML's business -- extreme ultraviolet (EUV) machines, deep ultraviolet (DUV) and non-EUV machines, and servicing its installed base.
DUV systems are mainly used for general-purpose chip manufacturing. They can be used for AI chip manufacturing through a process called multiple patterning, but that's less efficient than EUV machines, which use far shorter wavelengths of light to print ultra-precise designs on microchips. The high numerical aperture (High-NA) EUV machine -- the most advanced lithography system in the world -- can cost up to $400 million. But ASML is only shipping around one unit a quarter as it gradually scales production of this relatively new technology, purpose-built for commercial-scale production of next-generation AI chips.
When ASML reported second-quarter results in July, the company forecast a 30% increase in Low-NA EUV production capacity in 2027 and possibly by 2028, as well as a 30% increase in DUV immersion capacity in 2027 and another 30% increase in 2028.
CEO Christophe Fouquet said the following in ASML's Oct. 14 earnings release:
With such strong visibility and an order book momentum that continues to increase quarter on quarter this year, we now expect that our supply as currently planned for both 2027 and 2028 will not fully meet the demand of our customers. Given this, we are investigating ways to increase capacity for 2028 beyond the 30% increase we previously communicated. In addition, we continue to provide significant wafer capacity to our customers through our productivity upgrade portfolio.
So in just six months, ASML's visibility shifted from probably needing to ramp production capacity through 2028 to stating that even a 30% jump could be insufficient. That sends a clear signal to investors that ASML can't keep up with order volumes, which should give it even more pricing power.
ASML's market positioning gives it significant pricing power as foundries build new AI factories and upgrade their equipment to handle AI chip production demands.
ASML is now forecasting total net sales of 44 billion to 45 billion euros in 2026, with gross margin around 56%.
As you can see in the table, ASML's sales growth is accelerating, but its gross margins have also jumped significantly. The semiconductor company's margins are high because demand is outpacing supply. But another big driver of margins is that ASML spent over a decade pouring research and development (R&D) resources into cracking the code on High-NA EUV technology. ASML still spends a significant amount on R&D to maintain its industry leadership, but much of the legwork for the current EUV runway has already been completed.
In the fourth quarter of 2026, ASML is guiding for net sales of 14.2 billion to 15.2 billion euros, 57% gross margins, R&D costs of 1.2 billion euros, and sales, general, and administrative expenses of 400 million euros. ASML is an incredibly efficient company because its R&D budget is reasonable and it doesn't have to advertise its products because customers are already lining up out the door.
Both Low-NA and High-NA EUV systems still only make up 35% of total sales, given the size of ASML's DUV business and its revenue from services to its existing installed base. In 2026, ASML expects 36% year-over-year sales growth, but the EUV business is expected to grow 45%, non-EUV by 20%, and installed base management sales are forecasted to jump by 50%. During the Oct. 14 earnings call, ASML attributed higher EUV sales and services to its installed base as key drivers of higher gross margins. The more expensive EUV machines are significantly higher-margin than DUV, while services revenue from existing units provides high-margin cash flows for ASML regardless of the ebbs and flows of customer spending on new lithography systems.
ASML is one of the best AI stocks for long-term investors to buy now, given its dominant position in EUV lithography systems. ASML's margins should remain high due to a combination of insatiable demand for AI chip manufacturing, ASML's low operating costs, and relatively low R&D expenses -- which frees up capital to invest in capacity expansions without straining ASML's cash flows.
ASML is only scratching the surface of High-NA EUV sales. Recent partnerships with companies like Taiwan Semiconductor Manufacturing aim to make these systems even more efficient for advanced node manufacturing by 2033.
Add it all up, and ASML remains the best AI stock for investors looking for a catch-all way to bet on increasing volume and complexity of AI chip production.
Most investors think they missed the AI boat because they didn't buy Nvidia in 2005.
But according to our analysts, we're only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout, a massive technology build-out that Google's CEO says could be more profound than fire or electricity.
While everyone watches the chip designers, one "backbone" company provides the critical technology that Nvidia and AMD literally cannot function without. We've detailed this under-the-radar player in our new AI Playbook.
Daniel Foelber has positions in ASML. The Motley Fool has positions in and recommends ASML and Taiwan Semiconductor Manufacturing. The Motley Fool has a disclosure policy.
ASML Can't Keep Up With 2027 or 2028 Demand. Is It the Best AI Stock to Buy Now? was originally published by The Motley Fool