AAPL -0.28% NVDA -1.84% Explore stocks on Coinbase Trading disclosure Trading disclosure The above button links to Coinbase. Yahoo Finance is not a broker-dealer or investment adviser and does not offer securities or cryptocurrencies for sale or facilitate trading. Coinbase pays us for certain activity generated through this link. Prices displayed are informational.
Blue chip stocks are among the world's more reliable moneymakers. They're the industry giants, the powerhouse players, and the stocks you're supposed to count on.
But that's not always the case. In fact, many of the world's top companies have faltered at some point, but the best ones make it back to the top; that's why they're reliable.
Missed AI's "Act 1"? Act 2 Could Be 14x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our analysts, we're only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »
Consider Apple, which was the most valuable company in the world for years until it recently got pushed into second place by Nvidia. It has lost an extreme amount of its value several times in its history, both during market sell-offs and due to internal issues. It lost more than 40% of its value in less than a year between 2012 and 2013, for example, when iPhone demand was sluggish, impacting sales and profits. However, it was trading at a price-to-earnings (P/E) ratio of less than 10, and investors who spotted the bargain were rewarded quickly; it gained 56% within one year, as demand shifted.
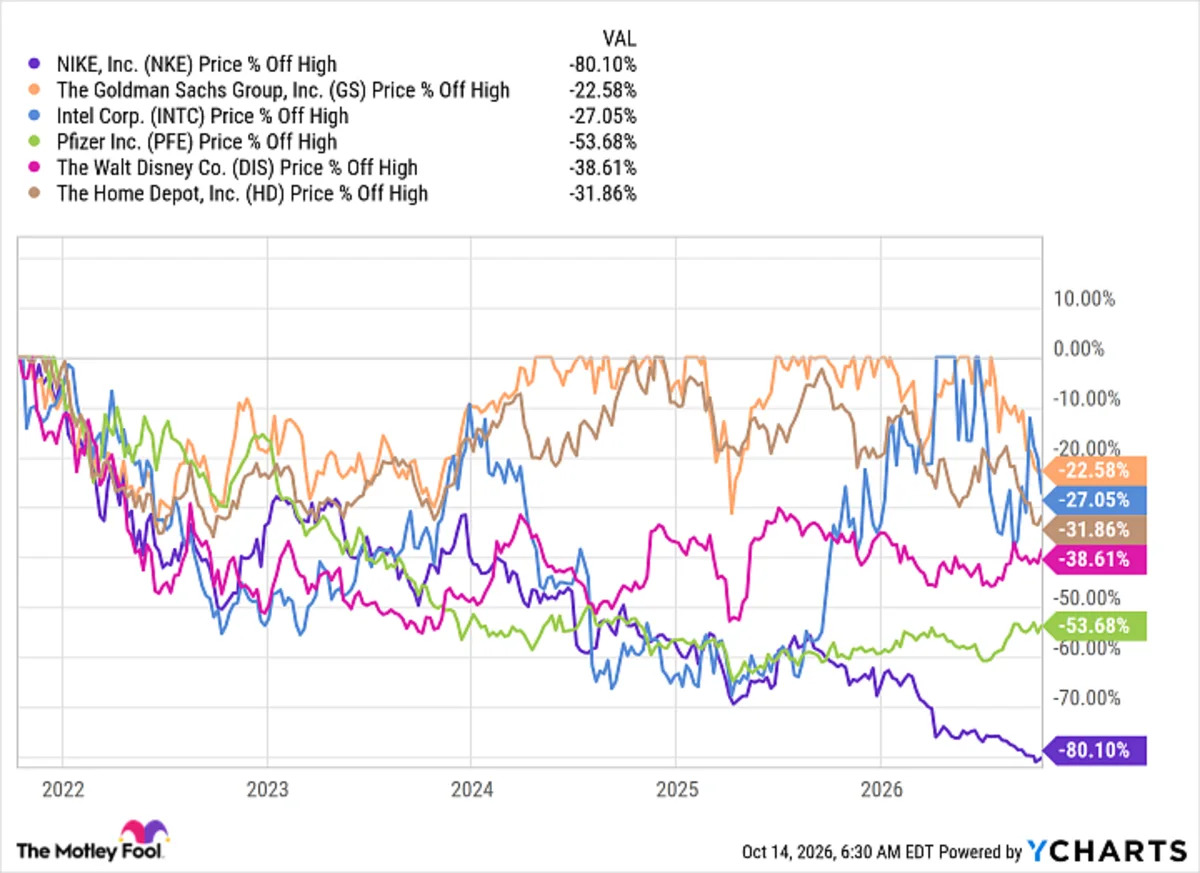
Every company goes through ups and downs. Today, despite the strong bull market and 14% gain for the S&P 500 year to date, Nike (NYSE: NKE), Goldman Sachs (NYSE: GS), Intel (NASDAQ: INTC), Disney (NYSE: DIS), Pfizer (NYSE: PFE), and Home Depot (NYSE: HD) are all at least 20% off their all-time highs. Here's whether each one is a bargain or a value trap.
Nike stock has been pounded during the past few years as it loses market share to up-and-comers. Although it's still the largest athletic apparel and footwear company in the world by far, sales have been dropping for the past few years, and they decreased 4% from last year in the 2027 fiscal first quarter (ended Aug. 31).
A series of missteps brought Nike to this place. Management decided to focus on direct-to-consumer channels rather than wholesale channels, and that allowed competitors to take more space in wholesale outlets like Dick's Sporting Goods. It was also overreliant on its classic franchises and was slow to innovate in sport. Athletes looking for the best technical specifications leaned into brands like Brooks (owned by Berkshire Hathaway and Hoka (owned by Deckers Outdoor). It's also facing major competition from local brands in China, one of its most important markets. New Chief Executive Officer Elliott Hill has made some progress in a rebound, and things are starting to look up. However, management is still forecasting a decline in sales in 2027.
Nike stock trades at a moderate 17 times trailing 12-month earnings, but in this case, it could be a value trap. Nike still has an uphill battle, and there are more compelling stories in the market.
Goldman Sachs often trades places with JPMorgan Chase as the largest investment bank in the country. It has enjoyed robust activity in the ongoing bull market, particularly this year, driven by a wave of initial public offerings (IPOs). It was one of the lead underwriters for the Space Exploration Technologies IPO, and its stock reached a high in July just after SpaceX went public. However, its stock has fallen since then on bond market volatility and concerns about increasing interest rates.
It reported strong earnings for the third quarter, beating on the top and bottom lines, driven by equities revenue rising 72% over last year and investment banking fees up 21%.
Much of its stock decline is related to overall economic sentiment rather than any internal issue. However, the stock still isn't cheap far as as financial companies go, trading at almost 13 times trailing 12-month earnings and 2.4 times book value, so it's not quite a bargain at this price.
Intel may be quite a bit off its all-time high, but it's actually up 163% this year. It has previously floundered as its technology was outdated in the artificial intelligence (AI) era, but it's come roaring back as central processing units (CPUs), the chips it makes to run computers, have become a critical component of agentic AI. Sales rose 25% year over year in the 2026 fiscal second quarter (ended June 27), and management is expecting sales to increase about 18% in the third quarter, after rising only 3% last year.
Intel stock trades at 8.8 times trailing 12-month sales, and it has been struggling with profitability during the past few years. It may continue to benefit from the AI tailwind, but I'd be wary about investing in it right now.
Pfizer is one of the leading pharmaceutical companies in the country, and it benefited from its COVID-19 vaccine a few years ago, sending the stock soaring. However, it's been under some pressure now that the vaccine isn't driving revenue anymore and is losing some of its patent protections, which eventually happens to all proprietary medications.
The good news is that revenue is starting to climb again, and it has several promising medications in the pipeline. It lost out on the race for GLP-1 weight-loss medicines, but it recently acquired Metsera, which is developing one.
At the current price, Pfizer trades at 37 times trailing 12-month earnings, given its recent quarterly net losses. However, its dividend yields more than 6%, potentially making it a great buy for long-term passive-income investors.
Disney is perhaps the most recognizable name in media and entertainment, but its stock has been dismal for years. The company has struggled with declining broadcast TV revenue, challenges in making its streaming business work, inflation-driven challenges for its parks segment, and a few box-office bombs.
At the current price, it trades at a P/E ratio of 22. That's not so cheap considering its middling performance, but risk-tolerant investors could take a chance on Disney at this price as it restructures and streaming becomes profitable.
Home Depot is the largest home improvement chain in the world, and while that's usually a good thing, it hasn't been so great in the weak real estate market. Persistent inflation and high interest rates are making it hard for people to buy new homes and complete home renovations. Even though Home Depot is managing fairly well, market sentiment remains very negative, especially now that interest rates are likely to be raised further.
Home Depot stock trades at a P/E ratio of 21, just below its 10-year average, so it's not quite a bargain. However, it's producing comparable sales increases despite the tough environment, which is why it could be worth the price. Its dividend is also yielding a higher-than-average rate of 3.2%. The stock may not recover for a while, but Home Depot is a forever stock for long-term passive income investors.
Before you buy stock in Goldman Sachs Group, consider this:
The Motley Fool Stock Advisor analyst team just identified what they believe are the 10 best stocks for investors to buy now… and Goldman Sachs Group wasn't one of them. The 10 stocks that made the cut could produce monster returns in the coming years.
Consider when Netflix made this list on December 17, 2004... if you invested $1,000 at the time of our recommendation, you'd have $380,579!* Or when Nvidia made this list on April 15, 2005... if you invested $1,000 at the time of our recommendation, you'd have $1,359,789!*
Now, it's worth noting Stock Advisor's total average return is 931% — a market-crushing outperformance compared to 212% for the S&P 500. Don't miss the latest top 10 list, available with Stock Advisor, and join an investing community built by individual investors for individual investors.
*Stock Advisor returns as of October 16, 2026.
JPMorgan Chase is an advertising partner of Motley Fool Money. Jennifer Saibil has positions in Apple. The Motley Fool has positions in and recommends Apple, Berkshire Hathaway, Deckers Outdoor, Goldman Sachs Group, Home Depot, Intel, JPMorgan Chase, Nike, Nvidia, Pfizer, and Walt Disney. The Motley Fool has a disclosure policy.
6 Blue Chip Stocks Trading Well Below Their Highs was originally published by The Motley Fool