
3 Reasons to Avoid VAL and 1 Stock to Buy Instead Jabin Bastian Tue, October 13, 2026 at 10:27 AM EDT 3 min read ^GSPC -0.06% VAL +0.72% Trade Valaris on Coinbase Trading disclosure Trading disclosure The above button links to Coinbase. Yahoo Finance is not a broker-dealer or investment adviser and does not offer securities or cryptocurrencies for sale or facilitate trading. Coinbase pays us for certain activity generated through this link. Prices displayed are informational.
Over the past six months, Valaris's shares (currently trading at $84.73) have posted a disappointing 14.5% loss, well below the S&P 500's 13.5% gain. This may have investors wondering how to approach the situation.
Despite the more favorable entry price, we're cautious about Valaris. Here are three reasons why VAL doesn't excite us, plus one stock we'd rather own.
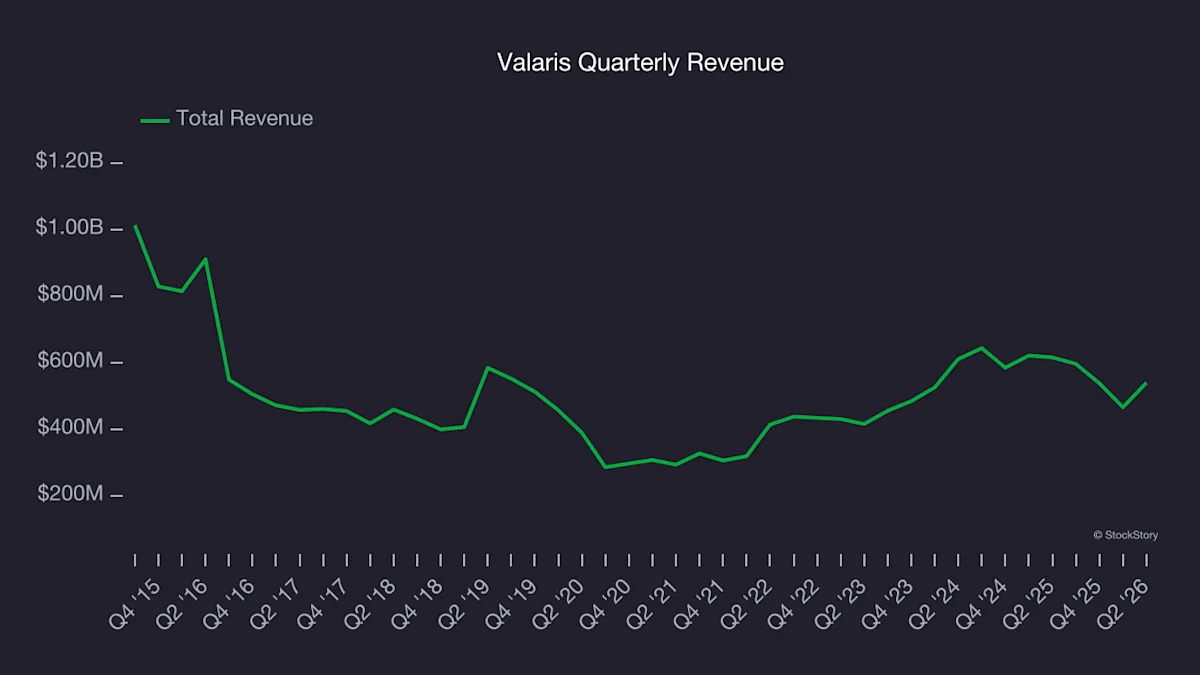
Cyclical sectors like Energy often flatter weaker operators during favorable price environments, but a longer-term lens separates those from businesses that can consistently perform across market cycles. Over the last five years, Valaris grew its sales at a decent 12.6% compounded annual growth rate. Its growth was slightly above the average energy upstream and integrated energy company and shows its offerings resonate with customers.
In a single quarter or year, gross margins in the sector can swing wildly due to commodity prices, hedging, or changes in labor costs. Over a multi-year period across different points in the cycle, gross margin differences can signal whether a company is a structurally-advantaged producer ("rock" quality, takeaway, operating costs) or not.
Valaris, which averaged 21.5% gross margin over the last five years, exhibited bottom-tier unit economics in the sector. It means the company will struggle at higher commodity prices than peers with better gross margins.
Free cash flow isn't a prominently featured metric in company financials and earnings releases, but we think it's telling because it accounts for all operating and capital expenses, making it tough to manipulate. Cash is king.
Valaris's demanding reinvestments have drained its resources over the last five years, putting it in a pinch and limiting its ability to return capital to investors. Its free cash flow margin averaged negative 5.8%, meaning it lit $5.80 of cash on fire for every $100 in revenue.
Valaris isn't a terrible business, but it isn't one of our picks. Following the recent decline, the stock trades at 13.5× forward P/E (or $84.73 per share). Beauty is in the eye of the beholder, but our analysis shows the upside isn't great compared to the potential downside. We're pretty confident there are more exciting stocks to buy at the moment. We'd suggest looking at one of our top digital advertising picks.
WHILE YOU'RE HERE: Top 9 Market-Beating Stocks. The best stocks don't just beat the market once. They do it again. And again. Robust revenue growth, rising free cash flow, returns on capital that leave their competition in the dust. The market has already rewarded these businesses.
But our AI platform says the party isn't over. Find out which 9 stocks made the cut this week — FREE. Get Our Top 9 Market-Beating Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-micro-cap company Tecnoglass (+1,552% between June 2020 and June 2025). Find your next big winner with StockStory today.
