US Stock Market Today: S&P 500 Futures Edge Higher On Hot Inflation Expectations Sasha Jovanovic Tue, October 13, 2026 at 4:12 AM EDT 8 min read ^GSPC -0.06% SHOP +4.90% CIEN -9.95% MDT +3.90% Explore stocks on Coinbase Trading disclosure Trading disclosure The above button links to Coinbase. Yahoo Finance is not a broker-dealer or investment adviser and does not offer securities or cryptocurrencies for sale or facilitate trading. Coinbase pays us for certain activity generated through this link. Prices displayed are informational.
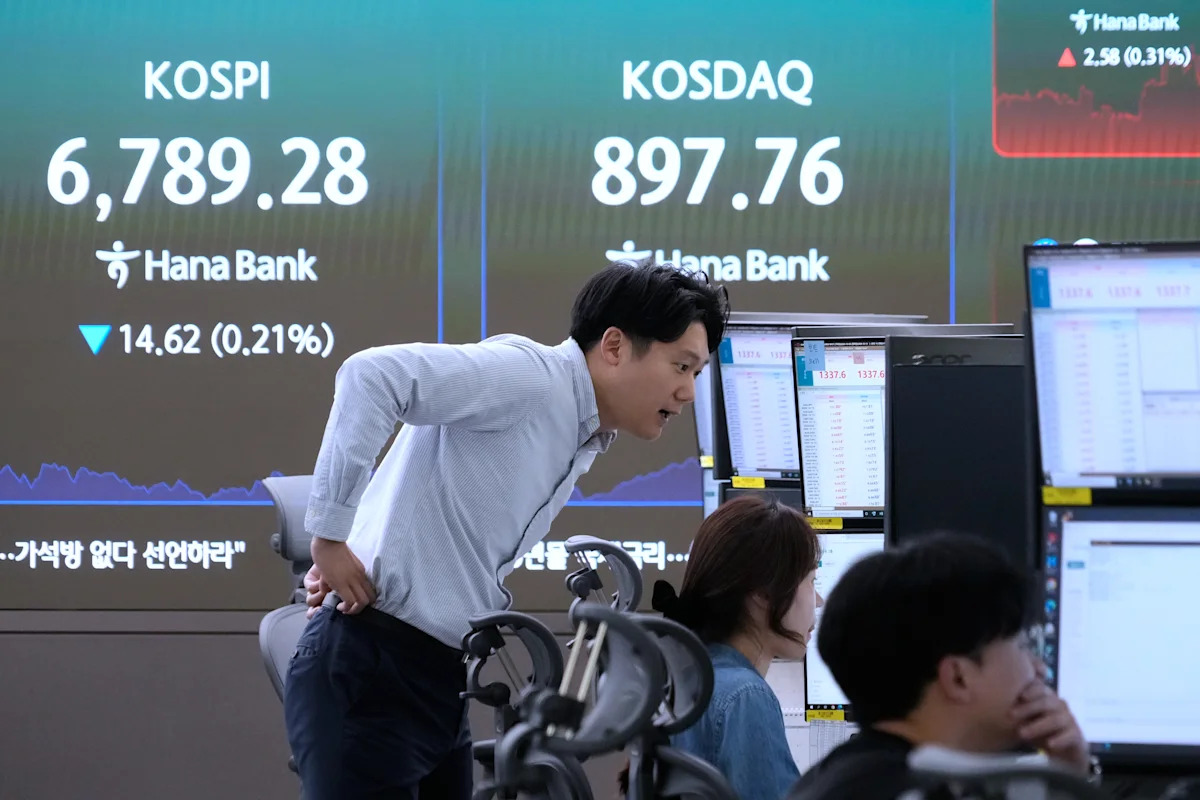
US stocks are set for a cautiously positive open, with index futures slightly higher as investors refocus on inflation. The single driver this morning is a jump in US year ahead inflation expectations, which is testing the recent calm in rates.
The latest University of Michigan survey puts year ahead inflation expectations at 4.7% in October, a five month high. That figure arrives just ahead of Wednesday's CPI release and has raised questions about how firmly price pressures are contained.
When households expect faster price gains, lenders usually demand more compensation for inflation risk. This can push Treasury yields higher and lift borrowing costs across mortgages and corporate credit. Higher funding costs can compress profit margins and pressure valuation multiples in rate sensitive parts of the equity market.
The key dilemma now is simple. If CPI and PPI confirm this pickup in inflation expectations, investors may need to reassess how long current rate expectations can hold. If the data push back instead, this early bid in equities faces a credibility check.
Character.ai has filed for voluntary Chapter 11, with Walt Disney lined up as stalking horse bidder for a non exclusive perpetual license to some of its intellectual property. Disney is also set to provide transition services. Readers will want to watch the court process and whether rival bidders emerge before the planned late November or early December closing.
Meta Platforms just introduced Muse Wonder, a closed AI model aimed at business clients, and says it outperforms rival systems. The company is pairing that push with the purchase of multiple VR patents from Sony. The mix of heavy AI investment and ongoing VR ambitions keeps capital needs in focus and raises questions about how Meta prioritizes future product spending.
PTC is under review by Halper Sadeh LLC over its planned sale to Schneider Electric for US$205.00 a share in cash. The law firm is examining possible securities law issues and fiduciary duty questions. Shareholders are being urged to explore their options, so the key watchpoint is whether this process leads to calls for a higher bid or added disclosures.
Shopify (SHOP) jumped 4.90% after multiple analysts raised price targets, citing stronger agentic commerce and AI driven demand.
Medtronic (MDT) gained 3.90% as investors reacted to updated research highlighting FY27 guidance and recent segment-wide growth trends.
Vylor (VYLR) advanced 3.75% following fresh analyst coverage and recent inclusion in major indices after its Corteva spin off.
Ciena (CIEN) declined 9.95% after investors reacted to the appointment of a new Chief People Officer and other leadership changes.
Lumentum Holdings (LITE) fell 9.78% as concerns over AI infrastructure funding pressured optical networking stocks, despite positive PCIe-over-optics developments.
Coherent (COHR) dropped 7.87% as optical networking shares weakened on worries about AI spending sustainability and data center funding constraints.
US traders are staring at a stacked stretch of inflation and spending data, plus a fresh wave of big bank and insurer earnings, all of which feed directly into rate expectations and sector positioning.
US CPI and Core CPI, Wed 14 Oct, land against forecasts of 0.5% headline and 0.2% core for September. Any upside surprise would reinforce the recent 4.7% inflation expectations print and keep pressure on Treasury yields and rate sensitive stocks.
US PPI and Core PPI, Thu 15 Oct, are projected at 0.5% and 0.3% month on month. This gives a clean read on pipeline costs and helps markets judge how durable any CPI move looks for margins in goods focused sectors.
US Retail Sales and control group, Thu 15 Oct, come with forecasts of 0.1% headline, 0.3% ex autos and 0.3% for the control group. Softer prints would echo weaker consumer sentiment and ease fears that consumption will keep inflation sticky.
US Initial Jobless Claims, Thu 15 Oct, sit against a prior 197,000 and a 200,000 consensus. A clear break higher would hint at a cooler labour market that could reduce pressure on the Federal Reserve to keep policy tight.
JPMorgan Chase (JPM), Goldman Sachs (GS), Bank of America (BAC), Citigroup (C), Wells Fargo (WFC) Q3 earnings, Tue 13 Oct, put net interest income, fee trends and cost of deposits under the microscope. This matters for how investors price the entire US banking sector into this rate backdrop.
Morgan Stanley (MS), BlackRock (BLK), State Street (STT) Q3 results, Wed 14 Oct, focus attention on asset management and market sensitive revenue lines, where shifts in flows and trading income help investors see how higher yields are feeding through to Wall Street fee pools.
Travelers Companies Q3 earnings, Fri 16 Oct, will spotlight underwriting margins and any change in catastrophe losses, giving insurance holders a concrete view of how pricing and claims trends are shaping profitability after a volatile summer for weather related events.
Energy: Fuel tightness keeps sector in focus
Energy has logged a clear 7 day gain on top of already strong year to date returns, helped by tight fuel markets and firm refining margins. Recent pieces on refiners and tanker operators underline how sensitive this group is to diesel and shipping conditions, not just crude prices.
If you hold Energy funds or producers, your returns are closely tied to oil, fuel spreads and shipping rates. The next real test is this week's US crude and gasoline inventory data, which will show whether supply is loosening or staying tight into year end.
Tech: AI headlines meet rate reality
Tech has slipped over the past week after a strong run this year, even as Microsoft, Amazon.com and others roll out new AI chips, cloud deals and agent tools. Rising inflation expectations keep upward pressure on interest rates, which often hits sectors where a lot of the story depends on profit growth many years out.
For everyday portfolios with big Tech exposure, that means more sensitivity to both bond yields and AI infrastructure spending news. Wednesday's US CPI print is the key macro catalyst here because any upside surprise would keep the rate debate front and centre for this sector.
Semiconductors: Hot year, cooler recent tone
Semiconductors show a sharp 7 day pullback after a very strong year to date climb, as traders react to talk about AI build out financing constraints and fresh competition in memory. News around Nvidia, Micron, Sandisk and custom AI chips from Microsoft keeps the focus on how much data center demand can support recent gains.
If your portfolio leans heavily into chip makers, swings are now closely tied to each update on AI capacity plans and funding. The single macro event that matters most near term is also Wednesday's US CPI, because it shapes borrowing costs for the huge data center projects these companies sell into.
Real Estate: Rate sensitive bounce after tough month
Real Estate has posted a 7 day gain after a weaker 30 day patch, which fits with how sensitive property values are to mortgage rates and bond yields. Stories around data center landlords and retail REITs show parts of the group still tied to AI infrastructure and everyday shopping even as higher borrowing costs bite.
For investors in REITs or property heavy funds, the key link is simple. Higher inflation expectations can feed into higher long term yields, which affects both property values and refinancing costs. This week's US CPI and the 30 year mortgage rate update will be the clearest signals to watch.
Consumer Staples: Defensive demand holds interest
Consumer Staples has delivered a solid 7 day gain and positive year to date return, as investors look for steadier areas while consumer sentiment weakens. Legal headlines around Kroger and Albertsons and new health and wellness pushes from large brands show how this group depends more on everyday spending than on big financed purchases.
If you use Staples as a stabiliser in your portfolio, it still pays to watch inflation because food and household prices directly affect both shoppers and producer margins. Thursday's US Retail Sales report is the key check, since it shows whether volumes and baskets are holding up as households report feeling more pressured.
With Consumer Staples showing a steady 7 day gain as investors look for more defensive exposure, you can stress test that idea against this list of 31 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com