America’s housing affordability crisis could drag on for at least another five years — and for New Yorkers, the wait could stretch well beyond a decade.
Housing costs nationwide could return to their 2018 levels relative to household income by 2031, according to a new Redfin analysis — but buyers in New York City, Long Island and roughly half of the major metropolitan areas studied could face another decade of financial pain.
That optimistic national scenario assumes mortgage rates fall to 6% while annual home-price growth holds steady at 2.1%.
If rates remain around 7.5% but home prices stop rising, affordability could recover by April 2032 instead.
And in an even rosier — though unlikely — scenario, where rates drop to 6% and prices flatten, housing costs could return to their pre-pandemic benchmark by February 2029.
But the picture is considerably bleaker in the Northeast and Midwest, where stubbornly rising home prices continue to outpace wage growth.
Long Island is feeling the squeeze particularly hard.
Nassau County, ranked the nation’s strongest seller’s market by Redfin, has seen home prices climb 5.3% over the past year, outpacing projected annual income growth of 3.6%.
That’s a 1.7-percentage-point gap between home-price appreciation and expected income gains, leaving prospective buyers struggling to keep up in an already fiercely competitive market — even if mortgage rates fall to 6%.
That imbalance means affordability could take at least 10 years to return to 2018 levels, even if mortgage rates fall to 6%.
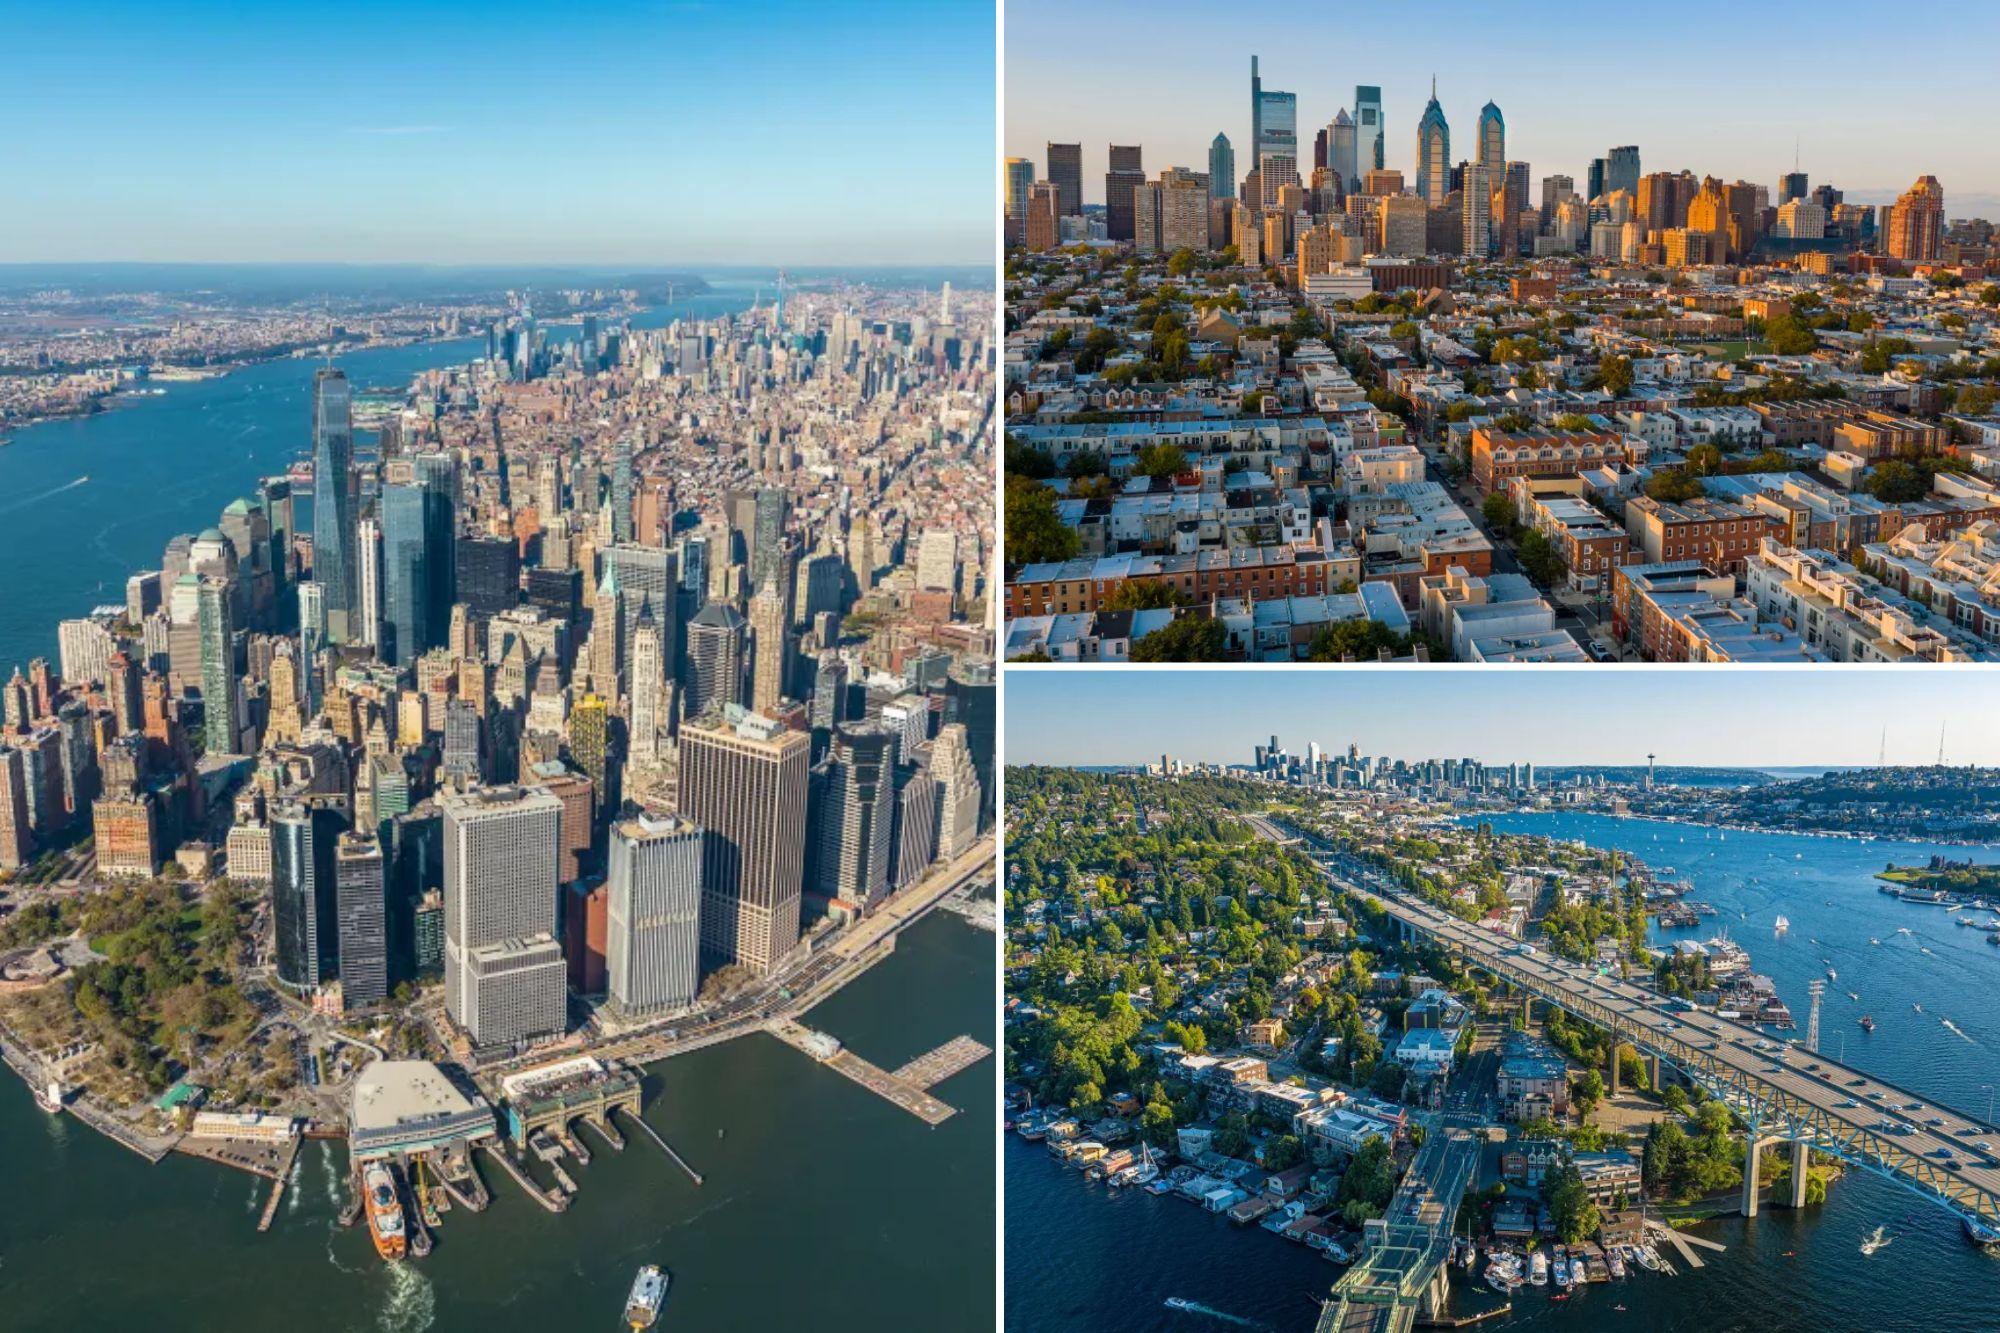
New York City, Newark, New Brunswick and Philadelphia face similarly lengthy recoveries, along with Chicago, Boston and several other major markets.
Chicago home prices, for example, have surged 5.5% year over year, compared with projected annual income growth of 3.9%.
“It may seem counterintuitive that housing costs could return to normal sooner in the country’s most expensive markets than in a place like Chicago or Philly, but it comes down to the direction of home prices and incomes,” Redfin senior economist Asad Khan said in the company’s published analysis.
Redfin defines “normal” as a return to August 2018, when the typical American homebuyer needed to spend about 30% of household income on monthly housing payments, including mortgage principal and interest, property taxes and insurance, assuming a 20% down payment.
“But in many Midwest and East Coast markets, home prices are still climbing faster than incomes — so even if rates were to drop meaningfully, a buyer’s monthly payment wouldn’t return to something that feels normal anytime soon,” he added in the report.
Ironically, some of America’s notoriously expensive West Coast markets could recover much faster.
San Jose, California, is closest to returning to its 2018 affordability levels, thanks to a 3.2% annual decline in home prices and projected wage growth of 6.5%.
Under a scenario with mortgage rates at 7.5%, San Jose could return to its previous benchmark by October 2027.
Austin, Texas, could follow in February 2028, while Oakland could reach that point by April 2028. Seattle and Portland are also among the markets positioned for relatively quick recoveries.
San Francisco presents an unusual case. Its housing costs briefly returned to 2018 levels when mortgage rates were around 7.25% in September, but soaring home prices — up 9.7% annually amid an AI-fueled wealth boom — threaten to push affordability further out of reach.
At 7.5% mortgage rates, San Francisco could face another decade before costs normalize.
Crucially, that doesn’t mean homes would suddenly become cheap. In expensive markets such as San Jose and San Francisco, returning to 2018 affordability levels could still leave homeownership beyond the reach of many residents.
The analysis examined 46 major metropolitan areas and modeled different combinations of mortgage rates, home-price growth and projected income gains.
And while the scenarios offer some hope for frustrated house hunters, they are hypothetical projections rather than forecasts of what will actually happen.
“Many house hunters feel stuck between two bad options: Stretch themselves to buy at today’s rates, or wait for lower rates only to see prices climb further out of reach,” Khan said in the published report.