3 Reasons Investors Love Diamondback Energy (FANG) Anthony Lee Mon, October 12, 2026 at 12:23 PM EDT 3 min read FANG +2.38% ^GSPC -0.10% Trade FANG on Coinbase Trading disclosure Trading disclosure The above button links to Coinbase. Yahoo Finance is not a broker-dealer or investment adviser and does not offer securities or cryptocurrencies for sale or facilitate trading. Coinbase pays us for certain activity generated through this link. Prices displayed are informational.
Diamondback Energy has been treading water for the past six months, recording a small return of 1.8% while holding steady at $192.41. The stock also fell short of the S&P 500's 12.8% gain during that period.
Given the weaker price action, is now a good time to buy FANG? Or should investors expect a bumpy road ahead? Find out in our full research report, it's free.
Sporting one of Wall Street's most memorable ticker symbols, Diamondback Energy (NASDAQ:FANG) drills for and produces oil and natural gas from underground rock formations in the Permian Basin of West Texas and New Mexico.
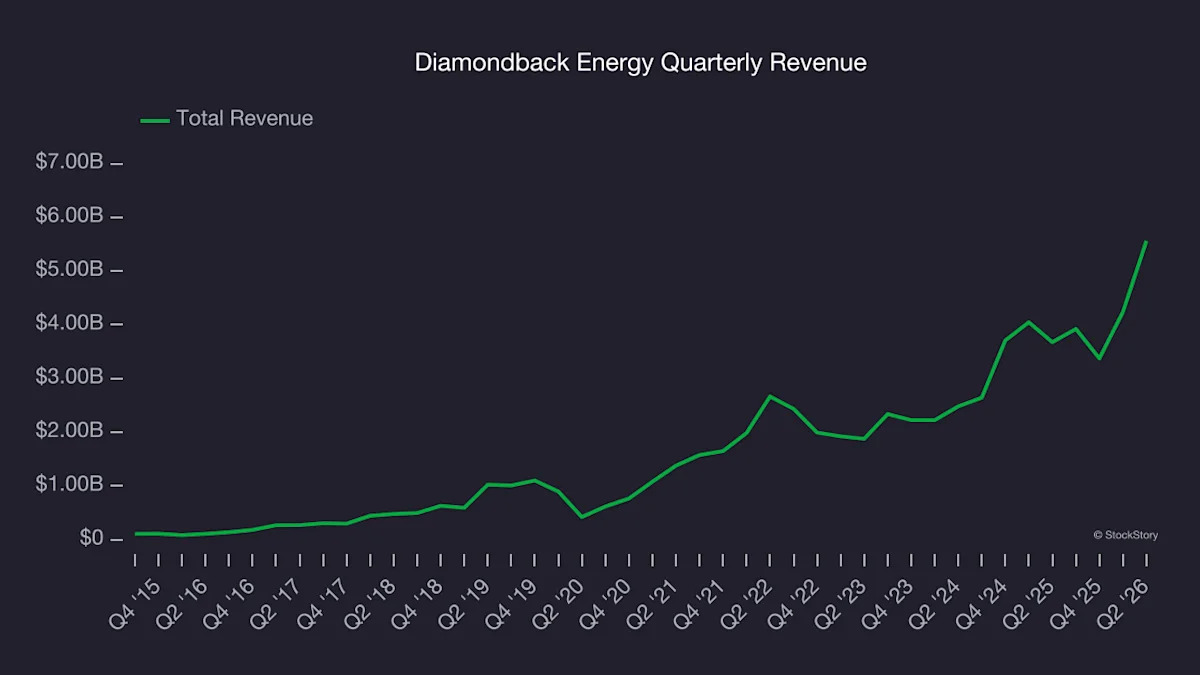
Cyclical industries such as Energy can make mediocre companies look great for a time, but a long-term view reveals which businesses can actually withstand and adapt to changing conditions. Thankfully, Diamondback Energy's 34.7% annualized revenue growth over the last five years was incredible. Its growth beat the average energy upstream and integrated energy company and shows its offerings resonate with customers.
In a single quarter or year, gross margins in the sector can swing wildly due to commodity prices, hedging, or changes in labor costs. Over a multi-year period across different points in the cycle, gross margin differences can signal whether a company is a structurally-advantaged producer ("rock" quality, takeaway, operating costs) or not.
Diamondback Energy, which averaged 79.8% gross margin over the last five years, exhibits enviable unit economics in the sector. It means the company will remain profitable at lower commodity prices than peers with inferior gross margins and serves as an advantaged starting point for ultimate operating profits and free cash flow generation.
Free cash flow isn't a prominently featured metric in company financials and earnings releases, but we think it's telling because it accounts for all operating and capital expenses, making it tough to manipulate. Cash is king.
Diamondback Energy has shown terrific cash profitability, driven by its lucrative business model that enables it to reinvest, return capital to investors, and stay ahead of the competition. The company's free cash flow margin was among the best in the energy upstream and integrated energy sector, averaging an eye-popping 37.8% over the last five years.
These are just a few reasons why Diamondback Energy is one of the best energy upstream and integrated energy companies out there. With its shares underperforming the market lately, the stock trades at 9.9× forward P/E (or $192.41 per share). Is now the right time to buy? See for yourself in our in-depth research report, it's free.
ONE MORE THING: Top 5 Growth Stocks. The biggest stock winners almost always had one thing in common before they ran. Revenue growing like crazy. Meta. CrowdStrike. Broadcom. Our AI flagged all three. They returned 315%, 314%, and 455%, respectively.
Find out which 5 stocks it's flagging this month — FREE. Get Our Top 5 Growth Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-micro-cap company Kadant (+214% between June 2020 and June 2025). Find your next big winner with StockStory today.