Synopsys (SNPS): The Next Big AI Stock Breakout? Ethan Feller Thu, October 8, 2026 at 12:58 PM EDT 5 min read SNPS -0.40% AMZN -2.07% OPAI.PVT Explore stocks on Coinbase Trading disclosure Trading disclosure The above button links to Coinbase. Yahoo Finance is not a broker-dealer or investment adviser and does not offer securities or cryptocurrencies for sale or facilitate trading. Coinbase pays us for certain activity generated through this link. Prices displayed are informational.
Identifying the next big AI winners has become increasingly challenging. The theme is maturing, and much of the extraordinary growth across the industry is already reflected in stock prices. However, I think I've identified one company that could be on the verge of a major move higher.
Synopsys (SNPS), a leading provider of semiconductor design software and intellectual property, has spent much of the last three years consolidating following an enormous multiyear rally. Concerns over slowing growth, the integration of its massive Ansys acquisition and the potential for AI to disrupt traditional software businesses have weighed on shares.
But the outlook appears to be improving rapidly. A series of major AI partnerships with Amazon and OpenAI, stronger-than-expected long-term financial targets and increasingly bullish analyst revisions have given investors several fresh reasons to reconsider the stock.
And with shares now approaching a major breakout on the quarterly chart, the timing looks particularly interesting.
Let's take a closer look at the recent developments, Synopsys' improving earnings outlook and the technical setup that suggests another substantial rally could be approaching.
Synopsys has long occupied an important position in the semiconductor industry. Its electronic design automation software helps companies develop increasingly complex chips, while its semiconductor intellectual property allows customers to incorporate proven designs into their own processors.
That makes Synopsys a critical supplier to the AI infrastructure buildout, particularly as hyperscalers invest billions developing their own custom accelerators. And the company's recent Investor Day delivered several important catalysts.
First, Synopsys announced a major agreement with Amazon (AMZN), which will use its intellectual property across custom silicon programs including Trainium, Graviton and Nitro. Importantly, the agreement introduces a royalty-based component tied to chip production, potentially allowing Synopsys to participate more directly in its customers' growth.
Separately, Synopsys announced a partnership with OpenAI to develop GPT-Synopsys, a specialized AI model for semiconductor design.
This is an especially interesting development considering the market's concern that AI could disrupt traditional software providers. Rather than being displaced by the technology, Synopsys may be positioned to become one of its beneficiaries.
Management also delivered a stronger-than-expected financial outlook.
Fiscal 2027 revenue is projected at $11.10–$11.20 billion, above the roughly $10.81 billion analysts had expected. Non-GAAP earnings guidance of $19.04–$19.12 per share was also comfortably ahead of the prior consensus near $17.81.
Looking further ahead, management now targets roughly 15% annual revenue growth through fiscal 2030, with operating margins approaching 50% and annual adjusted EPS growth in the mid-20% range.
The company also intends to repurchase approximately $1 billion in shares over the coming months, with a longer-term goal of returning up to 50% of free cash flow to shareholders.
That's a pretty compelling combination of new growth opportunities, improving profitability and shareholder returns.
The improving fundamental outlook is already showing up in analyst estimates. SNPS currently sports a Zacks Rank #1 (Strong Buy), following a recent upgrade from #2 (Buy), with revisions accelerating after the company's Investor Day.
The most notable changes have come in fiscal 2027, with fresh upgrades hitting in the last week. Over the last 60 days, the consensus earnings estimate has increased 6.1% to $18.26 per share, with five upward revisions and one downward revisions during that period.
And there could be additional upside to those estimates. Management's new fiscal 2027 guidance calls for adjusted EPS of $19.04–$19.12, still comfortably above the current consensus.
The near-term earnings trend has also been encouraging. In its latest quarter, Synopsys reported revenue of $2.48 billion and adjusted EPS of $3.91, beating earnings expectations by approximately 6.5%.
Valuation remains a consideration, with shares trading near 33x current-year earnings and 27.5x next year's estimates. That's certainly not cheap, but with management targeting mid-20% annual earnings growth through fiscal 2030, the premium could be justified if execution remains strong.
And with estimates moving higher, sentiment improving and analysts increasingly bullish on the company's AI opportunities, the fundamental backdrop looks considerably more attractive than it did just a few months ago.
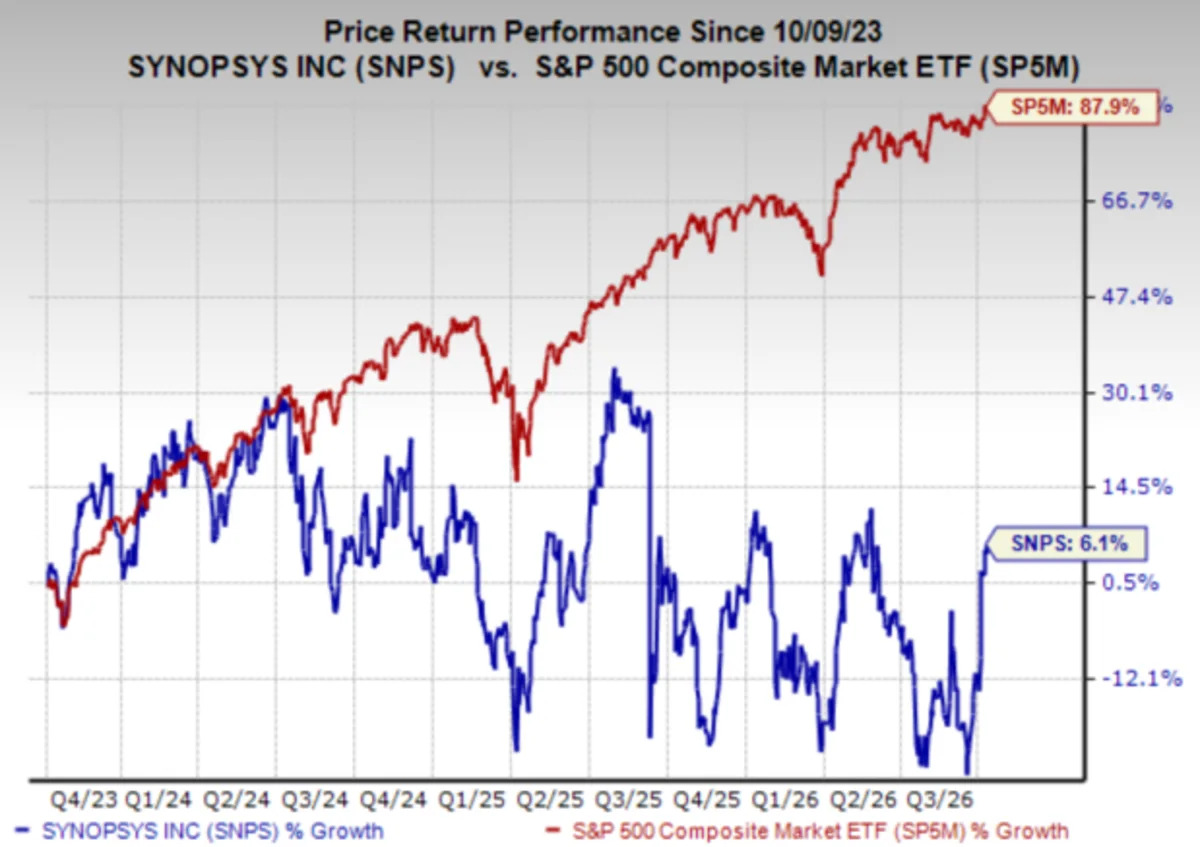
Perhaps the most compelling part of the setup is the quarterly chart.
Following a massive multiyear advance, Synopsys has spent the last several years consolidating, with shares trading in a broad descending channel since their 2024 peak.
Importantly, the long-term uptrend remains intact, and the recent rally has brought SNPS right back to the upper boundary of that consolidation, following a sharp gap up at the start of this quarter.
The stock is now testing resistance around $510–$520, a breakout above which could signal the beginning of another major leg higher.
These types of multiyear consolidations are particularly interesting when accompanied by improving fundamentals. The stock has spent years digesting its prior advance, while the latest developments suggest the underlying earnings story may be accelerating again.
Of course, the breakout hasn't been confirmed yet, and a rejection at resistance could keep shares trading within the existing range.
But with the Zacks Rank improving, estimates moving higher and several major catalysts now in place, I think the setup looks increasingly constructive.
Synopsys is emerging as an increasingly interesting way to participate in the AI infrastructure boom, particularly as custom semiconductor design becomes more important to the industry's growth.
The Amazon and OpenAI agreements, stronger long-term guidance and accelerating earnings revisions suggest the company may be entering a new phase of growth.
Meanwhile, the quarterly chart offers one of the more compelling technical setups I've come across recently.
Valuation isn't especially cheap, and the Ansys integration remains an execution risk. But with improving fundamentals and shares approaching a major multiyear breakout, SNPS looks like a stock worth watching closely.
Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Amazon.com, Inc. (AMZN) : Free Stock Analysis Report
Synopsys, Inc. (SNPS) : Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).