Nvidia Isn’t the Only Company Getting Rich From the AI Boom Vandita Jadeja Wed, October 7, 2026 at 8:00 AM EDT 5 min read CRDO +3.93% NVDA +0.14% MRVL +5.81% ALAB +7.58% Explore stocks on Coinbase Trading disclosure Trading disclosure The above button links to Coinbase. Yahoo Finance is not a broker-dealer or investment adviser and does not offer securities or cryptocurrencies for sale or facilitate trading. Coinbase pays us for certain activity generated through this link. Prices displayed are informational.
Credo Technology (CRDO) earns a BUY rating with a $263 price target, offering ~26% upside despite already surging 45% year to date.
Credo grows revenue 115% year over year yet trades at just 31x forward earnings, which is half the multiple of rivals Marvell (MRVL) and Astera Labs (ALAB).
Two customers account for over 60% of Credo's revenue, making order cuts the single biggest threat to the bull case.
Building a portfolio and living off one are two completely different skills, and almost nobody teaches the second. This problem is what The Definitive Guide to Retirement Income helps, and it is free today. Read more here. (Sponsor)
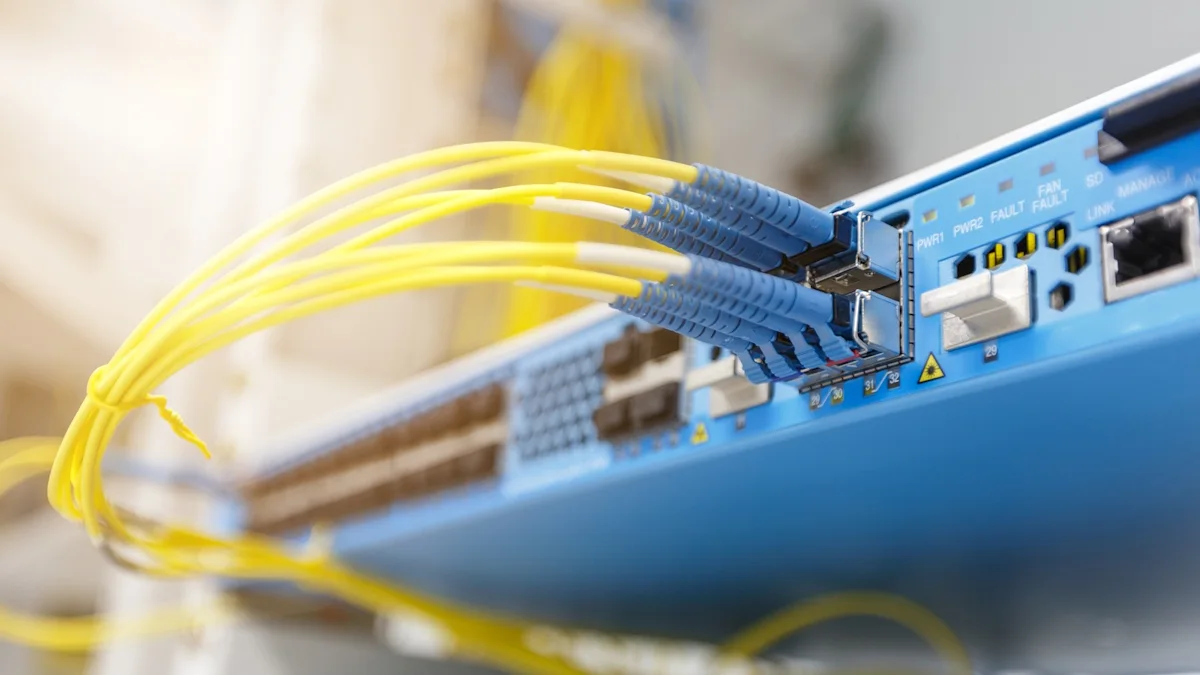
GPU makers dominate headlines, but AI clusters need the cables, optics and chips that move data between processors. Credo Technology (NASDAQ:CRDO) sells that connectivity layer to hyperscalers, and our model finds room for the stock to rise.
The 24/7 Wall St. price target for Credo stands at $263.13 over the next 12 months. That means 20.35% upside from the model's reference price of $218.64.
Shares fell 4.41% early Monday to $208.99. At that price, the upside to our target grows to 25.9%. The model rates Credo a buy at a high confidence level. Two things drive that rating: sharply rising earnings and a valuation that sits below Credo's closest connectivity peers.
Credo traded at $227.76 when it reported fiscal first-quarter 2027 results on September 1. By mid-September it had dropped to $161.49. Since then the stock has gained 26.49% over the past month. It is up 45.24% year to date and sits between a 52-week low of $86.48 and a high of $308.67.
Many successful investors eventually reach the same moment. The saving is done, the portfolio is built, and the question quietly changes from how much can I grow this to how much can I take out? Get that second question wrong and decades of good investing can come apart in a handful of years.
That is exactly what The Definitive Guide to Retirement Income helps answer. It covers what your retirement could actually cost, which income sources are worth using, and the withdrawal math that decides whether the money lasts. It is free today from Fisher Investments. Read More Here ›
The quarter itself was strong. Revenue of $479 million beat the $470.38 million consensus and rose 114.7% from a year earlier. Non-GAAP EPS came in at $1.20, ahead of the $1.17 estimate. For the full fiscal year, management expects revenue growth of more than 85% and optical revenue of more than $600 million.
The bull case reaches $335.72. Management expects zero-flap optics, silicon photonics PICs and optical DSPs to each bring in more than $100 million this fiscal year. Active electrical cables reach five hyperscalers.
Active LED cables and OmniConnect are expected to start producing revenue in fiscal 2028, with OmniConnect potentially adding "thousands of dollars of Credo content per GPU". 19 analysts give the stock bullish ratings, with consensus target of $281.09.
The bear case is $207.54. Credo's two largest customers made up 33% and 28% of first-quarter revenue. Inventory rose to $313.1 million. GAAP gross margin fell to 64.5% from 68.2%, though non-GAAP gross margin stayed at 68%.
Marvell Technology (NASDAQ:MRVL) competes with Credo directly in optical DSPs, with 79% of its revenue coming from data center sales. Even so, it trades at 62x forward earnings while growing far more slowly. Marvell holds its Investor Day on October 6, so keep an eye on what it says about connectivity demand.
Astera Labs (NASDAQ:ALAB) competes with Credo in retimers and grows at a similar rate, yet it trades at 56x forward earnings. Next to these two peers, our target looks conservative.
The 24/7 Wall St. price target of $263.13 has a buy rating and 90% confidence. Triple-digit revenue growth coupled with a forward multiple well below peers points to further upside.
Confidence would rise if optical revenue accelerates in the second half as expected, and caution would set in if a major customer cuts orders.
The 2026 figure is our 12-month target. The forecast rests on Credo continuing to execute on its optical roadmap.
Any change in hyperscaler spending on AI could move the stock well above or below these levels. Credo is one of several picks-and-shovels names benefiting from that buildout; we featured seven of these non-chipmaker AI infrastructure suppliers in a free report you can grab here.
(Sponsor) Most people spend their entire working lives focusing on one thing: growing a pile of money. Then they retire and discover the skill they actually need is close to the opposite. Turning that pile into steady income, year after year, through good markets and bad, without ever running out.
It may be the least discussed and most consequential transition in personal finance, and plenty of otherwise careful investors walk into it with no real plan. That is exactly what The Definitive Guide to Retirement Income helps answer. It is a free guide from Fisher Investments covering what your retirement will really cost, where the cash flow should come from, and how much you can safely withdraw each year. Learn more here. Learn More Here ›
Contact editorial@247wallst.com for any questions or corrections.